


Greentown China Holdings (SEHK:3900) Following Latest Sales Update, Does The Valuation Look Too Cheap?
Greentown China Holdings (SEHK:3900) has just updated investors on unaudited sales for the nine months to 30 September 2026, confirming transaction volumes across both its self-investment projects and project management operations.
The latest trading update landed as Greentown China Holdings’ share price reached HK$6.0, with a 1 day share price return of 2.74% offset by a year to date share price decline of 28.40% and a 1 year total shareholder return decline of 29.66%, pointing to short term momentum building against a weaker multi year experience where total shareholder return over five years has fallen 40.51%.
Spot opportunities beyond Greentown China Holdings by scanning a hand picked 234 resilient stocks with low risk scores that aims to pair steadier balance sheets with more resilient share price trends.Greentown China Holdings shares have bounced off recent lows, yet longer term returns remain weak and the latest sales update still sits against a loss making bottom line. Investors may now be weighing whether to step in at current levels or stay patient for potentially cheaper terms as more valuation detail unfolds.
Preferred Multiple of 0.1x P/S: Is it justified?
On the numbers available, Greentown China Holdings looks cheap against both its own fundamentals and its peers, with the stock trading at a P/S ratio of 0.1x while the last close sits at HK$6.0 and independent work suggests it is trading 79.2% below an estimated fair value.
The P/S multiple compares the market value of the equity to the revenue the business generates. For a developer with HK$141,079.334 in reported revenue and a market cap of roughly HK$15.2b, that 0.1x reading implies investors are currently paying a relatively low price for each dollar of sales.
Relative markers reinforce that point. The Hong Kong real estate industry P/S average is around 0.7x and peers cluster closer to 0.2x, while the estimated fair P/S ratio for Greentown China Holdings is 0.4x. That is a wide gap and signals the current valuation level could shift if sentiment or fundamentals change toward the fair ratio.
Explore the SWS fair ratio for Greentown China Holdings.
Result: Price-to-sales of 0.1x (UNDERVALUED)
Still, Greentown China Holdings carries clear risks, including a loss of CN¥57.203 in net income and annual revenue growth that declined about 10%, which could limit the potential for any rerating.
Find out about the key risks to this Greentown China Holdings narrative.
Another View: SWS DCF model points to deeper undervaluation
The P/S ratio makes Greentown China Holdings look cheap already. The SWS DCF model goes further, with an estimated future cash flow value of HK$28.91 per share versus the current HK$6.0 price. This implies a very large discount and raises the question of what risks the market is pricing in.
Look into how the SWS DCF model arrives at its fair value.
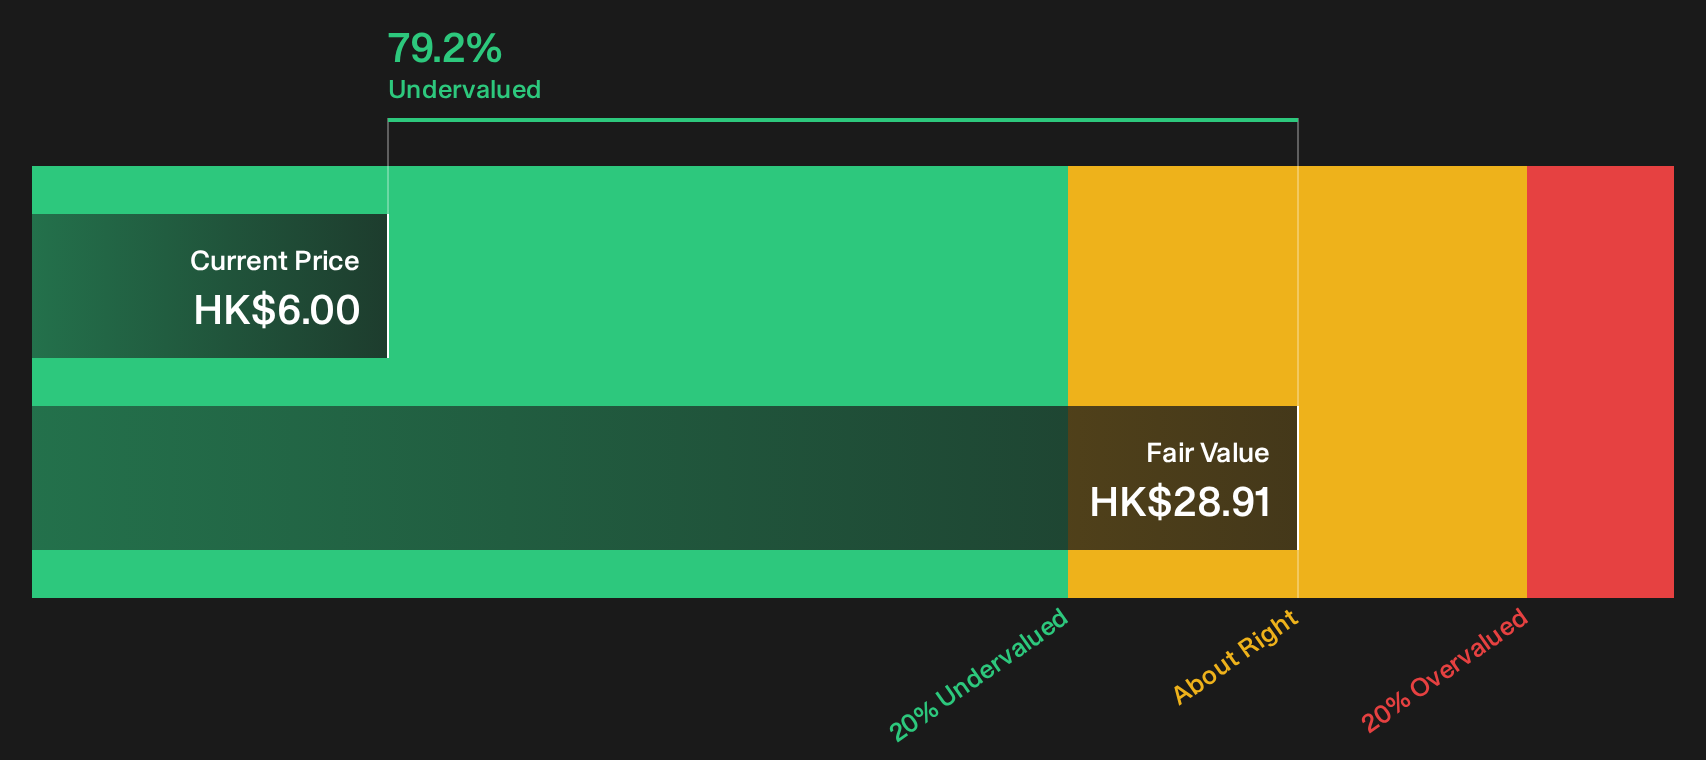
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Greentown China Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Greentown China Holdings can create both hesitation and opportunity. Consider reviewing the details for yourself promptly, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Greentown China Holdings?
Greentown China Holdings might be on your radar already, but casting a wider net can help you spot opportunities you would otherwise miss.
- Target value first by scanning a 191 high quality undervalued stocks that focuses on companies with solid fundamentals trading at lower prices than their underlying metrics might suggest.
- Strengthen your defense by checking a list of solid balance sheet and fundamentals (204 results) that spotlights businesses with healthier finances that may better handle tougher conditions.
- Hunt for tomorrow's quiet overachievers using a 614 high quality undiscovered gems built to surface quality stocks that have not yet attracted much attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com