


Aker BP (OB:AKRBP) Reports Stronger Q3 Volumes, Is The Upside Already Priced In?
Aker BP (OB:AKRBP) has drawn fresh attention after reporting preliminary third quarter 2026 figures, with net volume sold at 395.7 mboepd, compared with 375.7 mboepd in the previous quarter.
Aker BP’s recent trading update has landed while momentum in the shares is already strong. The NOK372.1 share price is supported by a 14.77% 90 day share price return and a 43.17% year to date share price return, alongside a 64.85% 1 year total shareholder return that points to investors reassessing both its operational progress and risk profile.
Scan how Aker BP’s trading update compares with other oil and gas producers on our hand picked list of list of solid balance sheet and fundamentals (204 results) to see what else fits your criteria.
Aker BP’s sharp run and fresh production data now set up a tougher question for new money. Does the current price still leave enough upside in the risk reward to justify buying more exposure here?
Most Popular Narrative: 13% Overvalued
Aker BP’s NOK372.1 share price sits above the most followed fair value estimate of NOK329.25, which frames the current debate around how much future execution is already reflected in the quote.
Aker BP aims to sustain production above 500,000 barrels per day beyond 2030, driven by their 2 billion barrel opportunity and projects like Yggdrasil and Johan Sverdrup. This supports long-term revenue growth through extended production capacities.
See why 42 investors see Aker BP as 13% overvalued.
The most followed framework uses a 6.65% discount rate and assumes revenue growth of about 4.1% a year, profit margins rising toward 13.5% and a future P/E of 14.6x to arrive at a fair value of NOK329.25. With Aker BP trading above that level, this lens suggests the recent price strength already bakes in a good portion of the expected project delivery, digital efficiency gains and low emission developments. It also indicates there may be less room for missteps on capex, emissions costs or project timing.
Result: Fair Value of NOK329.25 (OVERVALUED)
Still, the whole story can change quickly if emissions costs rise faster than expected or if major projects such as Yggdrasil or Wisting run into delays.
Find out about the key risks to this Aker BP narrative.
Another View: Aker BP Through The Cash Flow Lens
The fair value debate around Aker BP does not end with the NOK329.25 narrative and P/E based work. Our DCF model prices the shares at NOK634.86, which is well above the NOK372.1 quote and identifies the stock as undervalued on this framework. Which signal do you consider more relevant?
Look into how the SWS DCF model arrives at its fair value.
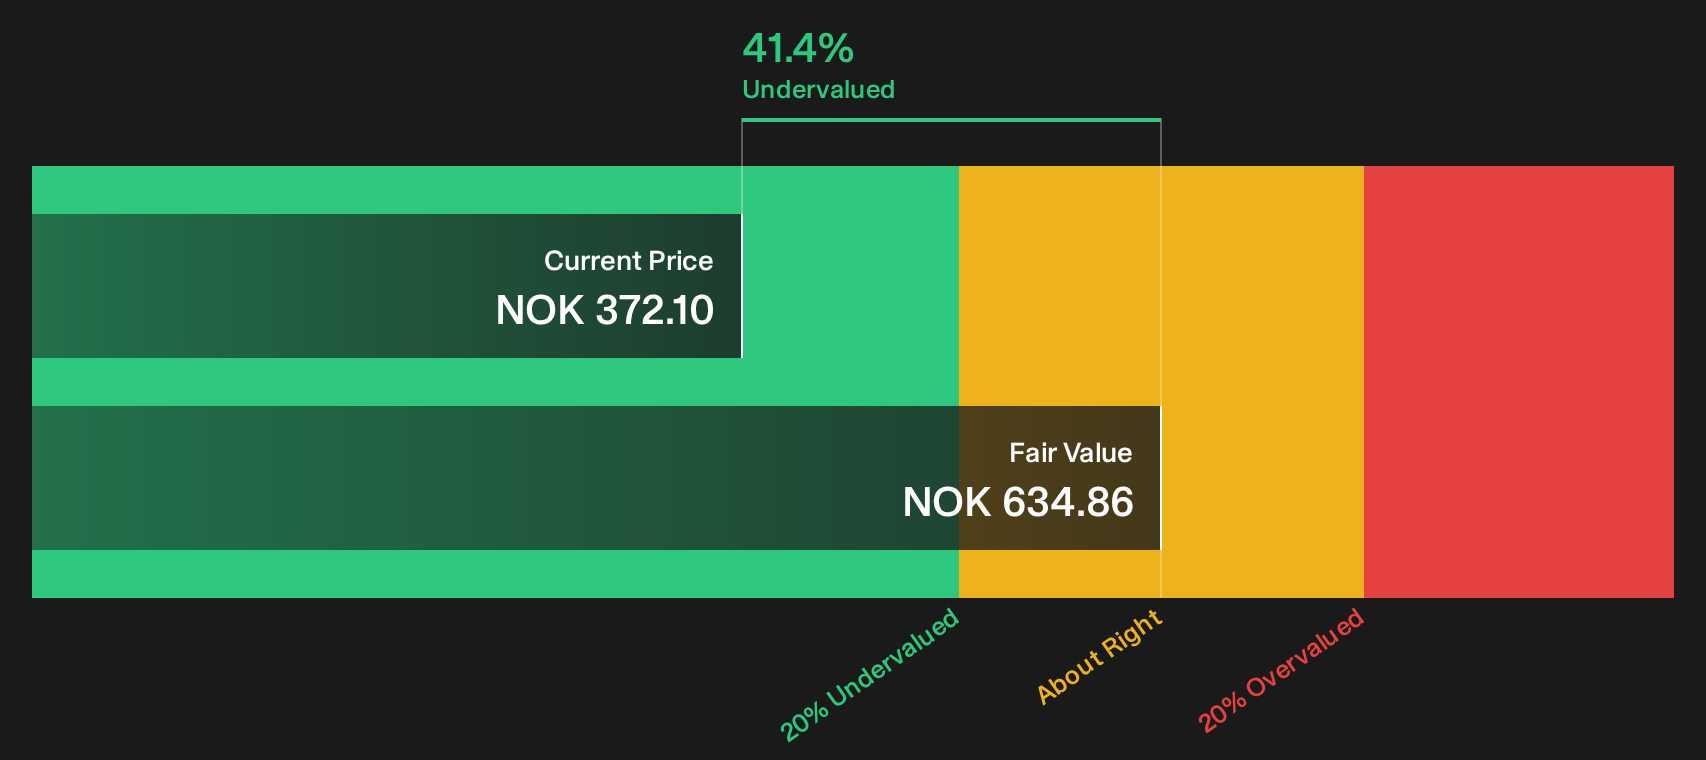
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aker BP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Aker BP’s value leave you unsure, use that tension as a cue to move fast and review the numbers yourself. Start by weighing the upside potential and downside flags side by side through 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Aker BP?
If Aker BP has sharpened your focus, do not stop there. Use the screener to surface other businesses that fit your preferred mix of risk, value and income.
- Target resilient balance sheets and steady fundamentals by running a focused search through our list of solid balance sheet and fundamentals (204 results).
- Hunt for quality at a reasonable entry point by filtering companies using the 191 high quality undervalued stocks.
- Build a cash flow focused watchlist by screening for income opportunities with the 216 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com