


Caught Out By PolyNovo's Fall? Here's What The Bears Saw
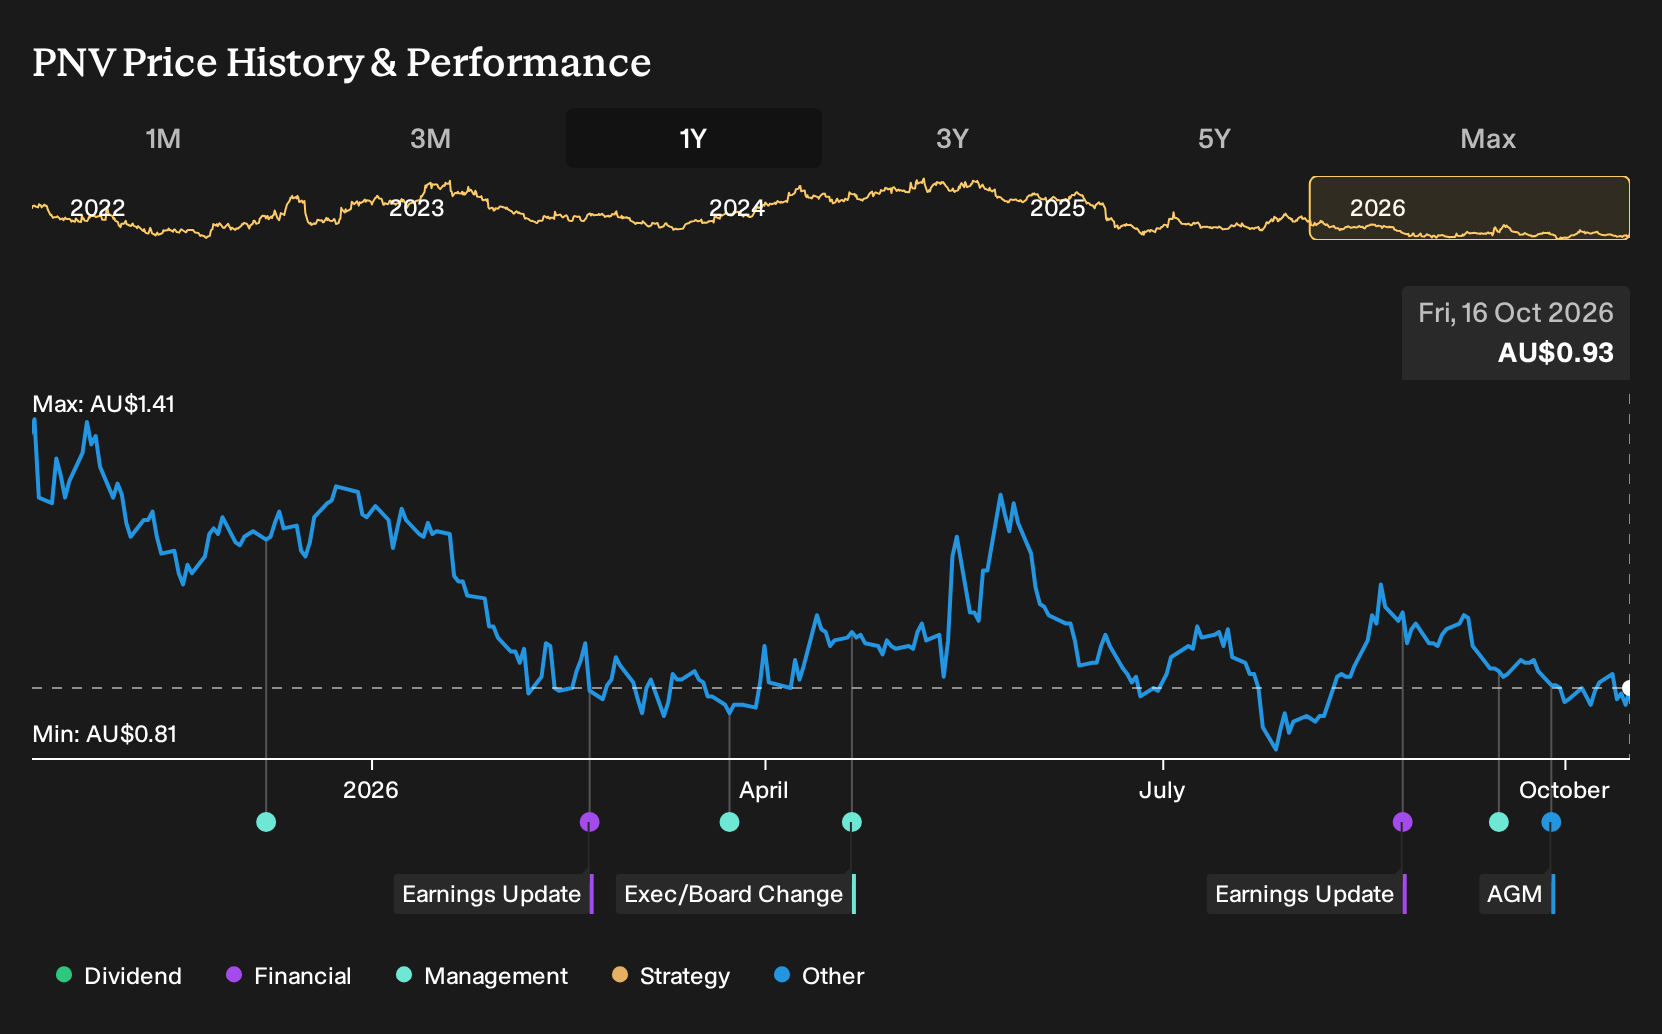
If you had looked at PolyNovo in October 2025 and decided to sit it out, the decision may feel very different today. Holding PolyNovo over the past year would have meant a 26.9% loss, including dividends. Over that same stretch, H2 2026 results showed higher revenue but a lower net margin than H2 2025. If you rewind to the start, which expectation on growth versus profitability could you have stress tested more closely?
If the move has made PolyNovo harder to judge, start where the gap is still open and scan 5 high quality undervalued stocks.
The Two PolyNovo Stories Investors Had To Weigh
The shares cost A$1.41 at the start of the period, and PolyNovo sat between two very different stories about where the business could go next.
On the bullish side, one camp saw aging populations lifting demand for advanced tissue care and pointed to a Fair Value of A$2.60. This was the price that view implied if its assumptions played out, built on recurring revenue from faster MTX adoption and broad international uptake.
The bearish narrative argued that global cost pressures and tighter regulation could squeeze pricing and margins, with a Fair Value of A$1.15 tied to the risk that reimbursement pressure and rising manufacturing costs would crimp profitability.
What The PolyNovo Results Actually Put To The Test
The clearest data point was PolyNovo’s H2 2026 report, where total revenue reached A$79.522m compared with A$69.164m in H2 2025. Net income moved to A$7.338m from A$9.876m and net margin slipped from 14.3% to 9.2%. That pattern cut both ways, supporting the growth story while challenging the high-margin part of the bullish case.
The key lesson is to link each upbeat story to a specific figure. When a thesis leans on operating leverage and pricing power, track net margin across periods, not just revenue, to see whether the profitability assumption is actually holding.
What PolyNovo’s Share Price Drop Now Asks You To Believe
PolyNovo now trades at A$0.93, with the selected Narrative’s Fair Value sitting above that level based on its own assumptions and modelling. The core pitch is that NovoSorb’s use broadens across complex wounds while current manufacturing capacity and cash generation support that expansion.
The critical assumption a buyer must examine is whether PolyNovo can turn its existing footprint and manufacturing base into sustained high margin NovoSorb growth in non burn complex wounds.
"The main thing that has to go right is converting the existing commercial footprint, manufacturing capacity and upcoming regulatory and reimbursement milestones into deeper penetration of non burn complex wounds across the US and Rest of World markets."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 32% below our estimate - sells consumer electronics and appliances through retailers while adding subscription-based digital services.
- Company 2 - 29% below our estimate - supplies commercial vehicle fleets with replacement components plus technical support when breakdowns occur.
- Company 3 - 48% below our estimate - designs and installs integrated audio visual, power and data infrastructure for complex commercial builds.
Those are three of them. See every one of the 12 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com