


Humana (HUM) Reshapes CenterWell As Fair Value Still Points Higher
Humana (HUM) just reshaped its CenterWell primary care footprint, with BlackRock funds agreeing to acquire WCAS’s stake in nearly 150 clinics and to form a new joint venture that adjusts funding, risk sharing, and future ownership options.
Humana’s latest clinic joint venture arrives after a powerful run, with the share price up 56.22% year to date and a 1-year total shareholder return of 51.87%, even though the stock has eased 4.33% over the past week and 4.41% in the last session. This hints that short term enthusiasm is cooling while longer term momentum remains intact.
Scan how Humana’s CenterWell deal compares with other healthcare operators by reviewing a hand-picked set of list of solid balance sheet and fundamentals (25 results) that may benefit from similar capital and balance sheet strength.
Humana now trades below both analyst targets and some intrinsic value estimates after a sharp run followed by a recent pullback. Is that discount compensation for real risk, or has caution on CenterWell concerns gone too far?
Most Popular Narrative: 4% Undervalued
Humana closed at $413.16 while the most followed narrative pegs fair value near $430.70, so the story hinges on whether margin repair and Stars execution really hold together.
Humana’s multiyear Medicare Advantage margin restoration plan that targets at least a 3% pretax margin by 2028, including 2027 bid discipline and exits from about 600,000 lower return plans with an aim to recapture a significant portion into higher value products, may influence earnings and net margins. Growth in value-based models, particularly through the expansion of CenterWell and Medicaid services, is contributing to robust year over year patient and membership growth, which may affect revenue.
See why 60 investors see Humana as 4% undervalued.
Result: Fair Value of $430.70 (UNDERVALUED)
Still, that 600,000 member Medicare Advantage exit and ongoing scrutiny of coding and Stars quality scores could unsettle Humana’s margin restoration story if outcomes disappoint.
Find out about the key risks to this Humana narrative.
Another Take On What Humana Is Worth
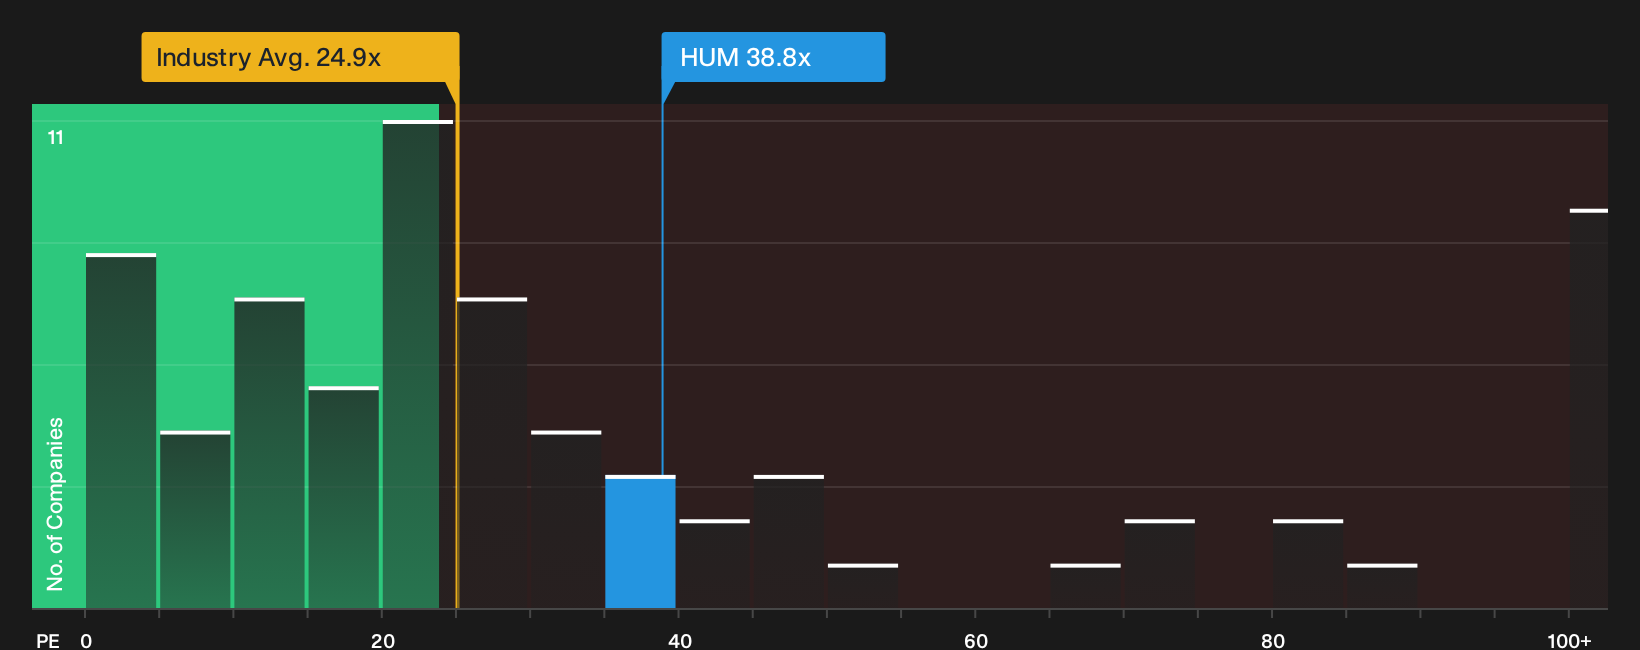
DCF work and fair value narratives paint Humana as undervalued. Yet on plain earnings, the picture is less forgiving. The stock trades on a P/E of 38.8x versus about 24.9x for both the US Healthcare industry and close peers, while the fair ratio sits higher at 47.4x.
That gap means investors are already paying a premium to the sector on current earnings, even if the fair ratio suggests the market could still move toward a richer multiple. The real question is whether you think future profit delivery justifies leaning into that valuation risk or waiting for the P/E to reset closer to peers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Humana story so far. Move quickly, review the full dataset, and stress test both sides of the debate with 2 key rewards and 2 important warning signs.
Looking for more Humana-sized investment ideas?
Do not stop your work at Humana alone. Broaden your opportunity set with a few focused stock lists that can spark fresh ideas before the next move hits.
- Target quality at a discount and scan a curated batch of potential mispriced opportunities through the 33 high quality undervalued stocks.
- Strengthen your downside protection and filter for companies with cleaner finances using the 32 resilient stocks with low risk scores.
- Hunt for future leaders early and sort through a focused pool of under-the-radar candidates via the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com