


Lonking Holdings (SEHK:3339) Could Be 33% Below Fair Value As Guidance Improves
Why Lonking Holdings’ Updated Guidance Matters Now
Fresh guidance from Lonking Holdings (SEHK:3339) flagging higher first half revenue and net profit has quickly become the main talking point for investors tracking the construction machinery sector.
The update points to a stronger earnings base supported by contract backed equipment sales and finance leases. This puts Lonking Holdings on the radar for investors who care about dividend durability and recurring cash flows.
Lonking Holdings’ share price has slipped 11.31% over the past month, even though the 1-year total shareholder return sits at 10.74% and the 3-year total shareholder return is very large at around 17x. This suggests that the recent weakness comes after a powerful longer term run.
Compare Lonking Holdings’ contract backed cash flows with other machinery and capital goods stocks using our handpicked list of solid balance sheet and fundamentals (204 results) for ideas with similar fundamentals.
A first half earnings base that looks firmer, a share price that has pulled back, and a long run total return that is already very large. Does Lonking Holdings still offer a favourable risk reward at this level?
Preferred P/E of 7.4x: Is it justified?
Lonking Holdings closed at HK$2.94, and on that price the stock trades on a P/E of 7.4x. That level screens as inexpensive when put against both the Hong Kong machinery industry average of 11.6x and a peer group average of 10.7x.
The P/E ratio compares Lonking Holdings’ share price to its earnings per share. For an equipment maker with HK$12,277.1m in revenue and HK$1,441.9m in net income, it gives a simple way to see how much investors are paying for each dollar of profit in a sector where earnings quality and cyclicality matter.
Earnings have grown by 3.9% per year over the past 5 years, with a sharper 21% increase over the past year. Net profit margins currently sit at 11.7%, slightly above last year’s 11.4%, and earnings are forecast to grow by 8.53% per year. Set against that profile, a 7.4x P/E level suggests the market is not placing a high premium on Lonking Holdings’ recent acceleration in profit growth.
The P/E of 7.4x is also described as expensive compared to an estimated fair P/E of 7.4x from the SWS fair ratio framework. That implies the current multiple is already in line with a level the market could move towards based on broader valuation patterns, even if it still looks cheaper than sector and peer averages.
Explore the SWS fair ratio for Lonking Holdings.
Result: Price-to-Earnings of 7.4x (ABOUT RIGHT)
Still, the Lonking Holdings story can shift quickly if construction demand in Mainland China weakens further or if finance lease customers struggle to meet payments.
Find out about the key risks to this Lonking Holdings narrative.
Another View: SWS DCF Points To Deeper Value
The earnings based multiple paints Lonking Holdings as roughly fairly priced, yet the SWS DCF model tells a different story. On that framework, the stock at HK$2.94 is trading below an estimated future cash flow value of HK$4.39, implying a sizeable valuation gap that raises a simple question: Is the market giving enough credit to Lonking Holdings’ cash flow potential or overcompensating for sector risk?
Look into how the SWS DCF model arrives at its fair value.
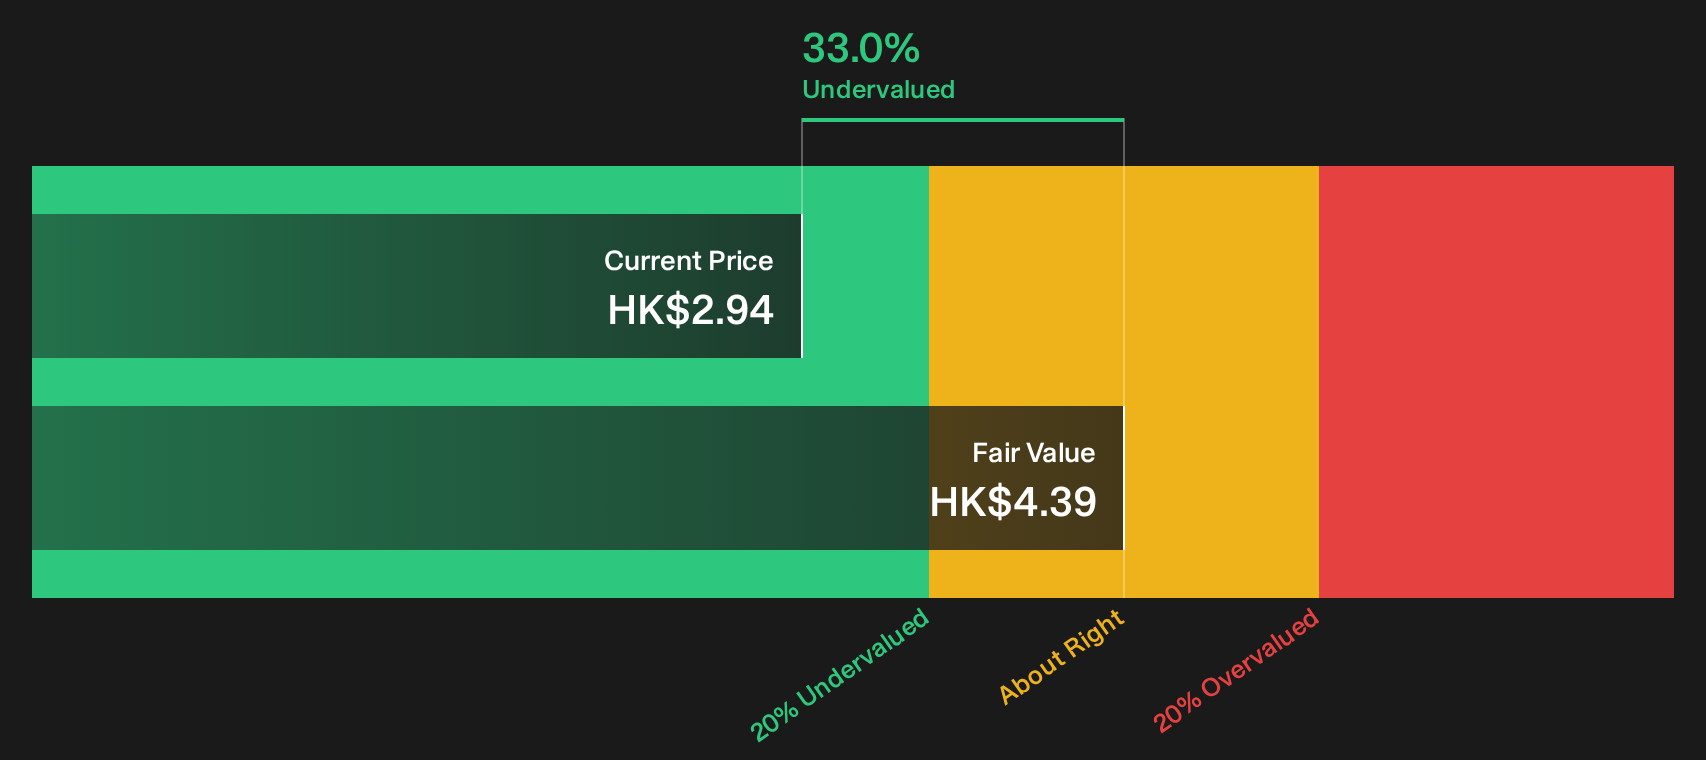
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lonking Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of firmer guidance, a pullback in Lonking Holdings’ share price and contrasting valuation signals feels mixed, act quickly and stress test the story against your own thresholds, then round it out by weighing the 3 key rewards and 1 important warning sign.
Looking for more Lonking Holdings sized ideas?
If Lonking Holdings has sharpened your focus on pricing and quality, do not stop here. Broader idea hunting now can shape your next few portfolio moves.
- Target potential mispricings by scanning companies that trade below their implied worth using the 191 high quality undervalued stocks.
- Build a steadier income stream by filtering for businesses that match your payout expectations through the 216 dividend fortresses.
- Tighten your downside risk by concentrating on financially robust operators with the 234 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com