


Does Higher Solar Output Change The Bull Case For Rubis Stock (ENXTPA:RUI)?
- Rubis reported first half 2026 operating results for its Photosol unit, with electricity production of 343 GWh compared with 269 GWh a year earlier.
- This higher Photosol output shows that Rubis’ renewable energy arm is becoming a more meaningful contributor within the broader energy portfolio.
- We will now look at how Rubis' higher Photosol electricity production could influence the broader investment narrative around its energy mix.
Scan how Rubis' push into renewables compares with peers by lining it up against our hand-picked 42 power grid technology and infrastructure stocks shaping the future of electricity infrastructure.
Rubis Investment Narrative Recap
Owning Rubis means believing the group can keep earning solid cash flows from fuel distribution while gradually building a credible renewable power arm. The jump in Photosol electricity production to 343 GWh in the first half of 2026 feeds that second leg of the story. The key short term focus still sits on how efficiently Rubis integrates this solar capacity without letting development spending drag too hard on margins.
The biggest immediate swing factor remains operating conditions in Africa and the Caribbean, where inflation, FX moves and politics can hit profitability fast. Execution risk on renewables runs alongside that, especially if energy purchase prices or regulation in Europe move against solar projects. The latest Photosol figures help the long term transition case but do not remove those pressures.
In this context, the Photosol update is the announcement that matters most for the current catalyst mix. Rubis is trying to show that renewable electricity production can scale from a relatively small segment, with €67.5m of revenue, into something that meaningfully complements fuel distribution. Higher generated volumes support that aim by pointing to better asset utilisation.
For you as a shareholder, the operational question is whether this growing solar base eventually offsets earnings pressure from regions dealing with hyperinflation and currency swings. That balance will influence how comfortably Rubis manages its high debt load while still funding new projects. Analyst expectations of moderate earnings and revenue growth already assume decent execution, so any stumble on project delivery or regulation would quickly matter.
Rubis' current analyst storyline points to forecast revenue of €7.8b and expected earnings of €353.2 million by 2029. That framework assumes revenue growth of 5.9% per year and an earnings increase of about €44.4 million from current earnings of €308.8 million.
Uncover how Rubis' fair value indicates an 11% potential upside to its current price that could narrow quickly.
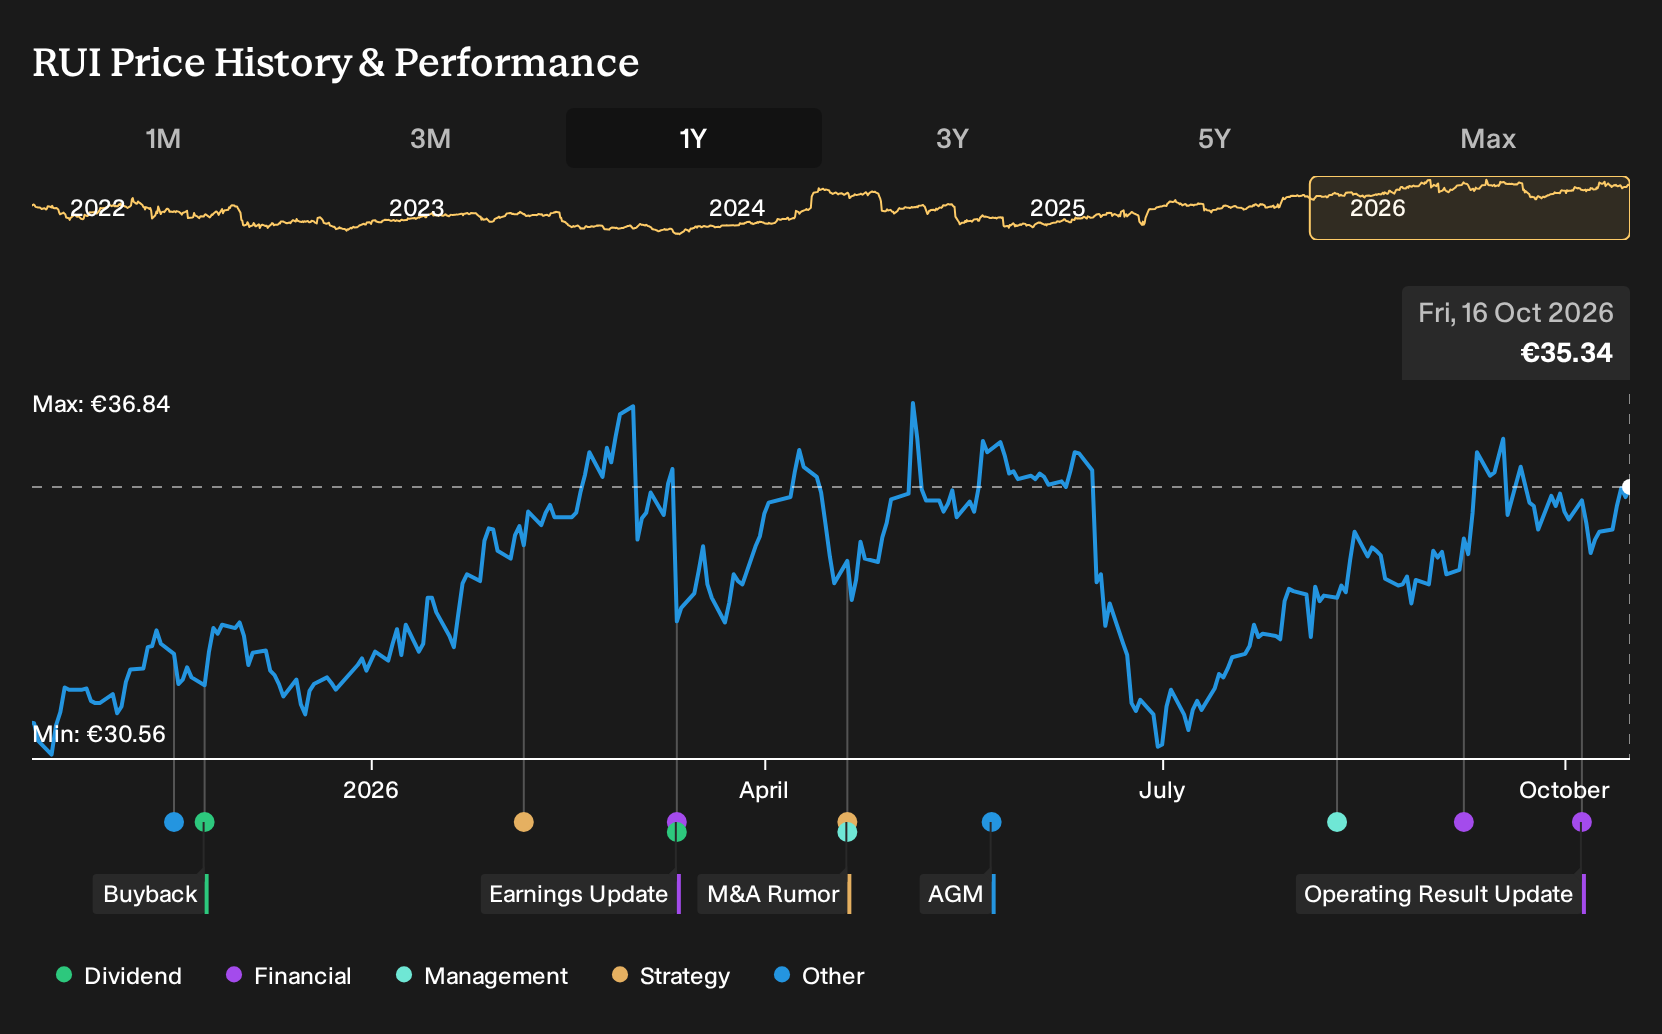
Exploring Other Perspectives
One alternate view treats Photosol’s project execution as the real swing factor. The most optimistic analysts were already pencilling in revenue of €8.7b and earnings of €426.0 million by 2029, compared with the baseline €7.8b and €353.2 million. You can treat today’s higher Rubis solar output as a fresh test of those upper range assumptions.
Explore 2 other Rubis fair value estimates, including one that suggests as much as 39% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Rubis research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rubis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rubis' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rubis?
Rubis might be central to your research today, but a stronger portfolio usually comes from comparing several opportunities side by side. Use the Simply Wall St Screener to quickly filter listed businesses down to a focused shortlist that actually fits your goals.
- If capital protection is front of mind, start with companies that score well on resilience and risk to see 234 resilient stocks with low risk scores.
- Income focused investors can zero in on higher yielding opportunities while still keeping an eye on quality through 216 dividend fortresses.
- For those hunting for future leaders that are not yet widely followed, filter for under-the-radar businesses with solid fundamentals using 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com