


Rio2 (TSX:RIO) Is Back In Focus, But What Is The Market Watching?
Rio2 (TSX:RIO) is back on investor screens as attention clusters around the Fenix Gold project's development and commissioning progress, with traders weighing execution risk, potential future cash generation, and balance sheet flexibility following recent price moves.
Recent trading tells two stories. The 1-day share price return of 1.67% and 90-day share price return of 14.72% suggest interest around Fenix is building again, even though the 30-day share price return is down 16.48% and the year-to-date share price return is down 9.79%. At the same time, the 1-year total shareholder return of 51.24% and very large 3-year total shareholder return signal that long-term holders in Rio2 have already captured a strong payoff from earlier entry points.
Scan how Rio2 compares to other potential breakouts in precious and base metals by reviewing our curated list of 36 elite gold producer stocks.
Recent gains, a sharp 30-day pullback, and a very large 3-year total return leave Rio2 at an awkward crossroads. Does it make more sense to step in after this slip or wait for a deeper reset as Fenix progresses?
Most Popular Narrative: 49% Undervalued
On the most followed valuation view, Rio2 is priced well below its implied worth, with the CA$3.04 last close set against a CA$6.00 fair value estimate that anchors the debate around how much Fenix and Condestable could contribute over time.
Rio2 appears significantly undervalued relative to its long-term earnings potential. Based on the platform’s future estimates, the company is expected to generate US$562.2 million in earnings by 2030, supported by strong revenue growth reaching US$5.85 billion. Applying a conservative 16.86× P/E multiple to these projected earnings results in an implied 2030 market capitalization of US$9.48 billion, or US$5.98 per share. When this valuation is discounted back to 2025 at 6.46% per year, the intrinsic value becomes US$4.37 per share. Converted at the current USD/CAD exchange rate of 1.3725, this corresponds to a fair value of approximately CA$6.00 per share. Compared to the current market price, this suggests that Rio2 is trading at a 53.7% discount to its estimated intrinsic value. The gap reflects the market’s cautious view of early-stage developers, while the model incorporates the company’s expected transition into a meaningful gold producer with strong future cash flows.
See why 4 investors see Rio2 as 49% undervalued.
Result: Fair Value of CA$6.00 (UNDERVALUED)
Still, Rio2 depends heavily on advancing Fenix and Condestable as planned, and any setback in permitting, capital access, or project execution could quickly shrink that implied upside.
Find out about the key risks to this Rio2 narrative.
Another View On Rio2’s Valuation
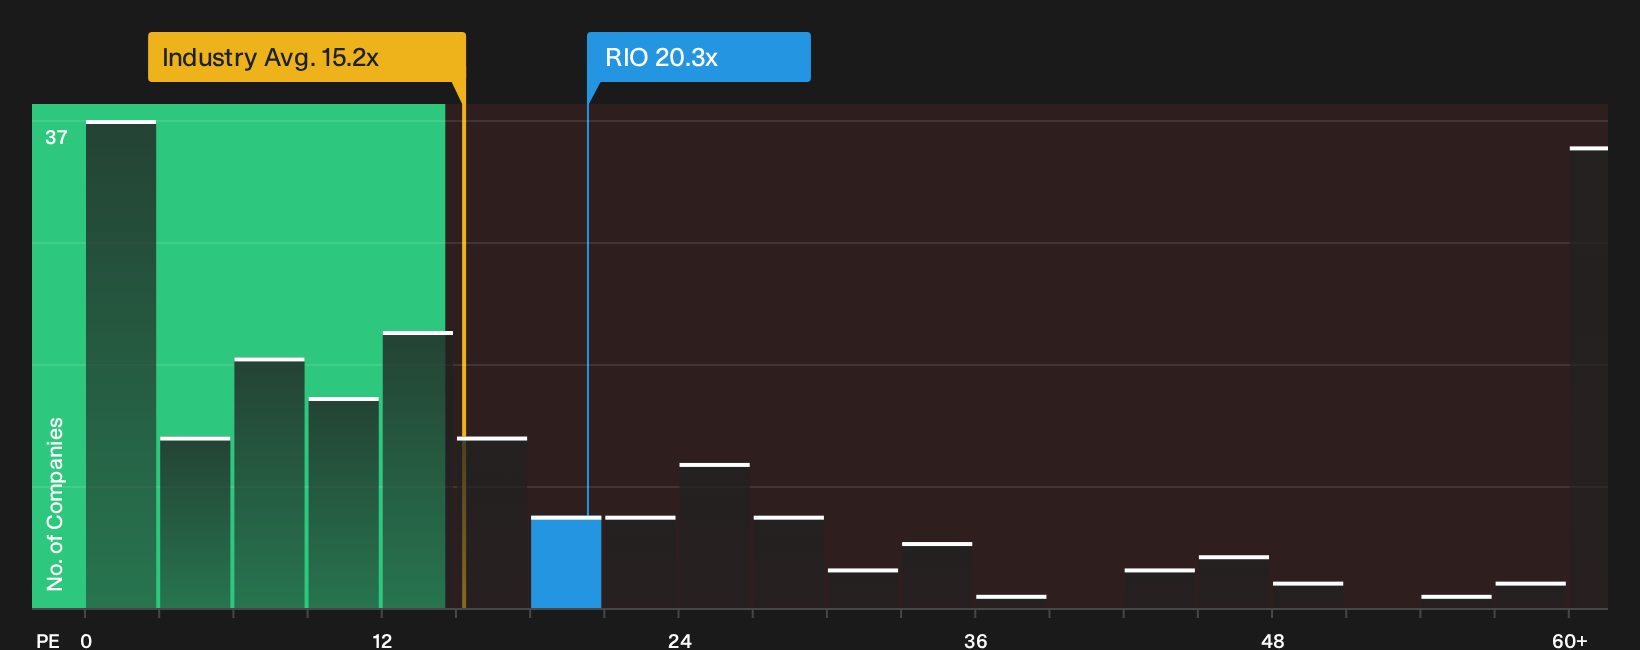
That CA$6.00 fair value pitch makes Rio2 look cheap, yet the market is not treating it like a clear bargain. The stock trades on a 20.3x P/E, richer than the Canadian Metals and Mining sector at 15.2x, although still below peers at 34.7x and under a 24.4x fair ratio that the market could eventually lean toward.
This split between a strong discount to fair value and a higher P/E than the wider industry points to valuation risk as well as potential reward. Is the market slowly pricing in future growth, or simply overpaying for a story that still has plenty to prove?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Rio2’s valuation story so far. If you want to act before sentiment shifts again, consider both perspectives starting with 4 key rewards and 1 important warning sign.
Looking for more Rio2-sized opportunities?
Do not stop at Rio2. Use the Simply Wall Street Screener to quickly surface fresh ideas that match your risk appetite, time horizon, and return goals.
- Target resilient potential value plays by scanning our 5 high quality undervalued stocks that pair quality fundamentals with pricing that may not fully reflect their underlying strengths.
- Prioritise capital protection first and hunt through a curated set of 8 resilient stocks with low risk scores designed for investors who refuse to compromise on stability.
- Spot future leaders early by reviewing a focused pool of 10 high quality undiscovered gems before they attract broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com