


Atlanticus Holdings (ATLC) Revenue Stays Strong, Is The Stock Still Undervalued?
Atlanticus Holdings stock reacts to recent performance data
Atlanticus Holdings (ATLC) has drawn fresh attention after recent performance data highlighted annual revenue of US$730.5m and net income of US$144.8m, prompting investors to reassess how the fintech lender is currently valued.
The share price of Atlanticus Holdings has eased in the short term, with the stock slipping around 6% over the past 90 days even as the year-to-date share price return is up 38.7% and the 1-year total shareholder return sits at 71.3%. This mix of cooling near term momentum and strong multi-year total shareholder returns, including a 3-year figure above 200%, suggests recent moves are more about investors recalibrating risk and reward at the current US$92.02 level than a wholesale shift in how the business is viewed.
Scan similar consumer finance players showing strong multi year returns and tightening valuations with our hand picked 33 high quality undervalued stocks.
Atlanticus Holdings is putting up solid revenue and profit figures, yet the share price has cooled in recent months. Is this still a strong fintech lender trading on a fair tag, or has enthusiasm run ahead of reality?
Most Popular Narrative: 31% Undervalued
Analysts following Atlanticus Holdings frame the recent US$92.02 share price against a narrative fair value of $133.50, which implies the current valuation trails their earnings and revenue expectations for the business.
The acquisition and integration of Mercury Financial has roughly doubled the balance sheet to about US$7b and brought a US$3b portfolio under Atlanticus portfolio management methods. Management expects this to support higher yields and return on assets over time, directly influencing revenue and earnings.
See why 5 investors see Atlanticus Holdings as 31% undervalued.
Result: Fair Value of $133.50 (UNDERVALUED)
Still, Atlanticus Holdings depends heavily on near prime borrowers and a smooth Mercury integration. As a result, weaker repayment trends or delayed cost savings could challenge that upbeat valuation story.
Find out about the key risks to this Atlanticus Holdings narrative.
Another view on Atlanticus Holdings valuation
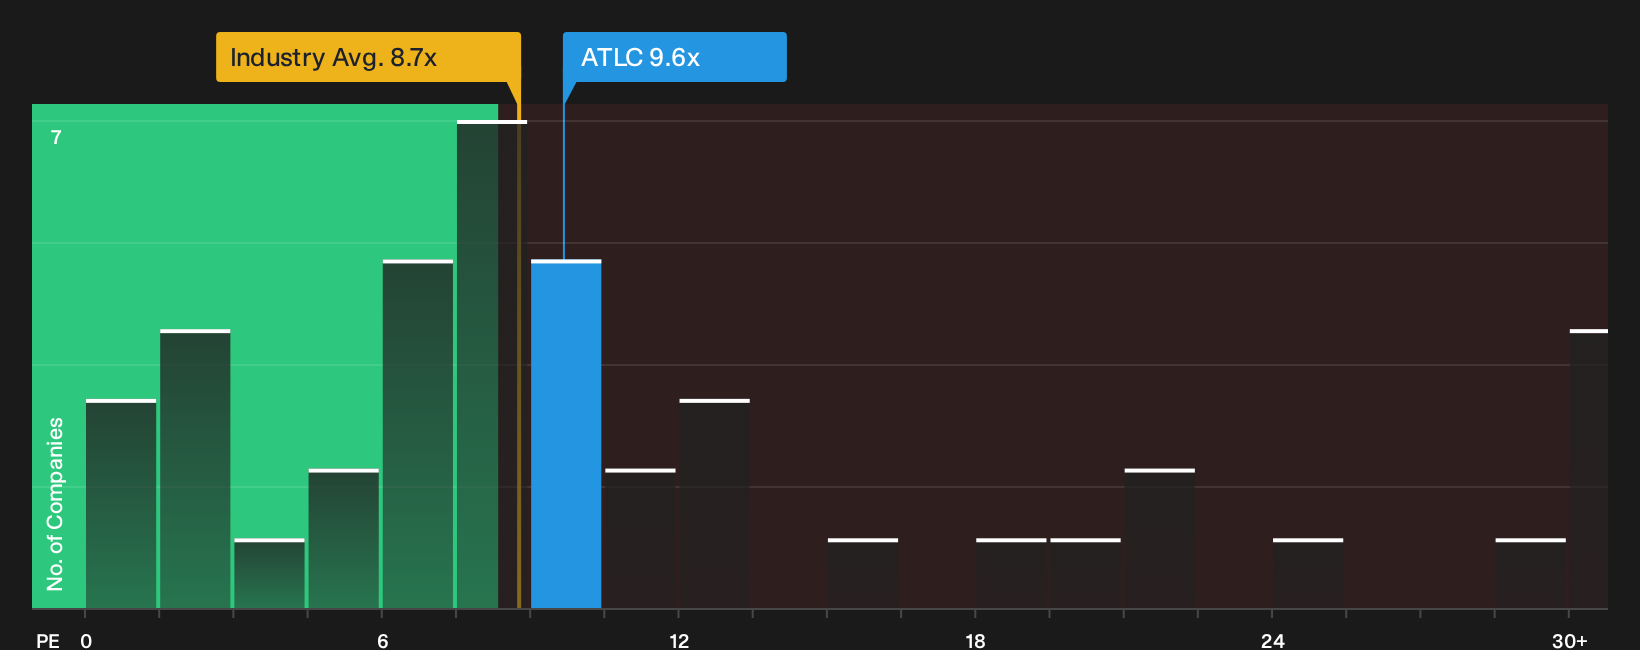
Analysts see Atlanticus Holdings as 31% undervalued against a fair value of $133.50, yet the market is already paying a P/E of 9.6x. That is higher than the US Consumer Finance industry at 8.7x, but lower than the 16.6x peer average and the 17.1x fair ratio estimate. For investors, does that mix signal a margin of safety or a market that is already pricing in a lot of good news?
Before leaning too hard on any one earnings multiple, it is worth testing these assumptions against a full valuation breakdown that compares industry, peer and fair ratio gaps, and shows how much room is left for error or upside: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on the Atlanticus Holdings valuation story so far. If you want to move fast and base your view on the full picture, check the 3 key rewards and 1 important warning sign
Looking for more Atlanticus Holdings style investment ideas?
If Atlanticus Holdings has sharpened your focus on valuation and risk, do not stop here. Fresh ideas now can shape returns for years.
- Target potential mispricing early and review companies that screen as financially strong yet underappreciated using the 33 high quality undervalued stocks.
- Build a steadier cash flow stream and examine businesses that show up in the 8 dividend fortresses.
- Prioritise resilience first and scan companies highlighted in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com