


Is Q3 Earnings Preview Altering The Investment Case For Ares Management (ARES)?
- Ares Management plans to report fiscal Q3 2026 results on October 29 after posting Q2 figures that exceeded consensus, supported by record fundraising and fresh capital inflows into its alternative investment platforms.
- The firm’s fee engine, backed by strong capital raising and resilient earnings, is drawing interest as investors look for more defensive financials exposure.
- We will look at how Ares Management's upcoming Q3 earnings update shapes the investment narrative built on fundraising driven fee growth.
Scan other defensive financials that rely on fees and fundraising strength, similar to Ares Management, by reviewing our curated list of 32 resilient stocks with low risk scores.
Ares Management Investment Narrative Recap
Ares Management appeals to shareholders who believe its fee driven model on private credit and real assets can keep converting fundraising into more stable earnings. The near term hinge is whether Q3 2026 results show that record Q2 inflows are turning into fee paying assets at a healthy pace, which would support the existing earnings growth profile.
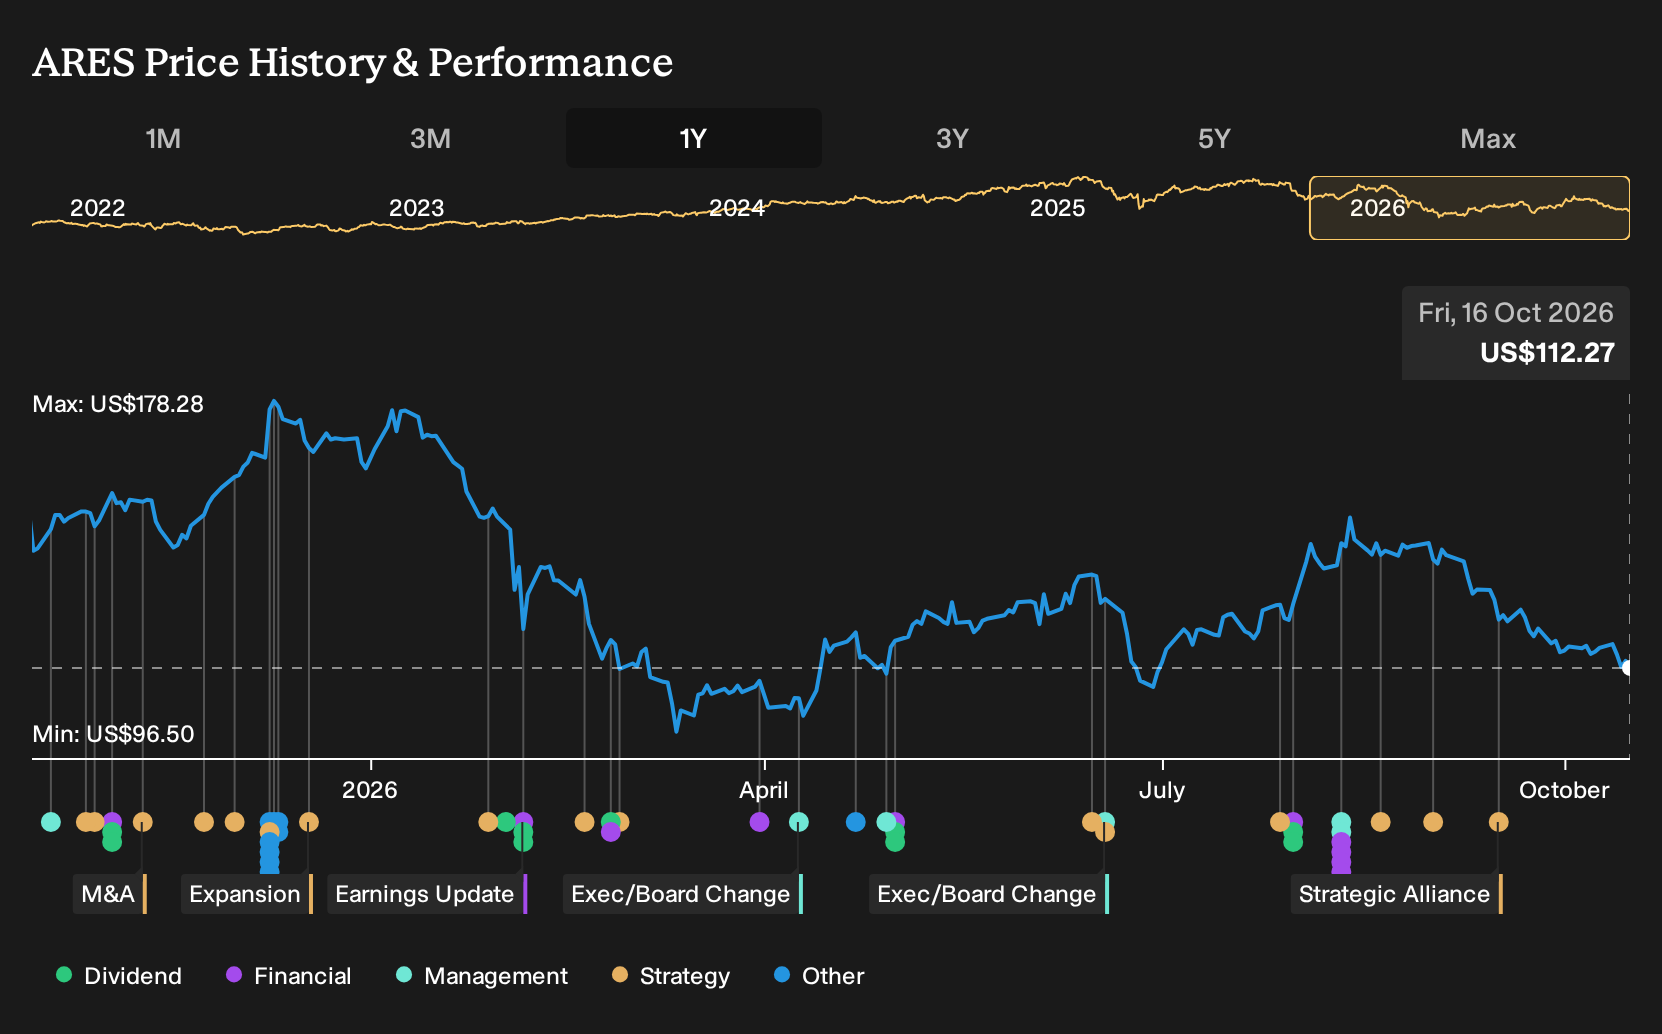
The sharp pullback in ARES, with the share price down 33% year to date, puts the spotlight on risks rather than the headline growth story. The biggest watchpoint is pressure in wealth channel products or weaker cash generation, which could stress dividend coverage and amplify existing concerns about a rich P/E multiple.
The upcoming Q3 2026 release is the key fresh data point. It follows Q2 results that beat expectations and highlighted US$36b of fundraising and about US$170b of dry powder, which matter directly for fee related earnings and deployment. Investors will want to see that fundraising momentum and deployment discipline are both holding up rather than pulling in opposite directions.
Recent commentary around Morgan Stanley’s US$149 Ares Management price target adds context but does not change the core operational questions. The focus remains on whether Ares uses its balance sheet and undeployed capital carefully, keeps a lid on wealth channel stress, and avoids stretching dividend commitments if earnings quality softens from one off items.
Ares Management's narrative projects revenues of US$6.9b and earnings of US$2.0b by 2029. This implies revenue growth of 9.5% per year and an earnings increase of roughly US$1.5b from current earnings of about US$487.4m.
Uncover how Ares Management's fair value indicates a 32% potential upside to its current price before sentiment around Ares Management shifts and the discount compresses.
Exploring Other Perspectives
Some of the most optimistic analysts put far more weight on Ares Management’s growth in high margin platforms like Ada Infrastructure and the Aspida insurance arm. You saw forecasts as high as US$7.2b of revenue and US$2.7b of earnings by 2029. Those views were set before this Q3 update, so treat them as moving parts rather than fixed truths, and compare them with your own expectations.
Explore 2 other Ares Management fair value estimates, including one that suggests as much as 50% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Ares Management research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ares Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ares Management's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ares Management?
Once you have a view on Ares Management, it can help to widen the lens and compare it with other opportunities that share some of the same qualities or offer a very different risk and return profile.
- If you want potential mispricing combined with quality fundamentals, review our curated set of 33 high quality undervalued stocks that might merit a closer look.
- For investors who care most about balance sheet strength and durability through cycles, scan the list of solid balance sheet and fundamentals (25 results) to see which businesses fit that brief.
- Income focused readers can check which payouts may justify further research by reviewing our selection of 8 dividend fortresses that pair higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com