


United Natural Foods (UNFI), Why Is It Drawing Fresh Attention?
Recent commentary from United Natural Foods (UNFI) highlights a nearly 24% rise in candy sales, driven by demand for non-GMO, vegan, and unsweetened products that pair familiar indulgence with cleaner ingredient labels.
At a share price of US$47.79, United Natural Foods has given investors a 43.0% year to date share price return, even though the stock has eased 0.97% over the past day and slipped over the last 90 days. That shorter term cooling contrasts with a 13.62% total shareholder return over one year and a very large 3 year total shareholder return of about 3x. This suggests recent moves in categories like cleaner label candy are being weighed against earlier enthusiasm and shifting views on risk and execution.
Scan other food and consumer staples stocks showing similar clean-label momentum with our curated list of 33 high quality undervalued stocks.
United Natural Foods trades about 11% below the average analyst target and at a sizeable discount to some intrinsic estimates. Is that caution about execution and risk still warranted after the recent run up?
Most Popular Narrative: 10% Undervalued
United Natural Foods is trading below the most followed fair value estimate of $53, which anchors the current debate around how much recent execution progress and cleaner label trends really justify in terms of upside from the $47.79 share price.
The accelerating consumer demand for organic, natural, and specialty products is translating into robust growth for UNFI's core categories, as reflected by 12% sales growth in the Wholesale Natural Products business and sustained volume momentum. This long-term consumption shift supports future revenue expansion.
See why 8 investors see United Natural Foods as 10% undervalued.
That storyline uses a discount rate of 8.57% and lands on a fair value around $53, which is also in line with the current analyst consensus target. Earnings of $84.0 million today and analyst expectations for $262.0 million by about 2029 sit behind that view, alongside an assumed profit margin lift from 0.3% to 0.8% and revenue growth of about 1.9% a year.
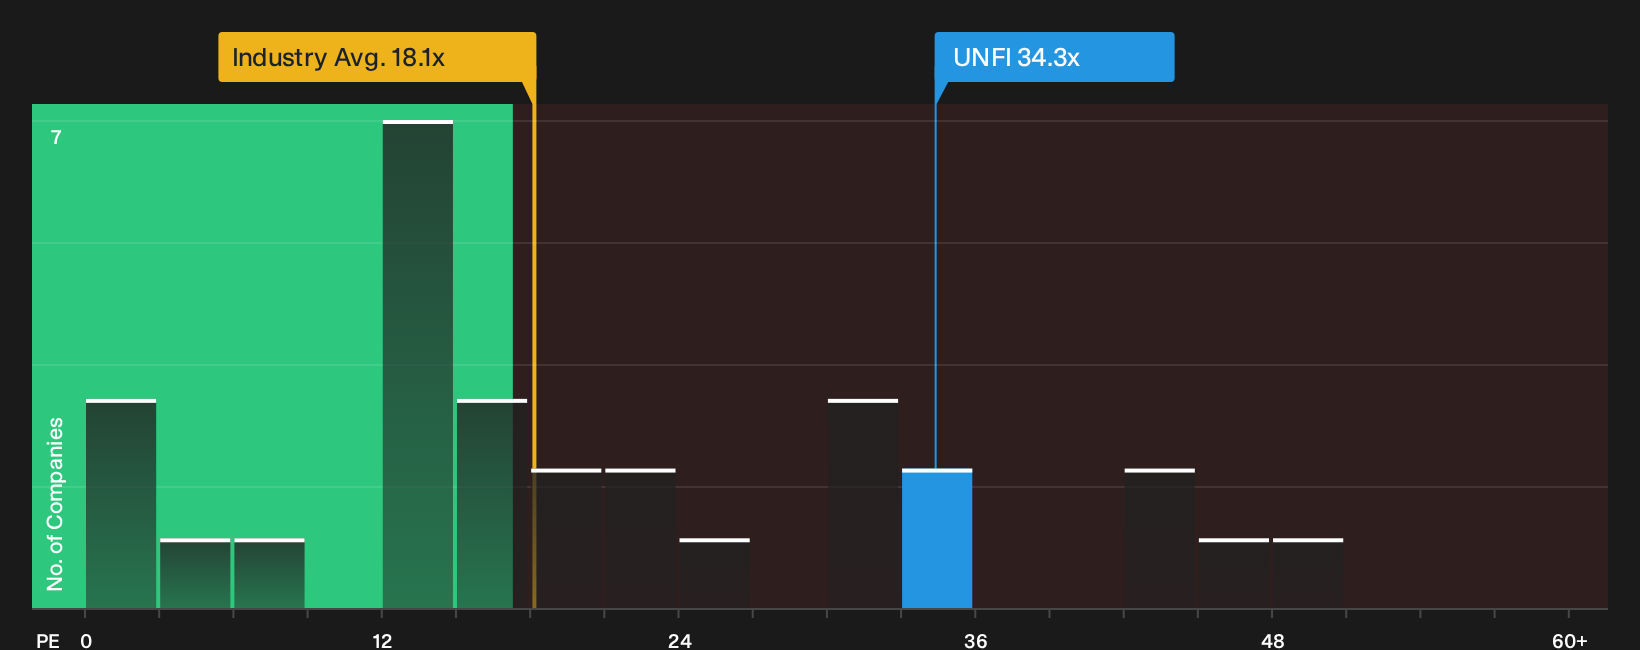
Analysts in that framework are effectively asking the market to accept a P/E of 15.1x on those later year earnings, compared with United Natural Foods trading on a much higher multiple today and above the US Consumer Retailing industry at 18.1x. The narrative implies that if earnings follow those paths, the valuation multiple could drift down toward that 15.1x level as the story becomes more about steady profit delivery than turnaround risk.
The same analysis still flags real pressure points. Conventional products are under strain, interest costs are not comfortably covered by earnings yet, and UNFI relies on higher risk funding rather than customer deposits. One off items, including a $96.0 million loss in the last twelve months to 1 August 2026, also make recent profit quality harder to read than a clean set of accounts.
Even so, the forecast profile is skewed toward profit recovery rather than top line acceleration. Revenue is modeled to grow around 2.1% a year, well behind the 13.4% forecast for the broader US market, while earnings are projected to grow about 23% a year from a relatively low base. That mix helps explain why the most popular narrative lands on a modest discount to fair value rather than a deep value case.
Result: Fair Value of $53 (UNDERVALUED)
Still, two pressure points could easily upset that 10% undervalued story for United Natural Foods: further weakness in conventional products and any fallout from cybersecurity issues.
Find out about the key risks to this United Natural Foods narrative.
Another View: What Multiples Say About United Natural Foods
The SWS DCF model points to upside for United Natural Foods, yet the current P/E of 34.3x looks heavy next to both the Consumer Retailing industry at 18.1x and a fair ratio of 27.9x. That richer multiple hints at valuation risk, not a bargain, if execution wobbles.
Investors comparing these signals may want to stress test what happens if sentiment shifts closer to that fair ratio before assuming the DCF upside is theirs to capture. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on United Natural Foods so far. If you want to move fast and develop your own interpretation of the story, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond United Natural Foods?
If you stop at United Natural Foods, you risk missing other opportunities that fit your style. Use targeted screeners to quickly surface ideas that match your priorities.
- Spot potential mispricing by scanning a curated pool of companies that screen as 33 high quality undervalued stocks before the crowd pays attention.
- Lock in income-focused ideas by reviewing a focused set of 8 dividend fortresses that pair higher yields with company specific fundamentals.
- Dial back volatility by focusing on a 32 resilient stocks with low risk scores that filters for businesses with stronger overall resilience scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com