


BlackRock (BLK) Posted Strong Q3 Earnings, Is The Stock Still A Bargain?
BlackRock (BLK) is back in the spotlight after its third quarter 2026 earnings showed higher revenue, stronger profitability metrics and record client inflows, sparking a fresh debate about what investors are paying for.
Recent moves in BlackRock’s stock suggest that momentum has picked up, with a 7.61% 90 day share price return and a 6.04% 30 day share price return after the earnings release, even though the 1 year total shareholder return is roughly flat and the 3 year total shareholder return is close to doubling investors’ money.
Compare BlackRock’s earnings surprise with other fee-heavy asset managers and AI plays by reviewing our hand picked 33 high quality undervalued stocks that benefit from similar themes.
For investors watching BlackRock after this earnings jolt, the puzzle is simple enough. Is this the moment to accept today’s price, or does patience for a cooler entry make more sense once the valuation work is done?
Most Popular Narrative: 14% Undervalued
According to the most followed narrative on BlackRock, the shares look cheap relative to a fair value of $1,318.96, compared with the latest close at $1,134.38. This puts the current debate on price squarely on execution in higher margin areas such as technology and private markets.
"This shift in business mix fully supports the multiple expansion assumption embedded in the original valuation model.
BlackRock has evolved from 'an indexed asset manager' into a global platform spanning technology, public markets, and private markets, with a more recurring earnings profile and increasing relevance as financial infrastructure."
See why 34 investors see BlackRock as 14% undervalued.
Result: Fair Value of $1,318.96 (UNDERVALUED)
Still, BlackRock’s story can be knocked off course if acquisition integrations disappoint or if market driven fee pressure undercuts the high margin platform pitch.
Find out about the key risks to this BlackRock narrative.
Another View: What BlackRock’s P/E Is Really Saying
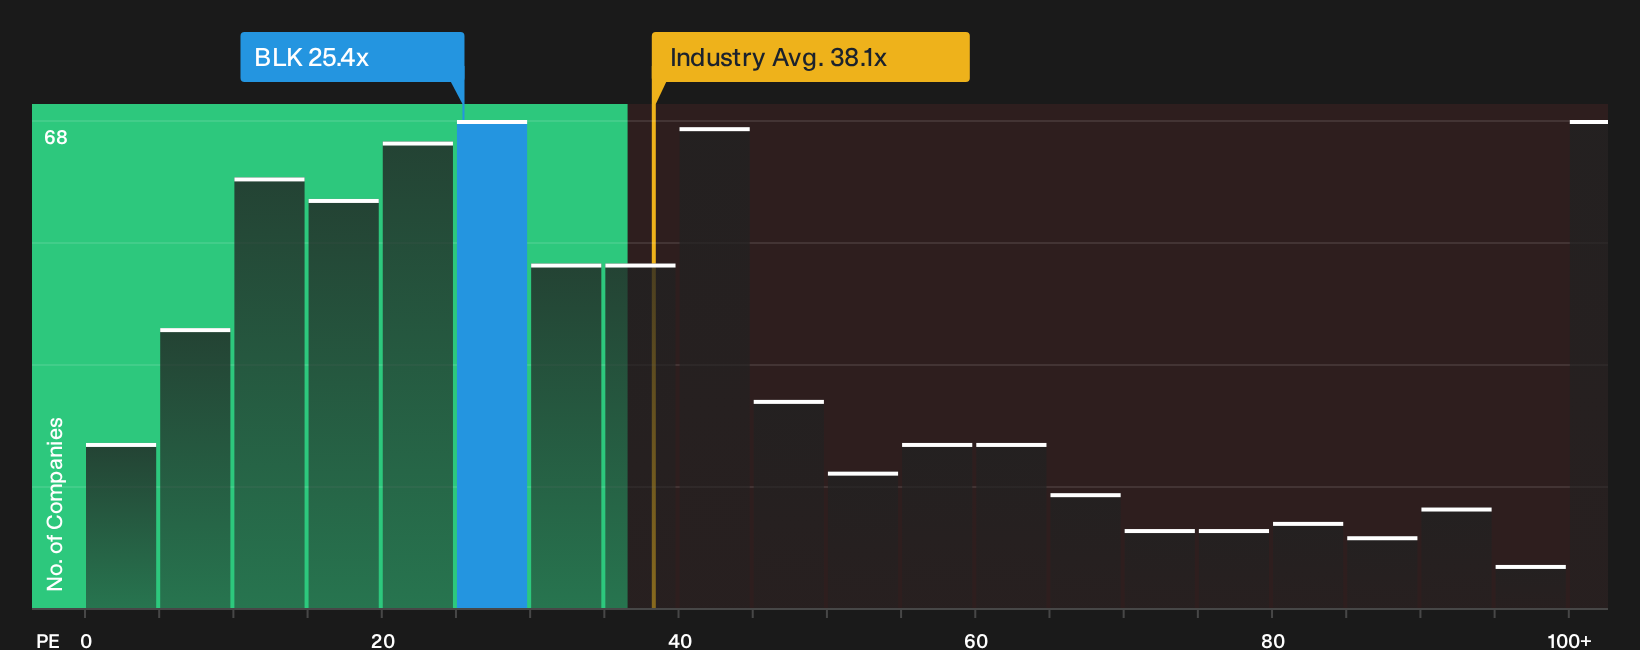
Momentum investors see BlackRock as undervalued based on that $1,318.96 fair value, yet the current P/E of 25.4x tells a tougher story. The stock trades richer than a fair ratio of 18.2x and above peer averages of 19.6x, even though the broader US Capital Markets group sits on a much higher 38.1x.
For you, that gap means paying up today for a business that screens cheap on cash flows but pricey on earnings. The key question is simple. Does the quality of BlackRock’s platform justify paying well above that fair ratio the market could drift toward, or is this where discipline wins?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment clearly split between reward potential and real risk flags, move quickly to stress test the numbers yourself and pressure check the story. The quickest way to see both sides is to review the 3 key rewards and 1 important warning sign.
Looking for more BlackRock style ideas?
If BlackRock has sharpened your focus on quality and valuation, do not stop here. Fresh opportunities rarely wait around for hesitant investors.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive valuations through the 33 high quality undervalued stocks.
- Boost your income potential by lining up stocks that pay out robust yields in the 8 dividend fortresses.
- Dial down portfolio risk by filtering for financially resilient businesses in the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com