


Vicor (VICR) Slides As AI Narrative Still Points To Higher Fair Value
Vicor (VICR) has drawn attention after a sharp pullback, with the share price down 13% in a day and about 28% over the past week. That move reframes how investors may view its recent gains.
The sharp weekly drop comes after a long stretch of strong gains, with the year-to-date share price return at about 63.9% and the 1-year total shareholder return above 200%. This recent volatility hints that momentum has cooled, even as longer term holders still sit on very large gains.
Scan opportunities moving with or against Vicor by reviewing our hand picked list of 55 AI infrastructure stocks before the next leg of sentiment sets in.
After a run that left Vicor holders with very large gains, this 1 week slide forces a reset. Is most of the payoff already in the rear view mirror, or does the current valuation still leave real upside on the table?
Most Popular Narrative: 51% Undervalued
Vicor last closed at $191.50, while the most followed narrative sets fair value at $393.75 using a 9.38% discount rate. That wide gap rests on a view that Vicor can convert its AI focused backlog and licensing deals into a much larger, high margin operation over time.
The accelerated adoption of high power, high density AI computing in data centers is still a live driver, and Vicor’s second generation vertical power delivery reaching 3 amps per mm² for a lead customer with a target of over 5 amps per mm² by late 2026 or early 2027 supports the view that higher performance products can support future revenue and gross margin.
See why 30 investors see Vicor as 51% undervalued.
Result: Fair Value of $393.75 (UNDERVALUED)
Still, the Vicor story is fragile if insider selling continues at scale or if rising legal and tax related costs start to squeeze earnings power.
Find out about the key risks to this Vicor narrative.
Another View: Vicor Looks Expensive On Earnings
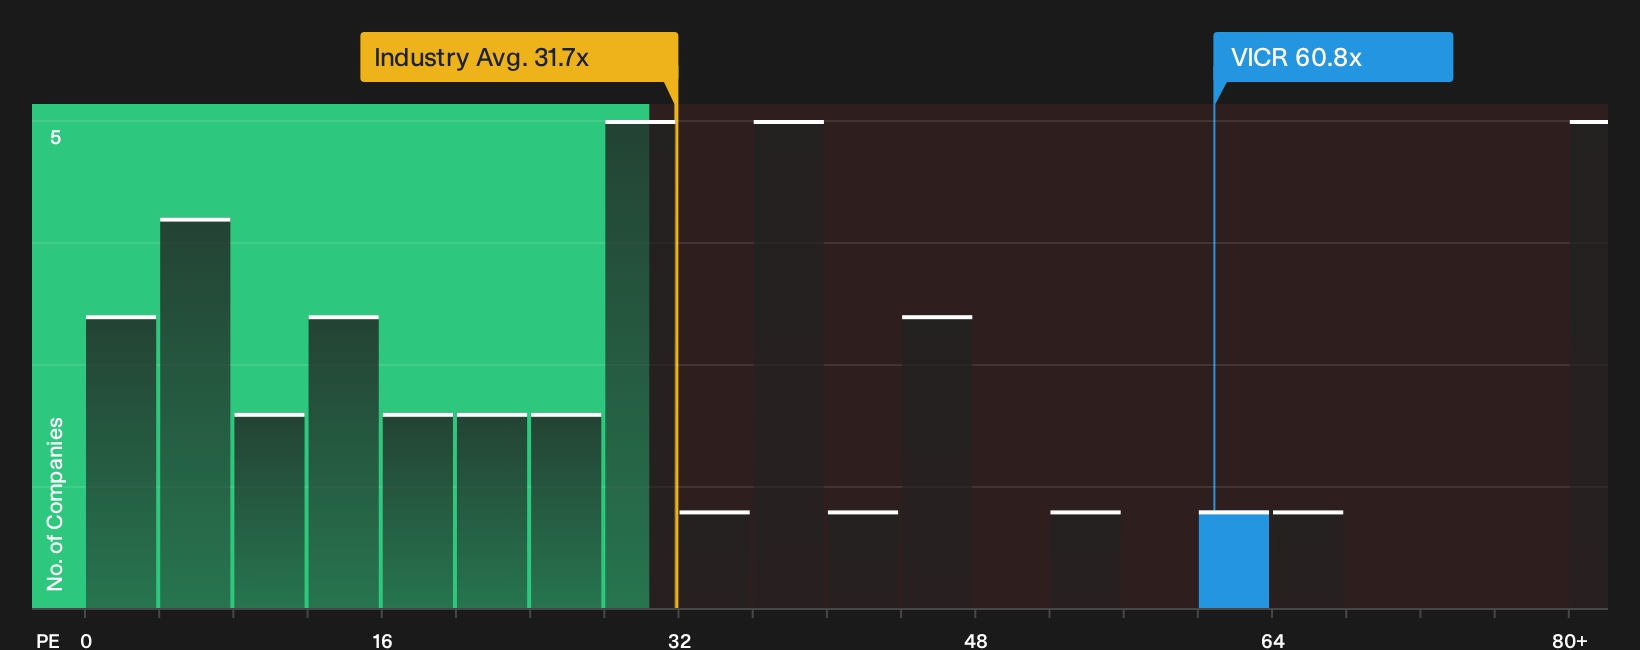
The first narrative leans on long range forecasts and a fair value of $393.75. A simpler lens tells a very different story. On a P/E of 60.8x, Vicor trades at more than double its peer average of 27.5x and well above the US Electrical group on 31.7x.
The fair ratio for Vicor is 65.2x, so today’s multiple sits closer to that modelled level than to sector norms. This tightens the margin for error if growth or margins disappoint. Is this a premium you are comfortable paying for the AI and licensing thesis to play out, or is it time to compare alternatives before committing fresh capital?
For a closer look at how that earnings multiple stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around Vicor can either freeze you or push you to check the numbers yourself and move with intent. To weigh both the upside potential and the downside signals, start with our breakdown of 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond Vicor?
If Vicor has you thinking harder about where to deploy fresh capital next, do not stop at a single ticker. Use targeted stock lists to pressure test your next move and avoid leaving better risk reward trades on the table.
- Target potential upside with companies that combine quality fundamentals and attractive pricing by scanning our 33 high quality undervalued stocks.
- Reinforce portfolio stability by focusing on balance sheets that look built to endure with the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by tracking 20 high quality undiscovered gems before they get heavy attention and pricing catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com