


AutoStore Holdings (OB:AUTO) Has A Record Backlog, Is It Still 15% Undervalued?
Fresh commentary around AutoStore Holdings (OB:AUTO) is focusing on its record order backlog and management’s 2026 revenue guidance near US$700 million, along with projected free cash flow growth that supports a more optimistic narrative.
AutoStore Holdings’ latest commentary lands after a sharp 35.8% 90 day share price return and a 62.3% 1 year total shareholder return, which points to momentum building as investors reassess growth potential and risk around the guided revenue and free cash flow story.
Compare AutoStore Holdings’ surge in interest with other robotics and automation plays by scanning the hand-picked 91 robotics and automation stocks, which are also riding order backlogs and free cash flow stories.
Bulls see AutoStore Holdings’ backlog and 2026 targets as proof the rerating has room to run. Bears see a hot story already priced in. Which side do the cash flow and valuation numbers lean toward now?
Most Popular Narrative: 15% Undervalued
AutoStore Holdings last closed at NOK15.26, while the most followed narrative anchors fair value around NOK17.94. This frames the recent rally as still short of that central estimate.
The accelerated rollout of new products and features, with 11 launches in 2025 and 14 more in the 12 months to Q2 2026 including AutoCase, FlexBins, CubeVerse and AutoStore Intelligence, expands addressable warehouse workflows and end markets, which can support revenue growth and help sustain high gross and EBITDA margins.
See why 13 investors see AutoStore Holdings as 15% undervalued.
Result: Fair Value of NOK17.94 (UNDERVALUED)
Still, soft North American revenue in Q2 2026 and management’s plans for heavier product and AI spending could pressure AutoStore Holdings if project conversion lags.
Find out about the key risks to this AutoStore Holdings narrative.
Another View: What Multiples Say About AutoStore Holdings
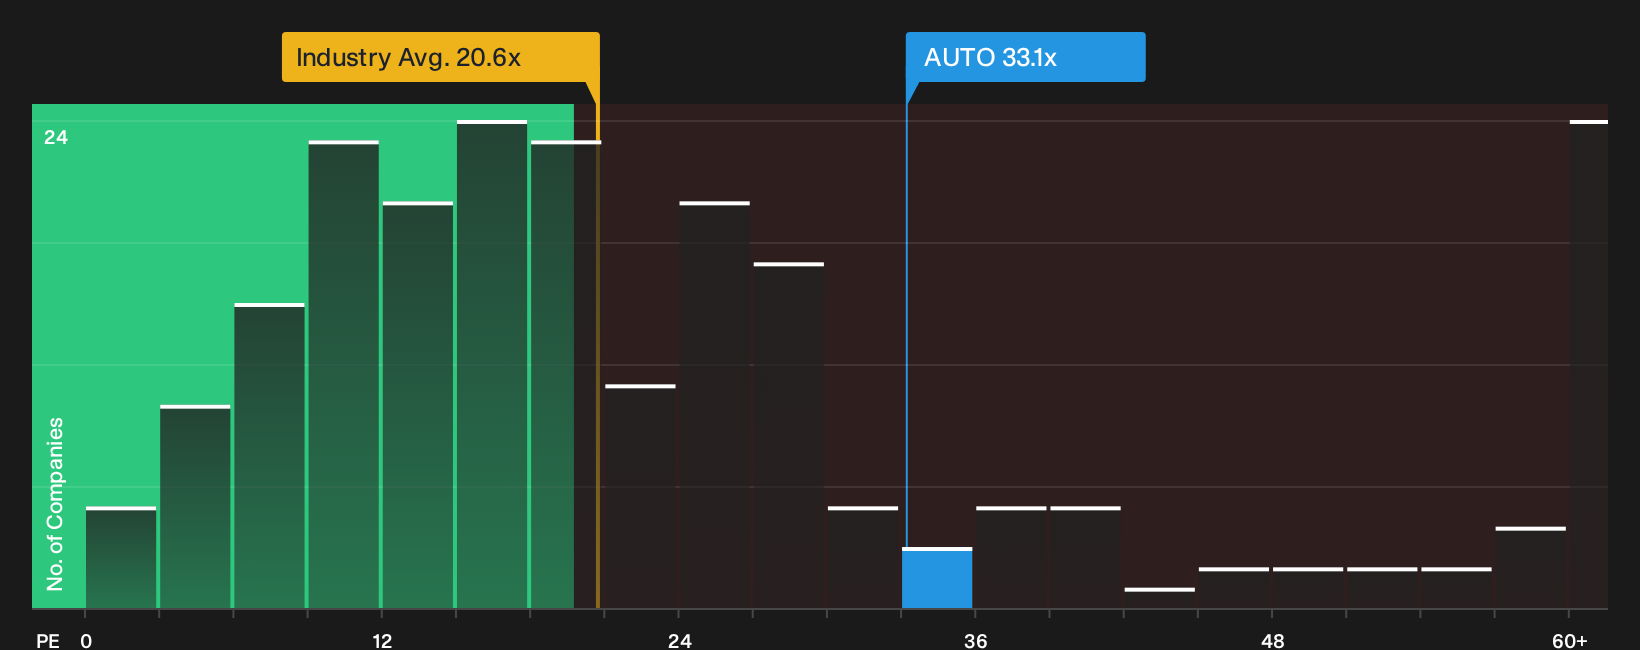
The story changes once the focus shifts from cash flows to what investors are paying for each krone of AutoStore Holdings’ earnings. The current P/E of 33.1x sits above the European Machinery group on 20.2x and is also higher than the fair ratio of 30.2x, which signals that sentiment already builds in a richer outcome than the regression-based reference point suggests. If earnings growth or margins come in softer than expected, how much room is there for the multiple to adjust without eating into that 15% upside narrative?
For a closer look at how the current earnings multiple compares with peers and the fair ratio, and what that might imply for valuation risk in practice, see See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around AutoStore Holdings is split, with both risk concerns and reward potential on the table, so move quickly and pressure test the data yourself using our breakdown of 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond AutoStore Holdings?
If AutoStore Holdings is on your radar, broaden your watchlist with a few targeted screens that surface fresh ideas before the wider market catches on.
- Target resilience first by scanning a 234 resilient stocks with low risk scores that keeps volatility and risk scores in check while you focus on compounding capital.
- Hunt for quality at a discount with a 191 high quality undervalued stocks that blends solid fundamentals with pricing that still leaves room for upside.
- Build staying power into your portfolio using a list of solid balance sheet and fundamentals (204 results) that prioritises durable finances and dependable fundamentals over short term excitement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com