


Why China Overseas Land & Investment (SEHK:688) Is Back In The Spotlight
China Overseas Land & Investment (SEHK:688) has released its September 2026 sales data, reporting a 22.8% year-on-year decline in contracted value. However, the total for January to September increased by 6.2%, even though the sales area was smaller.
Recent price action has been mixed. The share price is up 10.1% over the past 30 days but roughly flat over 90 days, while the year to date share price return of 5.4% contrasts with a 1 year total shareholder return that is slightly negative. This suggests enthusiasm around China Overseas Land & Investment's latest sales update is still tentative, and investor focus remains split between near term sales volatility and the longer multi year record.
Scan other property developers showing a different mix of sales momentum and share price performance by reviewing our hand picked list of 191 high quality undervalued stocks alongside China Overseas Land & Investment.
Bulls point to China Overseas Land & Investment’s higher year to date sales value and recent share price rebound. Bears focus on the September slump and weak 1 year return. Which story does current valuation better reflect?
Preferred P/E of 11x: Is it justified for China Overseas Land & Investment?
On traditional valuation metrics, China Overseas Land & Investment screens as inexpensive against several benchmarks. The stock closed at HK$13.17, which aligns with a P/E of roughly 11x and a headline assessment that it trades at a 57.9% discount to an estimated fair value of HK$31.29 based on future cash flows.
The P/E multiple measures how much investors are willing to pay today for each unit of current earnings. For a developer with multiple revenue streams and HK$11,122.53m in net income, this ratio helps you judge how the market is weighing current profitability against future expectations. In this case, the share price embeds a P/E that is below several reference points provided in the data.
Several comparisons pull in different directions. Relative to the Hong Kong Real Estate peer average P/E of 15.3x, China Overseas Land & Investment is described as good value, and its P/E also screens attractively against an estimated fair P/E of 14.6x that the market could move toward if sentiment shifts. At the same time, the stock is labelled expensive against the broader Hong Kong Real Estate industry average of 8.9x, which hints that investors might be assigning a premium versus some sector peers, even though earnings have declined by 26.8% per year over the past 5 years and recent net profit margins compressed from 7.7% to 6.1%.
Explore the SWS fair ratio for China Overseas Land & Investment.
Result: Price-to-earnings of 11x (UNDERVALUED).
Still, the recent September sales drop and the multi year earnings decline rate of 26.8% per year could quickly challenge any optimism around China Overseas Land & Investment’s valuation reset.
Find out about the key risks to this China Overseas Land & Investment narrative.
Another View: What The SWS DCF Model Says About China Overseas Land & Investment
The P/E points to value, yet the SWS DCF model goes even further. On that framework, China Overseas Land & Investment at HK$13.17 is described as trading at a 57.9% discount to an estimated fair value of HK$31.29. This suggests an even larger valuation gap.
DCF estimates rely on long term cash flow assumptions, while earnings multiples lean on current profit and peer comparisons. If the cash flow inputs prove too optimistic, that 57.9% discount could shrink quickly. If they are accurate, the current P/E may be an unduly cautious indicator for China Overseas Land & Investment.
Look into how the SWS DCF model arrives at its fair value.
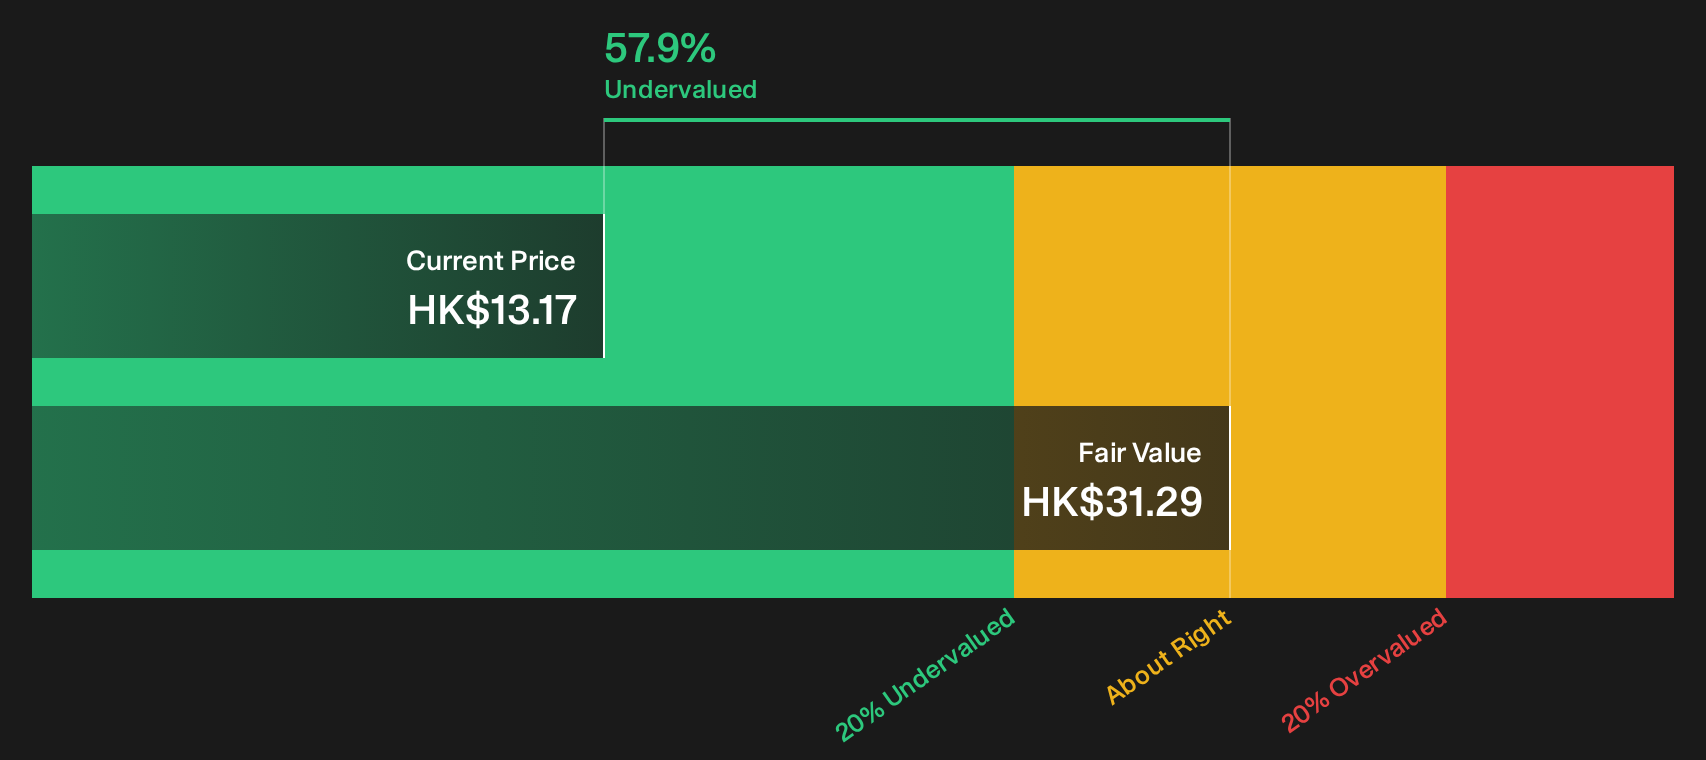
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Overseas Land & Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China Overseas Land & Investment’s valuation and fundamentals can pull you in both directions, so check the numbers yourself, weigh the trade offs between risks and potential upsides, and then review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond China Overseas Land & Investment?
If China Overseas Land & Investment has sharpened your focus on valuation and risk, you may want to broaden your opportunity set with a few targeted stock ideas.
- Chase potential mispricing by scanning a curated group of companies that screen as both financially strong and attractively valued through the 191 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by zeroing in on businesses with robust finances using the list of solid balance sheet and fundamentals (204 results).
- Review a focused pool of under the radar opportunities with sound fundamentals in the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com