


Skandinaviska Enskilda Banken (OM:SEB A), Why Is It Drawing Fresh Attention?
Skandinaviska Enskilda Banken (OM:SEB A) is back under the spotlight after resolving a long running U.S. regulatory review tied to historical anti money laundering controls in its Baltic operations, with a settlement that clarifies legacy legal risks.
Recent attention on Skandinaviska Enskilda Banken comes alongside a 10.79% year to date share price return to SEK219.3. Momentum has softened over the past month as the 30 day share price return declined 3.73% and the 7 day move fell 3.82%. Even so, the 1 year total shareholder return of 29.88% and 5 year total shareholder return of 127.10% point to a longer track record that investors are weighing against the regulatory clean up and October leadership change.
Compare how Skandinaviska Enskilda Banken stacks up on legal, earnings and balance sheet resilience by scanning our curated list of 234 resilient stocks with low risk scores.
Skandinaviska Enskilda Banken now pairs a clearer legal backdrop with a long running total return record and a softer recent share pullback. The real test is how that mix compares with the current valuation.
Most Popular Narrative: 3.5% Undervalued
Skandinaviska Enskilda Banken is trading at SEK219.3 against a widely followed fair value estimate of SEK227.18, so the current setup is framed as modest undervaluation built on measured assumptions for growth, margins and risk.
SEB's focus on increasing fees and commissions in the CIB division and customer satisfaction improvements could boost revenue growth. The expansion of AI initiatives across the bank is expected to enhance efficiency and productivity, positively impacting net margins over the medium to long term.
See why 23 investors see Skandinaviska Enskilda Banken as 3% undervalued.
The narrative rests on a discount rate of 6.28%, with revenue growth assumptions around 5.3% a year and profit margins near 42.2%, which together support the SEK227.18 fair value mark relative to today's price. That combination points to a mildly supportive valuation gap rather than a deep discount or stretched premium based on these inputs.
Result: Fair Value of SEK227.18 (UNDERVALUED)
Still, if fee heavy Corporate & Investment Banking activity slows or regulatory levies rise faster than expected, Skandinaviska Enskilda Banken's fair value narrative could quickly look fragile.
Find out about the key risks to this Skandinaviska Enskilda Banken narrative.
Another View: Skandinaviska Enskilda Banken On Earnings Multiples
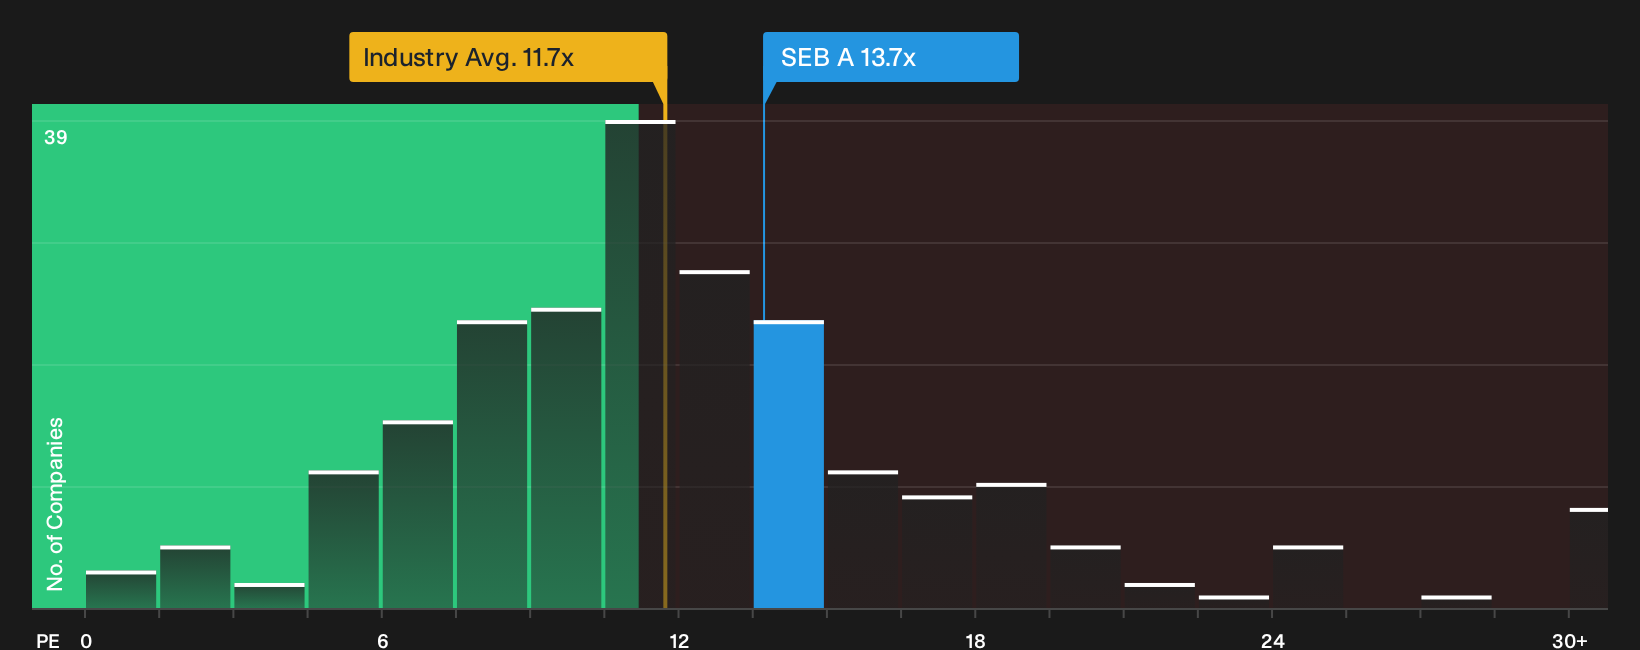
Fair value models lean toward Skandinaviska Enskilda Banken looking undervalued, yet its P/E of 13.7x sits above the European banks group at 11.7x and the peer average at 12.1x, and even above a fair ratio of 13.3x. That premium suggests less room for error if earnings disappoint. Which signal do you trust more: the cash flow model or what the market is paying per krona of profit?
See what the numbers say about this price gap in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
You can then set that into context using the relative P/E snapshot in
Next Steps
Mixed signals around Skandinaviska Enskilda Banken's valuation and risk profile mean opinion is split, so consider acting promptly, review the underlying data and weigh both 2 key rewards and 1 important warning sign.
Looking for more Skandinaviska Enskilda Banken sized ideas?
If you stop with Skandinaviska Enskilda Banken, you miss a broader set of opportunities that could fit your risk tolerance and income goals even better.
- Target stronger balance sheets by checking companies screened for financial resilience in the list of solid balance sheet and fundamentals (204 results).
- Hunt for mispriced opportunities by scanning companies that appear attractively valued in the 191 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies focused on higher yields in the 216 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com