


Man Wah Holdings (SEHK:1999) Could Be 58% Undervalued After Its Profit Warning
Guidance shock puts Man Wah Holdings under the microscope
Man Wah Holdings (SEHK:1999) has warned that profit attributable to shareholders for the six months to 30 September 2026 could fall roughly 70% to 90% from the HK$1,145.6 million reported a year earlier.
The guidance flags pressure from higher chemical input costs linked to the Middle East conflict, weaker gross margin, and sizeable losses tied to a recently acquired US business, including impairment charges following Southern Motion Inc.'s Chapter 11 filing.
Investors have reacted quickly to Man Wah Holdings' profit warning, with the share price down 28.46% over the past 90 days and 50.97% year to date. The 1-year total shareholder return of 46.38% and 5-year total shareholder return of 76.78% highlight longer running pressure on sentiment, despite a 4.12% rebound in the latest session that hints at short term bargain hunting rather than a clear shift in momentum.
Contrast Man Wah Holdings' current earnings pressure with other hand picked furniture and consumer durables stocks by scanning 191 high quality undervalued stocks, which may offer stronger fundamentals at compressed prices.
After a profit warning this sharp and a share price slide this deep, the question for Man Wah Holdings now is whether the current valuation still compensates you for the risks.
Preferred P/E of 4.8x: Is it justified for Man Wah Holdings?
On simple valuation markers, Man Wah Holdings looks cheap. The shares last closed at HK$2.28, while the stock trades on a P/E of 4.8x that screens as low against both its own fair ratio and sector references.
The P/E ratio compares what you pay per share with the earnings that Man Wah Holdings generates per share. For a consumer durables group that manufactures sofas and related home products, this measure helps you judge whether the market is putting a heavy or light price tag on those profits, especially when earnings forecasts point to moderate growth rather than rapid expansion.
Analysts currently expect earnings for Man Wah Holdings to grow about 4.8% per year, slower than the Hong Kong market forecast of 10.5% per year. Despite that softer outlook, the shares are priced at a P/E of 4.8x compared with the Hong Kong Consumer Durables industry average of 9.5x and a peer average of 19.6x. The estimated fair P/E for the stock is 6.9x, which is meaningfully higher than where the shares trade and suggests the market could shift closer to that level if sentiment toward the business improves.
Explore the SWS fair ratio for Man Wah Holdings.
Result: Price-to-earnings of 4.8x (UNDERVALUED)
Still, Man Wah Holdings faces clear threats from further losses in its US operations, as well as any renewed squeeze on input costs that could chip away at already thin sentiment.
Find out about the key risks to this Man Wah Holdings narrative.
Another view on Man Wah Holdings: DCF flags deeper mispricing
The low P/E tells only part of the story. Our DCF model values Man Wah Holdings at HK$5.47 per share, compared with the recent HK$2.28 price. This implies the stock trades at roughly a 58.4% discount to that estimate. That kind of gap can signal either opportunity or a model that is far too optimistic, so which is it?
Look into how the SWS DCF model arrives at its fair value.
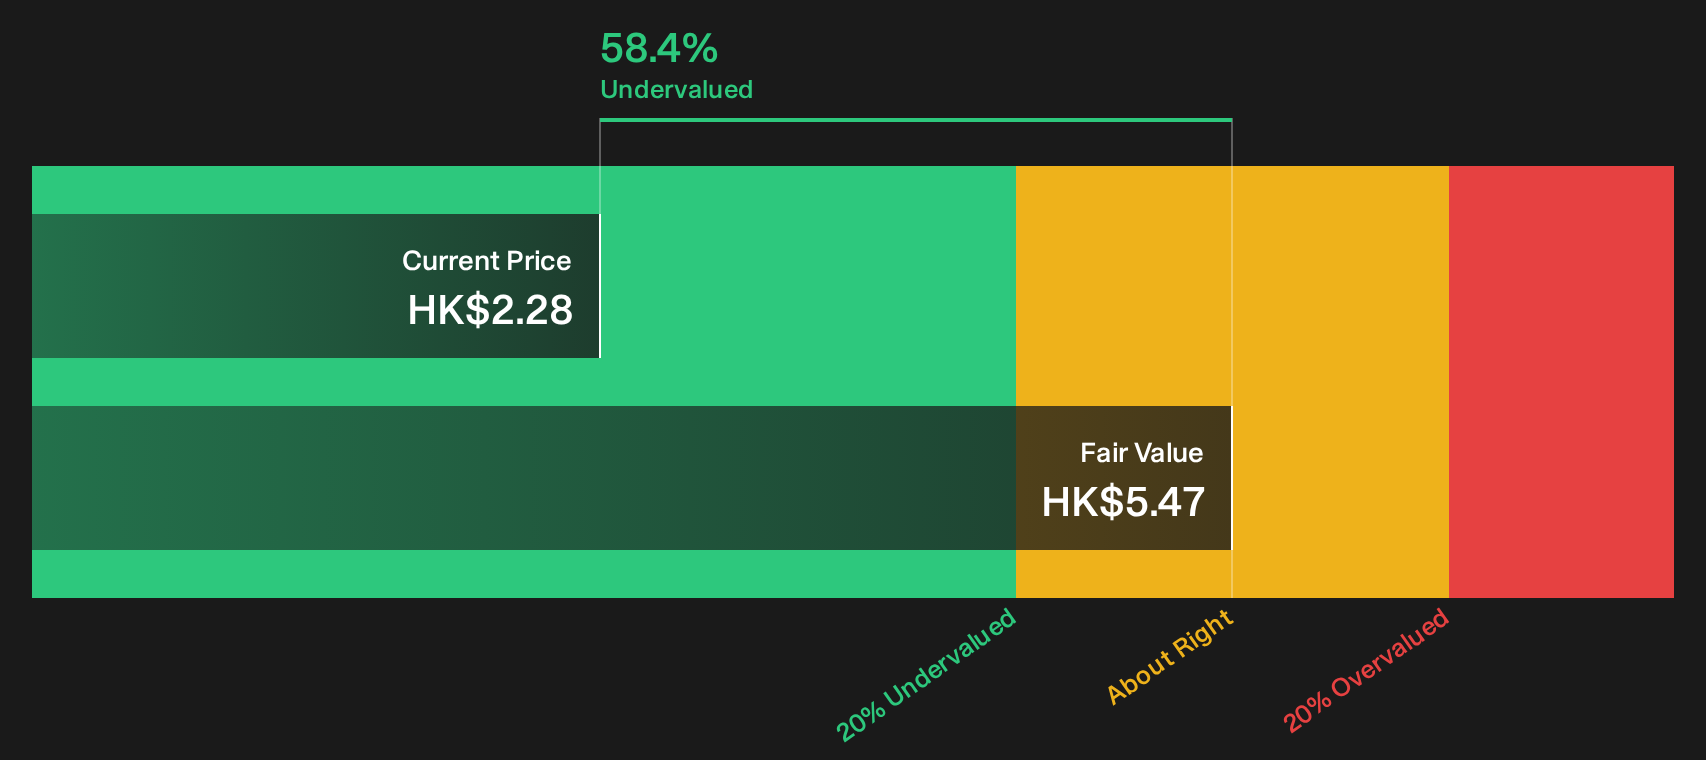
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Man Wah Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Man Wah Holdings is clearly split, with sharp guidance risk on one side and value signals on the other. If you are considering this stock, it may be useful to move quickly and review the underlying data yourself. To weigh both angles in one place, start with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Man Wah Holdings?
If Man Wah Holdings has sharpened your focus on valuation and risk, you may wish to use that momentum and line up your next watchlist candidates before the market moves.
- Scan the 191 high quality undervalued stocks to identify potential value ideas that combine lower pricing with stronger financial profiles.
- Review the 234 resilient stocks with low risk scores to focus on ideas that aim to keep volatility in check while still leaving room for possible upside.
- Explore the 614 high quality undiscovered gems to find companies that pair quality fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com