


Earnings Beat Could Be A Game Changer For PNC Stock
- PNC Financial Services Group reported Q3 2026 net interest income of US$4.206b and net income of US$2.081b, with basic EPS from continuing operations at US$4.98, alongside higher net loan charge offs of US$257m compared with the prior year period.
- The bank is pairing heavier investment in AI and automation with mixed fee income trends and rising credit costs, which increases the focus on how efficiently PNC converts its technology spending into operating leverage and more resilient noninterest revenue.
- This article will examine how PNC Financial Services Group's stronger Q3 earnings and higher loan charge offs may influence the broader investment narrative.
Compare how PNC Financial Services Group’s Q3 mix of stronger earnings, rising charge offs and heavier tech spend stacks up against peers in our hand picked 32 resilient stocks with low risk scores.
PNC Financial Services Group Investment Narrative Recap
To own PNC Financial Services Group, you need to be comfortable with a story that leans on technology spending, a large US$300b loan book and fee based lines to keep earnings resilient. The Q3 report reinforces that earnings power is intact in the near term, even as fee income showed some softness and costs tied to AI programs remain elevated.
The most important short term swing factor is how quickly PNC turns its heavy automation and AI investment into visible operating leverage. The main risk right now is credit. Net loan charge offs of US$257m in Q3, higher than a year ago, keep the focus squarely on how credit quality holds from here.
The Q3 earnings release is the clearest reference point for that risk reward trade off. Net interest income of US$4.206b and net income of US$2.081b, together with basic EPS from continuing operations at US$4.98, show that PNC Financial Services Group can still generate sizeable profit while absorbing higher credit losses.
That same update also frames near term catalysts. Rising net charge offs and mixed fee income trends put more pressure on the AI and automation program to deliver cost efficiencies. At the same time, the planned redemption of US$1.25b of 6.615% senior notes in October 2026 will slightly reshape funding costs and capital flexibility around those execution priorities.
PNC Financial Services Group’s current analyst narrative points to revenues of US$29.1b and earnings of US$8.7b by 2029, built on forecast revenue growth of 6.2% a year. This would mean an earnings increase of about US$1.4b from the US$7.3b reported today.
Uncover why PNC Financial Services Group's fair value indicates a 25% potential upside to its current price, which could narrow quickly.
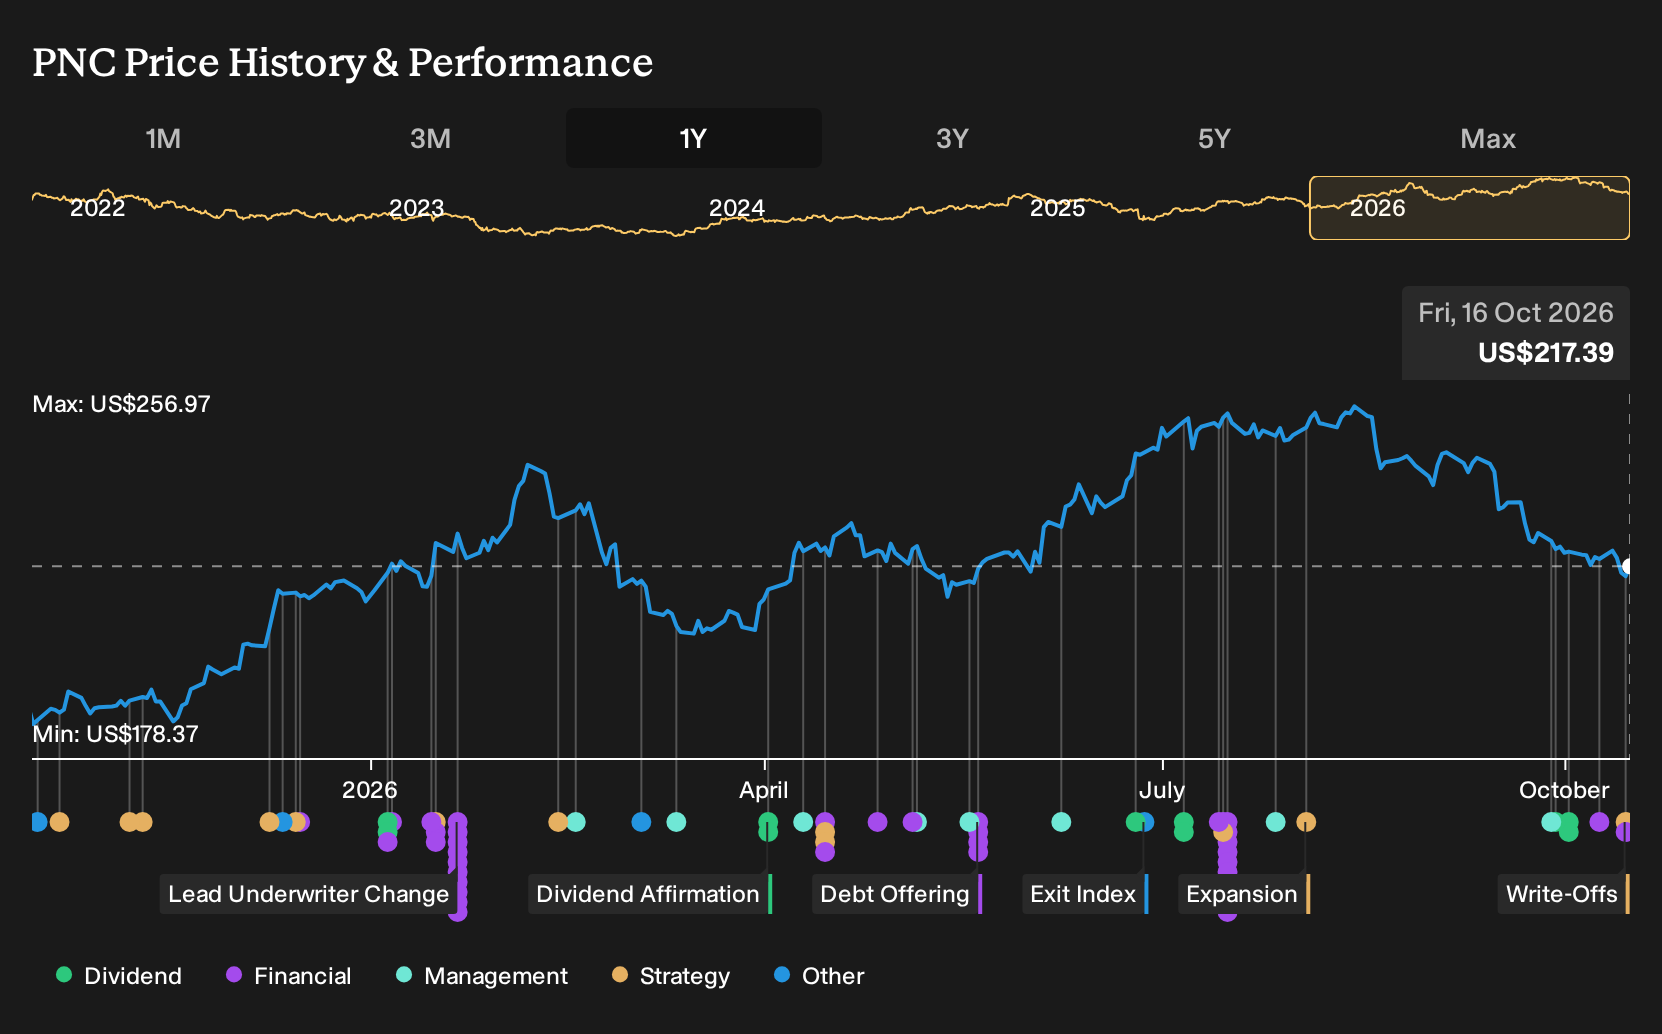
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$272 to almost US$392 a share, which is a wide gap for the same PNC Financial Services Group story. That spread sits beside rising charge offs, heavy AI investment and upcoming debt redemption, so you are seeing sharply different views on how these forces shape future performance.
Explore another PNC Financial Services Group fair value estimate, including one that suggests the potential for as much as 80% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your PNC Financial Services Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PNC Financial Services Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PNC Financial Services Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond PNC Financial Services Group?
If the PNC Financial Services Group story has sharpened your view on risk, reward and balance sheet strength, it can be useful to scan a wider field of potential opportunities using focused stock lists built around those same themes.
- For investors who want potential upside without ignoring quality, take a look at companies flagged as having attractive valuations and stronger fundamentals through 33 high quality undervalued stocks.
- If capital preservation and sturdier financial positions matter most to you, start with the list of solid balance sheet and fundamentals (25 results) to narrow in on businesses where leverage and liquidity profiles may be less stretched.
- For readers who prefer to be early to a story rather than late, the 20 high quality undiscovered gems can surface smaller companies with stronger financial characteristics that might not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com