


Swire Pacific (SEHK:19) Pushes Mainland Expansion Following A Fair Value View
Swire Pacific (SEHK:19) is back in focus after management pushed ahead with an aggressive Mainland China development pipeline. The strategy aims to deepen its premium property footprint while the company faces softer demand in both Mainland China and Hong Kong.
That aggressive build out is landing at a time when Swire Pacific’s share price has strong momentum, with a 90 day share price return of 20.6% and a year to date gain of 65.5%. The 5 year total shareholder return of 209.3% points to a powerful longer term compounding story.
Scan other property focused opportunities that show similar momentum and expansion plans using our curated list of 191 high quality undervalued stocks.
Swire Pacific now trades only slightly below both analyst targets and an estimated fair value range, even after its strong run. Is that cautious pricing or a fair response to execution risk on the Mainland build out?
Most Popular Narrative: Fairly Valued
Swire Pacific closed at HK$105.4 against a widely followed fair value estimate of HK$105.46, which leaves almost no valuation gap and puts the focus squarely on whether the current expansion plans and earnings profile can actually deliver against expectations baked into the price.
Swire Pacific's aggressive expansion of its premium property brands (Taikoo Li, Taikoo Hui) and substantial ongoing development pipeline in Mainland China, where demand is underpinned by rising urbanization and population growth, positions the Property division for strong recurring rental and trading income growth over the coming years, supporting both revenue and earnings stability.
See why 4 investors see Swire Pacific as 0% undervalued.
Result: Fair Value of HK$105.46 (ABOUT RIGHT)
Still, the fair value story for Swire Pacific can unravel if Hong Kong offices remain weak or if aviation earnings from Cathay and HAECO turn volatile again.
Find out about the key risks to this Swire Pacific narrative.
Another View: What Swire Pacific’s P/E Is Telling You
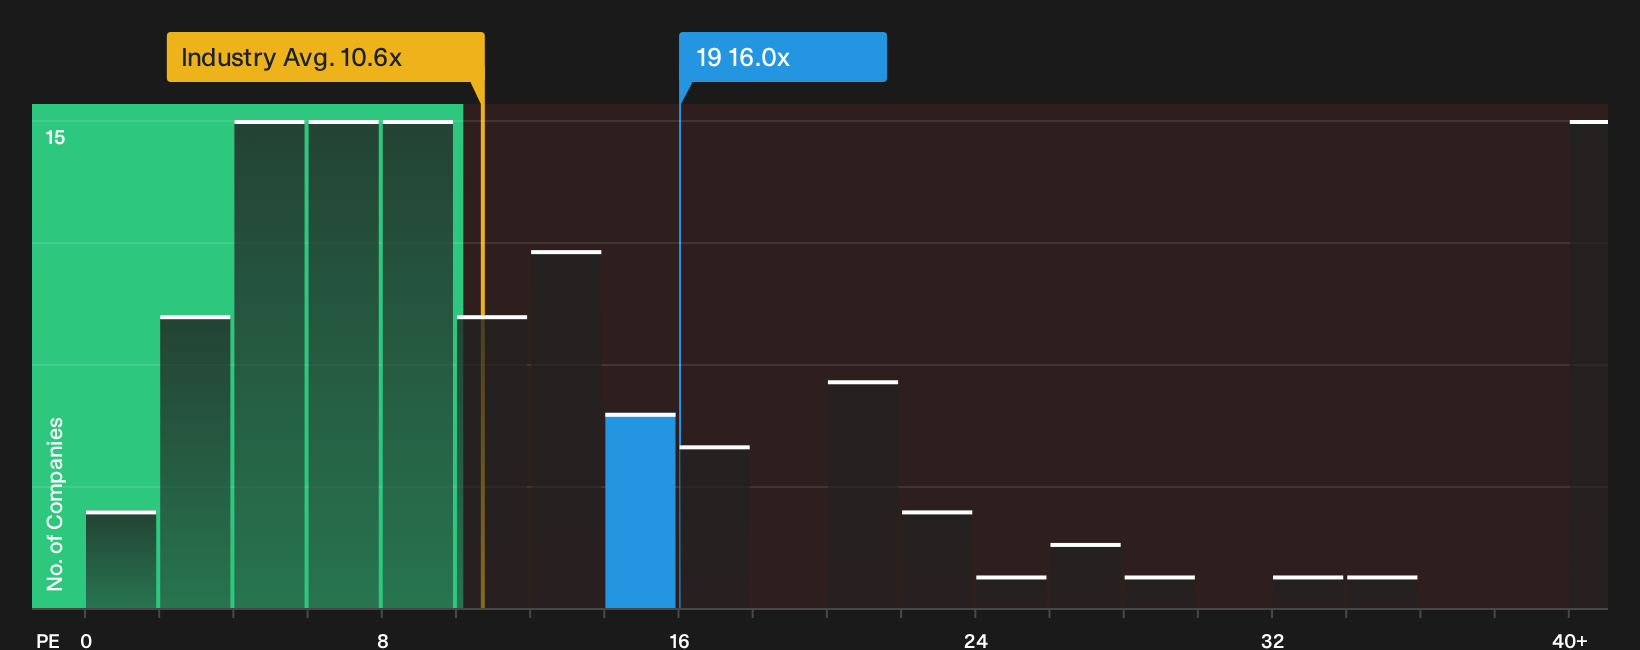
On earnings multiples, Swire Pacific looks less relaxed. The shares trade on a P/E of 16x, compared with 10.6x for the wider Asian Industrials group and 8.9x across closer peers, while the fair ratio sits lower again at 9.4x. That higher tag points to valuation risk rather than a clear bargain. How comfortable are you paying up for execution on Mainland projects and aviation exposure?
See what the numbers say about this price in our valuation breakdown, starting with the company’s current earnings multiple versus its peers and fair ratio estimate, then set your own hurdle rate for comfort around that gap. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on Swire Pacific's current pricing and risk profile. If you prefer to act quickly, review both potential benefits and drawbacks in our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Swire Pacific?
Do not park all your attention on Swire Pacific alone. Use the Simply Wall Street screener to uncover fresh ideas that might fit your portfolio better.
- Target potential mispricing by scanning a focused group of 191 high quality undervalued stocks that pair stronger fundamentals with more modest expectations.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (204 results) so weaker finances do not surprise you at the wrong moment.
- Hunt for future leaders early by reviewing a curated set of 614 high quality undiscovered gems before they sit on every investor’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com