


Lerøy Seafood Group (OB:LSG) After Weaker Q3 Volumes Is The Undervalued Case Still Intact
Production update puts Lerøy Seafood Group stock in focus
Lerøy Seafood Group (OB:LSG) drew attention after reporting third quarter 2026 production figures, with harvested salmon and trout volumes at 54,680 GWT, compared with 59,100 GWT a year earlier.
The third quarter production update landed against a backdrop where Lerøy Seafood Group’s share price has edged higher in recent months but remains under pressure this year, with the NOK41.9 quote sitting alongside an improving 3-year total shareholder return of 14.24% and a 5-year total shareholder return that is still down 32.21%.
In the short term, the 90-day share price return of 2.9% suggests recent news, including the weaker harvested volumes, has been absorbed without a sharp shift in sentiment. By contrast, the year-to-date share price decline of 18.56% and the 1-year total shareholder return decline of 13.33% point to investors reassessing both risk and recovery potential over a longer horizon.
Compare Lerøy Seafood Group’s latest move with other seafood and protein producers by scanning the hand picked list of solid balance sheet and fundamentals (204 results) list that have weathered recent market pressure more steadily.
Lerøy Seafood Group now trades at a discount to both analyst targets and intrinsic value estimates, despite the recent uptick. So where does a fair price really land between those two anchors?
Most Popular Narrative: 15% Undervalued
On the latest numbers, Lerøy Seafood Group is trading at NOK41.9 against a widely followed fair value marker of NOK49.5. This puts the recent production update into a valuation frame rather than just a volume story.
Lerøy's sustained investment in new farming technologies (such as submerged and shielding technology) and its in-house improvement program have already yielded higher survival rates, lower mortality, and cost reductions. This positions the company for continued increases in production volumes with better efficiency, which should positively impact both revenue growth and net margins.
See why 21 investors see Lerøy Seafood Group as 15% undervalued.
Using a 6.79% discount rate, that narrative-backed estimate implies around a 15% gap between the NOK49.5 fair value and the current NOK41.9 quote. Investors can weigh this against the weaker recent returns and tighter margins. Analysts in that framework are effectively saying the recent share price decline and softer profitability are already reflected in the model, so the critical question is whether Lerøy Seafood Group can deliver on the efficiency and margin story described above.
Result: Fair Value of NOK49.5 (UNDERVALUED)
Still, the narrative around Lerøy Seafood Group can be knocked off course if inflation keeps feed and energy costs elevated, or if biological issues disrupt salmon and trout output again.
Find out about the key risks to this Lerøy Seafood Group narrative.
Another View: Lerøy Seafood Group on earnings multiples
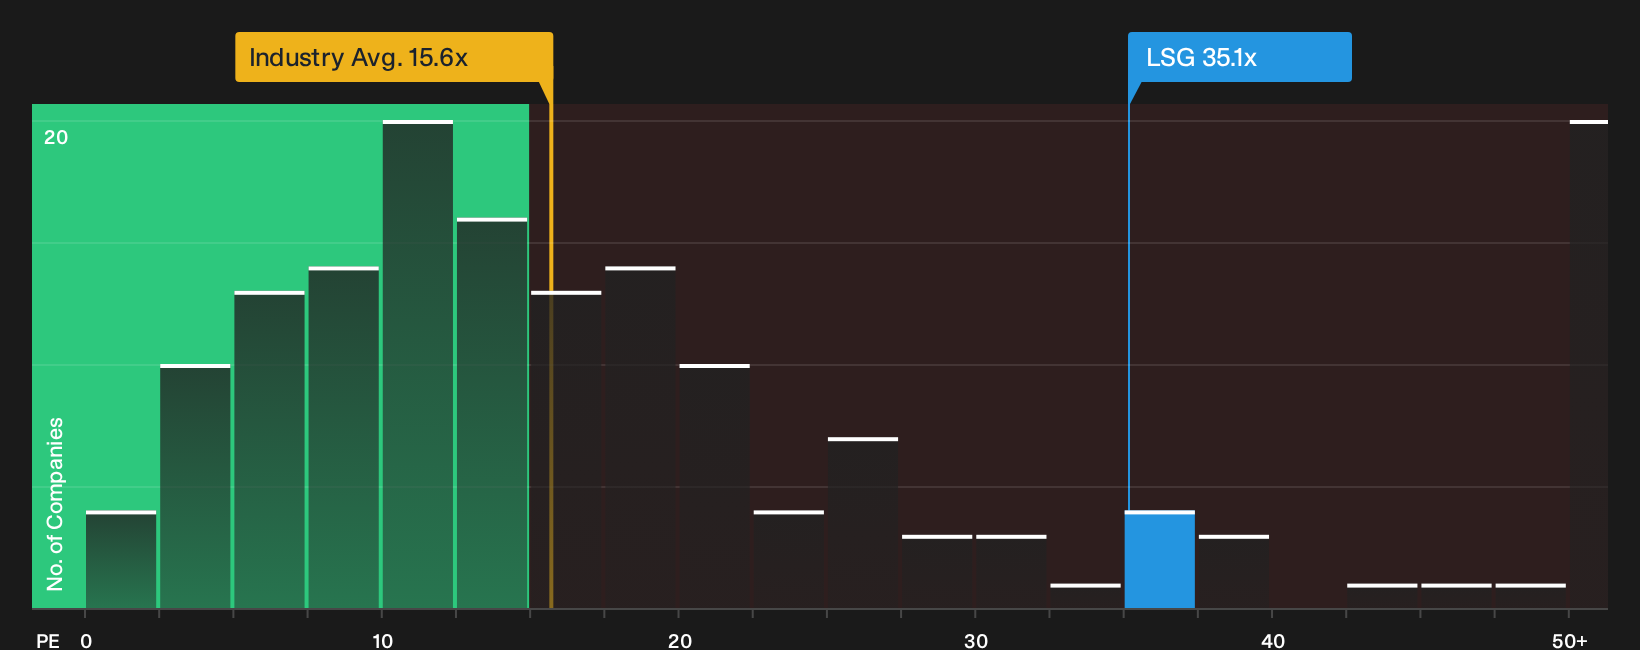
The fair value of NOK49.5 for Lerøy Seafood Group leans on analyst forecasts and discounting, yet the current P/E of 35.1x tells a different story. That valuation is richer than both peer averages at 23.1x and the fair ratio of 32.1x, which points to thinner room for error if growth or margins stumble.
Before leaning too heavily on any single fair value number, it helps to see what the underlying ratios are implying about risk and upside, and where you feel most comfortable on that spectrum. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Lerøy Seafood Group so far, right? If you want to move beyond the headline mood, walk through the full picture in the 2 key rewards and 2 important warning signs.
Looking for more Lerøy Seafood Group style investment ideas?
If Lerøy Seafood Group has sharpened your focus, do not stop here. Fresh ideas often come from comparing it with companies in very different positions.
- Target steady upside potential by screening for quality companies trading below what the market currently prices in through the 191 high quality undervalued stocks.
- Prioritise resilience in tougher markets by running the 234 resilient stocks with low risk scores and focusing on businesses with stronger risk profiles and more predictable performance.
- Hunt for future market leaders before they are widely followed using the 614 high quality undiscovered gems and see which solid operators are still flying under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com