


Revolution Medicines (RVMD) Could Be 31% Below Fair Value Following EU RASONQUE Backing
The fresh catalyst for Revolution Medicines (RVMD) is the European Medicines Agency’s positive CHMP opinion on RASONQUE for previously treated metastatic pancreatic cancer, which points to an expanded potential market beyond the U.S.
Recent trading has been choppy for Revolution Medicines, with the share price down 6.8% over the past 30 days and 1.4% over 90 days. However, the year-to-date share price return of 125.2% and a one-year total shareholder return of 228.9% suggest momentum has been strong overall as investors weigh fresh RASONQUE news, new Phase 3 trial starts, and the US$250 million debt funding draw against shifting expectations for future execution and risk.
Extend your research beyond Revolution Medicines by scanning a curated group of oncology-focused biotechs with late stage assets and funding in place using the 20 high quality undiscovered gems.
Revolution Medicines now trades well below the average analyst valuation, even after a sharp run this year. Is that discount pointing to mispricing, or does it simply mirror the risks embedded in the current pipeline and cash burn?
Most Popular Narrative: 31% Undervalued
Revolution Medicines closed at $177.96, while the most followed narrative pegs fair value at about $257.47. This frames today’s price as a steep discount built on ambitious RAS oncology assumptions.
The move toward targeted oncology treatments for high unmet need tumors such as pancreatic, lung and colorectal cancer aligns with the company’s RAS(ON) portfolio. This could influence long term revenue growth if multiple registrational programs convert to approved therapies.
Eight ongoing or planned Phase III registrational trials and clinical experience in more than 2,500 patients create multiple data points over the next few years that could change how investors view the durability and scale of the pipeline, with potential implications for future revenue visibility and earnings power.
See why 16 investors see Revolution Medicines as 31% undervalued.
The prevailing view builds that valuation on a projected fair value of $257.47, a very large uplift from the current share price, using a discount rate of 7.54% to bring long range cash flows back to today. The same storyline leans on analyst expectations for revenue to eventually reach $3.6b and earnings of $426.6m. This is in contrast to Revolution Medicines currently reporting no revenue and a substantial loss, which means your own conviction in those pipeline and margin assumptions is doing most of the heavy lifting.
Result: Fair Value of $257.47 (UNDERVALUED)
Still, the Revolution Medicines story can change quickly if pivotal RASolute or RASolve studies disappoint, or if long term cash burn runs ahead of current funding plans.
Find out about the key risks to this Revolution Medicines narrative.
Another View: What Multiples Say About Revolution Medicines
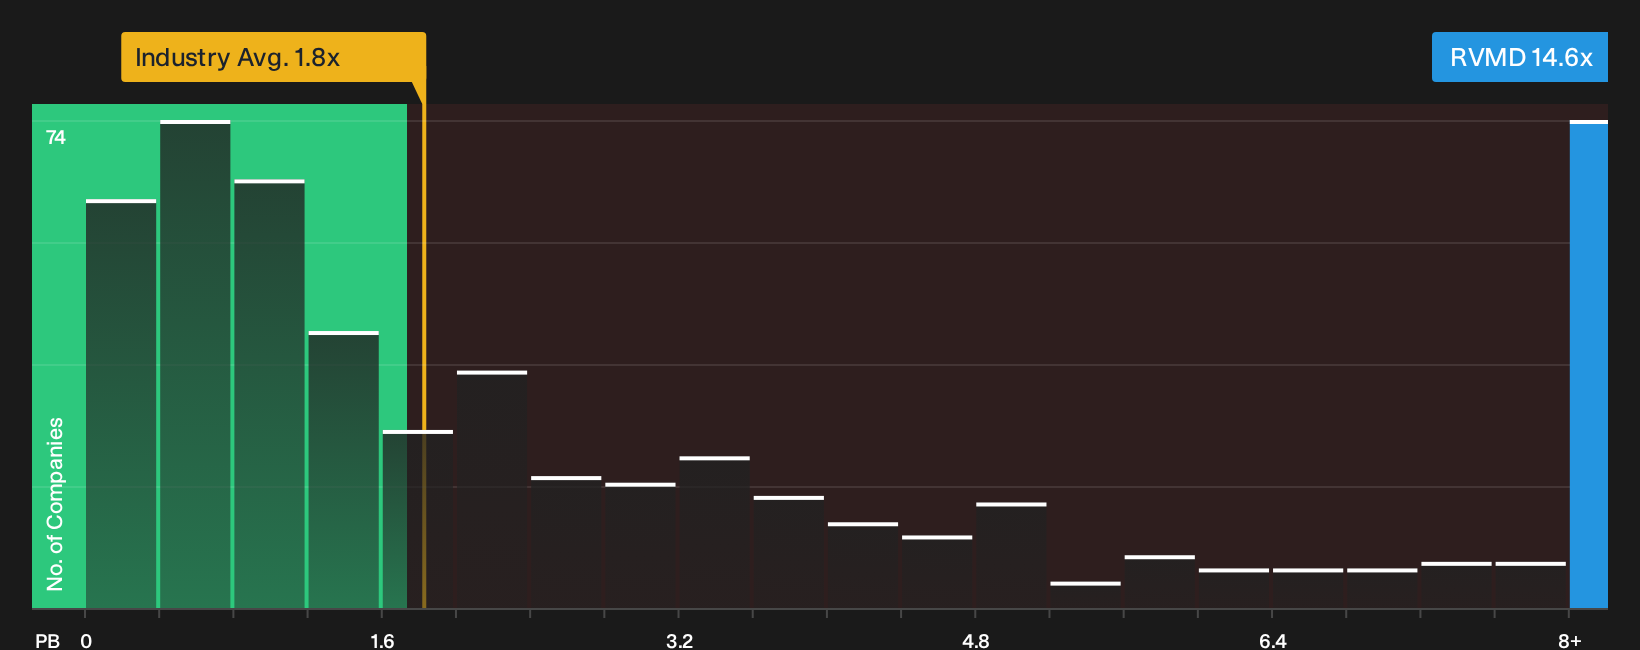
The DCF story for Revolution Medicines paints a deeply undervalued picture, yet the market is pricing the shares very differently on simpler yardsticks. The stock trades on a P/B of 14.6x versus 1.8x for the wider US Biotechs group and 11.2x for close peers, which signals investors are already paying a heavy premium for future success rather than getting a clear bargain. If the share price ever gravitates toward a lower P/B closer to peers or an eventual fair ratio, investors may want to consider how much scope there could be for upside before valuation risk starts to dominate the thesis.
To stress test that premium further against fundamentals and peer pricing, take a look at our valuation breakdown through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals like these can make Revolution Medicines hard to pin down. Move quickly, test the data yourself, and weigh both sides of the story with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Revolution Medicines?
If you stop with Revolution Medicines, you miss a wider field of potential opportunities that could better match your risk tolerance, income goals, or growth targets.
- Target high yield potential and stress test your income plan against a curated pool of resilient payers using the 8 dividend fortresses.
- Zero in on financially sound businesses and stack your watchlist with companies that have stronger balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked opportunities by scanning fundamentally strong prospects that sit off the market’s radar with the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com