


Learn Why The Bull Case For Ono Pharmaceutical Stock Could Change Following Biohaven Licensing Deal
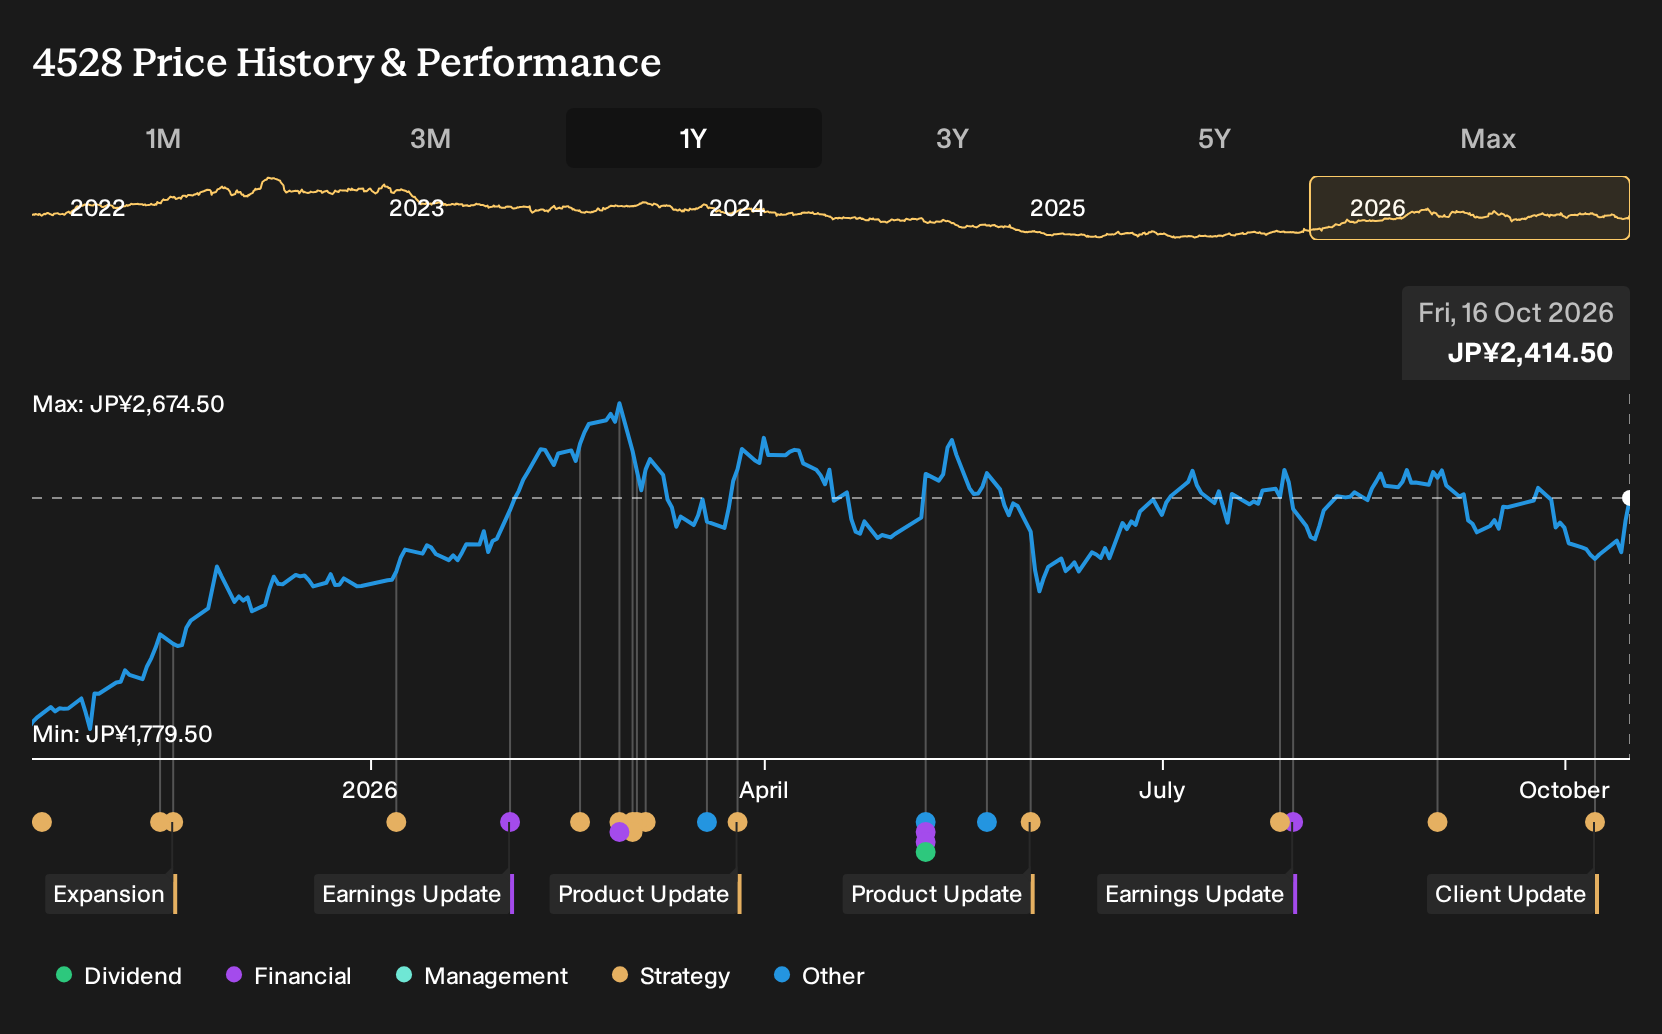
- Biohaven announced that Ono Pharmaceutical secured an exclusive license to develop and commercialize MoDE pan IgG degrader drugs BHV-1300, BHV-1310, and BHV-1320 across Japan, South Korea, Taiwan, and ASEAN. Under the agreement, Biohaven will receive up to US$100 million in near-term payments plus royalties of about 20% on regional net sales.
- The tie-up gives Ono Pharmaceutical access to late stage autoimmune candidates such as Phase 3 BHV-1300 while limiting upfront capital outlay. Ono will rely on partnering economics rather than full in-house discovery and early clinical spending across these assets.
- Next, the focus turns to how Ono Pharmaceutical's investment narrative evolves as it leans on Biohaven's MoDE degrader pipeline for autoimmune expansion.
What Is Ono Pharmaceutical's Investment Narrative?
To own Ono Pharmaceutical, you need to believe that a broad oncology and specialty portfolio can keep throwing off dependable cash flows while new therapies are added at a measured pace rather than through heavy balance sheet risk. The Biohaven MoDE degrader deal fits that mindset. Ono is leaning on external science to refresh its autoimmune pipeline in Japan and Asia without shouldering early discovery costs, which matters for a business facing forecast declines in revenue and earnings over the next three years.
In the short term, the key question is execution. That means how cleanly Ono integrates BHV-1300 into its development and commercial plans in the region, how it manages pricing power in oncology and chronic disease drugs, and whether capital stays focused on returns instead of chasing volume for its own sake. The group already offers a 3.31% dividend and trades on a P/E of 14.9x, described as below some value estimates yet slightly above the Japan pharma industry average, so the Biohaven tie up needs to support that income story rather than dilute it with rising complexity.
Even so, there is a softer undercurrent in the Ono Pharmaceutical story that can be easy to miss until you look closely at ...
There's only one way to know the right time to buy, sell or hold Ono Pharmaceutical. Head to Simply Wall St's company report for the latest analysis of Ono Pharmaceutical's Fair Value.
Exploring Other Perspectives
Fair value estimates for Ono Pharmaceutical from the Simply Wall St Community span roughly ¥2,520 to ¥3,430 across 2 separate views, which already shows how far opinions can spread before new information hits the market. The Biohaven licensing agreement adds another layer, so you might want to compare several community perspectives before deciding what matters most.
Explore another Ono Pharmaceutical fair value estimate, including one that suggests as much as 42% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ono Pharmaceutical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ono Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ono Pharmaceutical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ono Pharmaceutical?
Once you have a view on Ono Pharmaceutical, it often helps to widen the lens and compare it with other opportunities that share some of the qualities you care about most, whether that is value, balance sheet strength, or potential mispricing.
- If you are hunting for quality at a reasonable entry point, scan a curated set of 13 high quality undervalued stocks that combine solid fundamentals with prices that some investors may see as appealing.
- For readers who care most about capital preservation and steadier profiles, filter the market through a 23 resilient stocks with low risk scores to see which businesses line up with a more cautious approach.
- When you want to move beyond well known tickers and look for potential future leaders, sort through a 73 high quality undiscovered gems that pair robust financials with lighter coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com