


WEX (WEX), Why Is The Market Taking A Closer Look?
WEX (WEX) has drawn attention after its shares closed at US$182.01 on the latest trading day, with recent price swings contrasting with longer term total return figures spanning the past year to 5 years.
Recent trading paints a mixed picture for WEX, with a 7 day share price return of 5.56% and a 90 day gain of 11.33%, offset by a 30 day share price decline of 5.97%. The 1 year total shareholder return of 20.93% contrasts with slightly negative 3 and 5 year total returns, which may hint at momentum rebuilding after a weaker stretch.
Compare WEX's recent rebound with a hand-picked group of financials showing similar price action and fundamentals by scanning the list of solid balance sheet and fundamentals (25 results) today.
WEX runs a sizeable payments platform and reports solid revenue and net income figures. Yet the recent share price rebound raises a tougher question: Are investors paying a fair price for that quality today, or stretching for the recovery story?
Most Popular Narrative: 7% Undervalued
Compared with WEX's last close at $182.01, the most widely followed narrative anchors fair value at $195.36. This implies a modest discount that depends on execution in payments and benefits rather than a dramatic reset in expectations.
The shift in capital allocation toward share repurchases is supported by leverage at 2.9x within the 2.5 to 3x target range, roughly US$696m to 700m of adjusted free cash flow over the last 12 months and a US$1b authorization. This means more of WEX’s cash generation is directed to reducing the share count, which can lift adjusted EPS even if revenue growth stays within the guided organic range.
See why 8 investors see WEX as 7% undervalued.
Result: Fair Value of $195.36 (UNDERVALUED)
Still, two pressure points could upset the WEX story: any sustained hit to fuel card volumes from electric vehicle adoption, and tougher pricing or competition in Corporate Payments that squeezes transaction margins.
Find out about the key risks to this WEX narrative.
Another View: What WEX’s P/E Is Really Saying
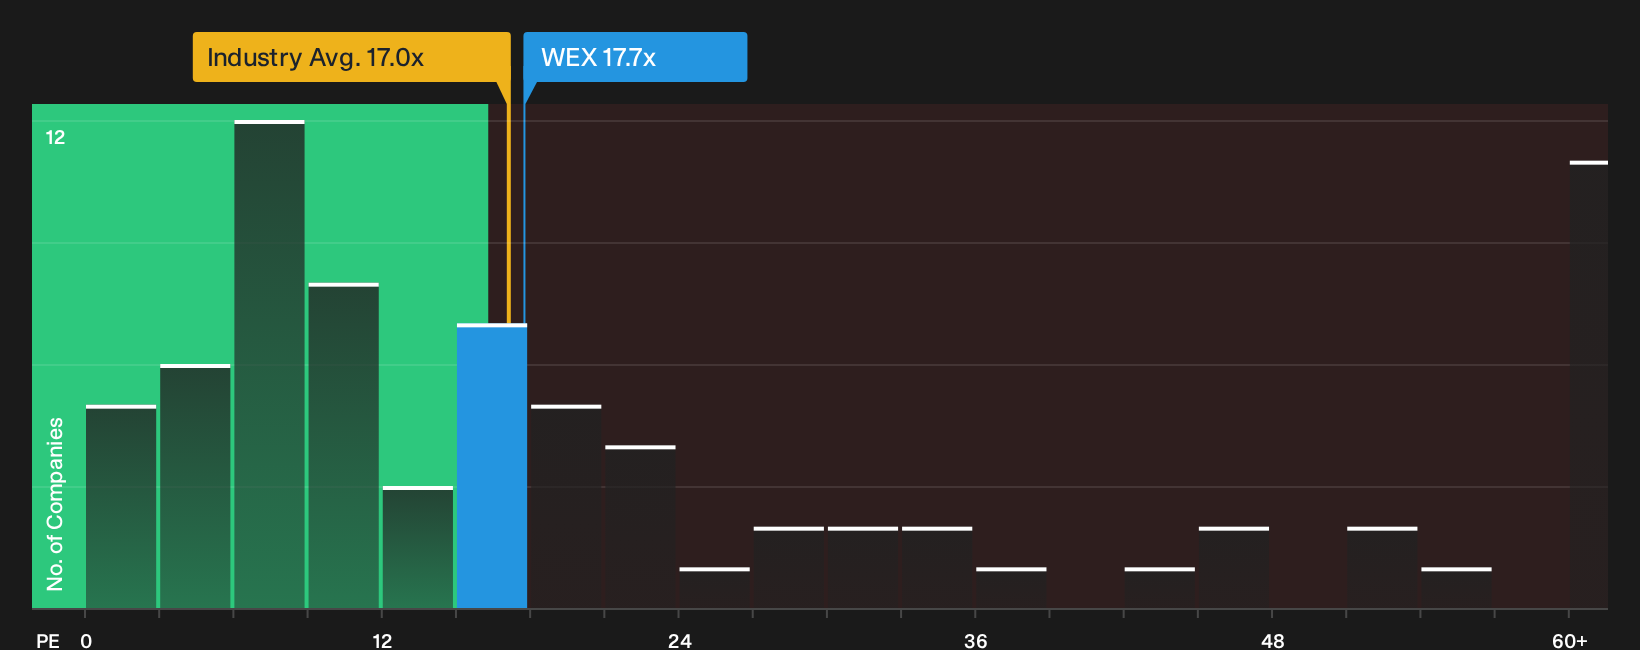
That 7% undervalued fair value hinges on future cash flows, yet the simple earnings multiple is less forgiving. WEX trades on a P/E of 17.7x, above the US Diversified Financial industry on 17x and peers on 17.3x, while the fair ratio suggests 13.5x. That gap points to valuation risk if growth or margins disappoint.
For a closer look at how those earnings multiples line up with fundamentals, and where the market could shift if sentiment cools, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on WEX’s value case today. Take a few minutes to run the numbers yourself, weigh the risks against the upside, and then check the 3 key rewards and 2 important warning signs.
Looking for more WEX investment ideas?
If you stop with WEX, you miss a broader opportunity set. Let the data surface ideas so you are not guessing where to look next.
- Target potential mispricings by scanning companies flagged as 33 high quality undervalued stocks before other investors pay attention.
- Lock in steadier income by reviewing a focused pool of 8 dividend fortresses that aim to pair yield with resilience.
- Reduce portfolio stress by concentrating on a 32 resilient stocks with low risk scores that filters for stronger balance sheets and milder drawdowns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com