


Record Markets Revenue Could Be A Big Moment For BNP Paribas Stock
- BNP Paribas recently reported record 2025 revenues in its Global Markets division, with 9.1% year-on-year growth and a 7.2% compound annual growth rate since 2020, while institutional client activity rose 12% and wallet share increased each year for five consecutive years.
- This sustained expansion in Global Markets and faster growth in institutional client business points to deeper client penetration and stronger fee-generating capacity across BNP Paribas' capital markets platform.
- We will look at how BNP Paribas' investment narrative is shaped by Global Markets' record 2025 revenues and sustained institutional client gains.
Scan beyond BNP Paribas and compare its Global Markets momentum with a hand-picked 191 high quality undervalued stocks that may offer similar institutional flows at more modest valuations.
BNP Paribas Investment Narrative Recap
To own BNP Paribas, you need to be comfortable with a big universal bank that leans on Eurozone retail and corporate banking while trying to squeeze more efficiency and fee income out of a large platform. The key short term swing factor is execution on its efficiency and AI program, which aims to push the cost/income ratio closer to 50% over time.
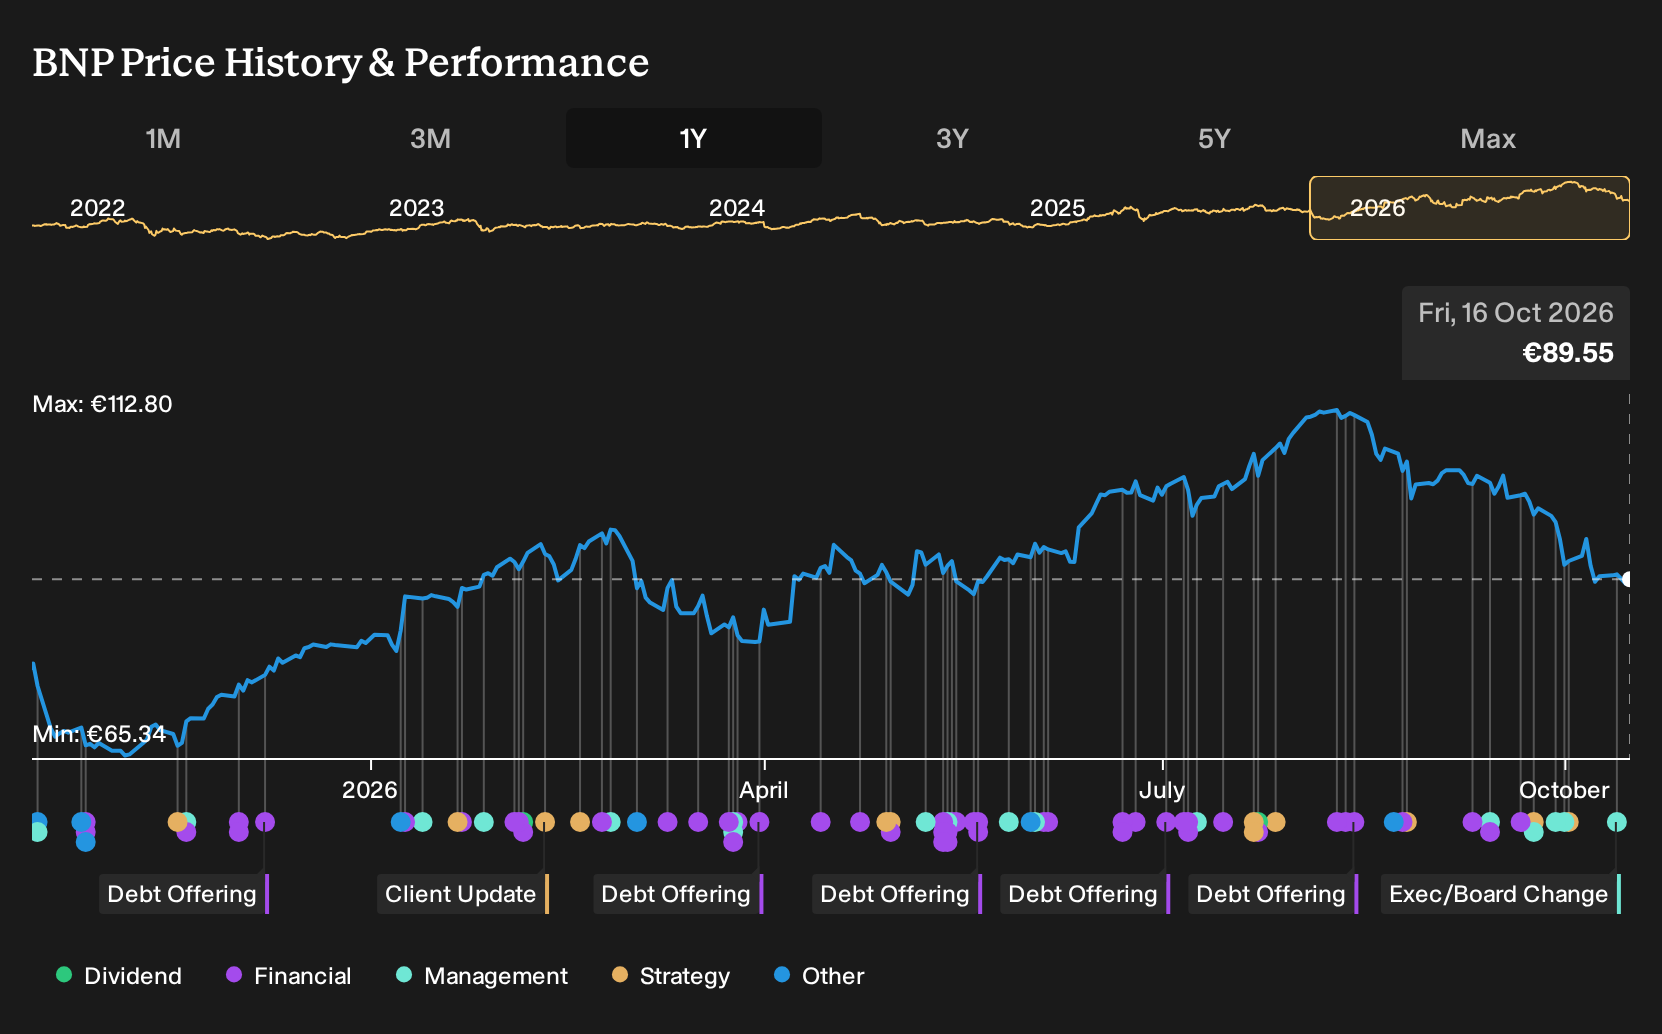
On the risk side, pressure in Arval from used car markets, regulatory constraints in core European countries, and ongoing ESG litigation remain front of mind. The recent share pullback and oversold technicals change sentiment more than operations, so they do not materially alter those core business drivers right now.
The appointment of Aman Mehra to lead transaction banking sales for North and East India looks most relevant to the Global Markets and institutional client story around BNP Paribas. Expanding experienced coverage in India ties directly into transaction banking, cash management and trade finance, which sit alongside the capital markets franchise serving large corporates.
For you as a shareholder, the interest is whether deeper transaction banking penetration in a growth market can reinforce fee income and cross sell into Global Markets over time. Execution risk is real, given higher risk wholesale funding and existing bad loan and ESG issues. A stronger Indian franchise can support the broader originate and distribute and asset gathering ambitions if management delivers.
BNP Paribas Consensus Growth And Valuation Frame
For BNP Paribas, the current analyst story is built around steady expansion of the revenue base and a meaningful lift in earnings power over the next few years. Instead of chasing a blue sky scenario, the consensus pins numbers to a relatively measured top line and profit profile that you can actually compare against your own expectations.
Forecasts in the stock reports point to revenue rising by 6.0% each year over the next three years. That pace is not aggressive for a large universal bank and gives you a clean anchor for thinking about how Global Markets and the broader Eurozone franchise might contribute to the group total. Profit margins are expected to move from 24.9% today to 26.9% in three years. A two point shift sounds small, yet on tens of billions of sales it can have a sizeable effect on bottom line profit.
Consensus earnings today are quoted at €12.8b. Analysts expect that figure to reach €16.4b by 2029, with the most optimistic views stretching to €18.5b. The move from €12.8b to €16.4b implies an earnings increase of about 28% over the period, which would materially reshape the income statement even without heroic revenue assumptions. One key plank in that bridge is the efficiency and AI program, which is intended to trim the cost base and support that higher margin profile.
Valuation work then takes those operating forecasts and asks what multiple investors might pay if they materialise. The consensus numbers imply revenues of €61.0b and earnings of €16.4b in 2029 and assume the stock trades on a P/E of 10.7x at that point. That compares with about 7.7x today and a GB Banks sector figure of 7.8x mentioned in the research, so the story is not only about higher profits but also about investors assigning a richer earnings multiple to BNP Paribas in future.
BNP Paribas' narrative projects €61.0b revenue and €16.4b earnings by 2029. This rests on 6.0% yearly revenue growth and an earnings increase of about €3.6b from €12.8b today.
Uncover why BNP Paribas' fair value indicates a 33% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly €119 at the low end to about €215 at the top, so you are seeing private investors model BNP Paribas at almost 2x apart. Set that against fresh catalysts such as the Paris biotech and health seminar and the senior India hire, and you get plenty of room for opinions to clash. Use that spread as a prompt to review several alternative viewpoints before deciding how Global Markets progress and Eurozone banking risks might shape your own stance.
Explore another BNP Paribas fair value estimate, including one that suggests it could be worth just €119.07!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your BNP Paribas research is our analysis highlighting 5 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BNP Paribas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BNP Paribas' overall financial health at a glance.
Looking For More Investment Ideas Beyond BNP Paribas?
Once you have a view on BNP Paribas, it can help to line it up against other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that fits how you actually invest rather than a one size portfolio.
- If capital preservation comes first for you, start with companies that show stronger resilience on key risk checks through the 234 resilient stocks with low risk scores.
- If you care most about balance sheet strength and underlying business quality, narrow the field to companies with robust finances using the list of solid balance sheet and fundamentals (204 results).
- If you want to hunt for underfollowed opportunities with sound fundamentals, cast a wider net through the 614 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com