


Goosehead Insurance (GSHD) Valuation Debate Puts Fair Value Back In Focus
Fresh debate around Goosehead Insurance (GSHD) has picked up after analysts split on its valuation, with bulls pointing to enterprise and embedded channel expansion while bears flag pressure from commission rates and rising competition.
Recent trading has been choppy for Goosehead Insurance, with a 1-day share price return of 1.75% and 7-day gain of 6.64% following a 30-day share price drop of 14.94% and year-to-date decline of 33.87%. This aligns with a 1-year total shareholder return loss of 30.77% and points to fading longer term momentum, even as short term moves react quickly to each new twist in the valuation debate.
Scan how Goosehead Insurance compares with other insurers facing a similar valuation debate by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
For Goosehead Insurance, a year of sharp drawdowns now sits alongside fresh optimism about enterprise and embedded growth. The real issue is whether the meaningful upside sits ahead or if most of the rerating already happened on the recent bounce.
Most Popular Narrative: 31% Undervalued
Against Goosehead Insurance's last close of $46.40, the most followed narrative anchors on a fair value of $67.25, framing today’s debate around whether investors are overlooking its earnings power at this discount rate of 7.24%.
Goosehead Insurance's capital light model, together with over 1 million Class A shares repurchased for US$53.7 million year to date in Q2 2026 and a remaining authorization of US$144.6 million, supports ongoing buybacks alongside US$25 million to US$35 million of annual investment in digital and AI tools. This can lift per share earnings and improve return on capital over time.
See why 10 investors see Goosehead Insurance as 31% undervalued.
Result: Fair Value of $67.25 (UNDERVALUED)
Still, the Goosehead Insurance story can break if rising compensation and general expenses continue to run ahead of revenue, or if Digital Agent spending keeps squeezing margins longer than analysts expect.
Find out about the key risks to this Goosehead Insurance narrative.
Another View: Goosehead Insurance On Earnings Multiples
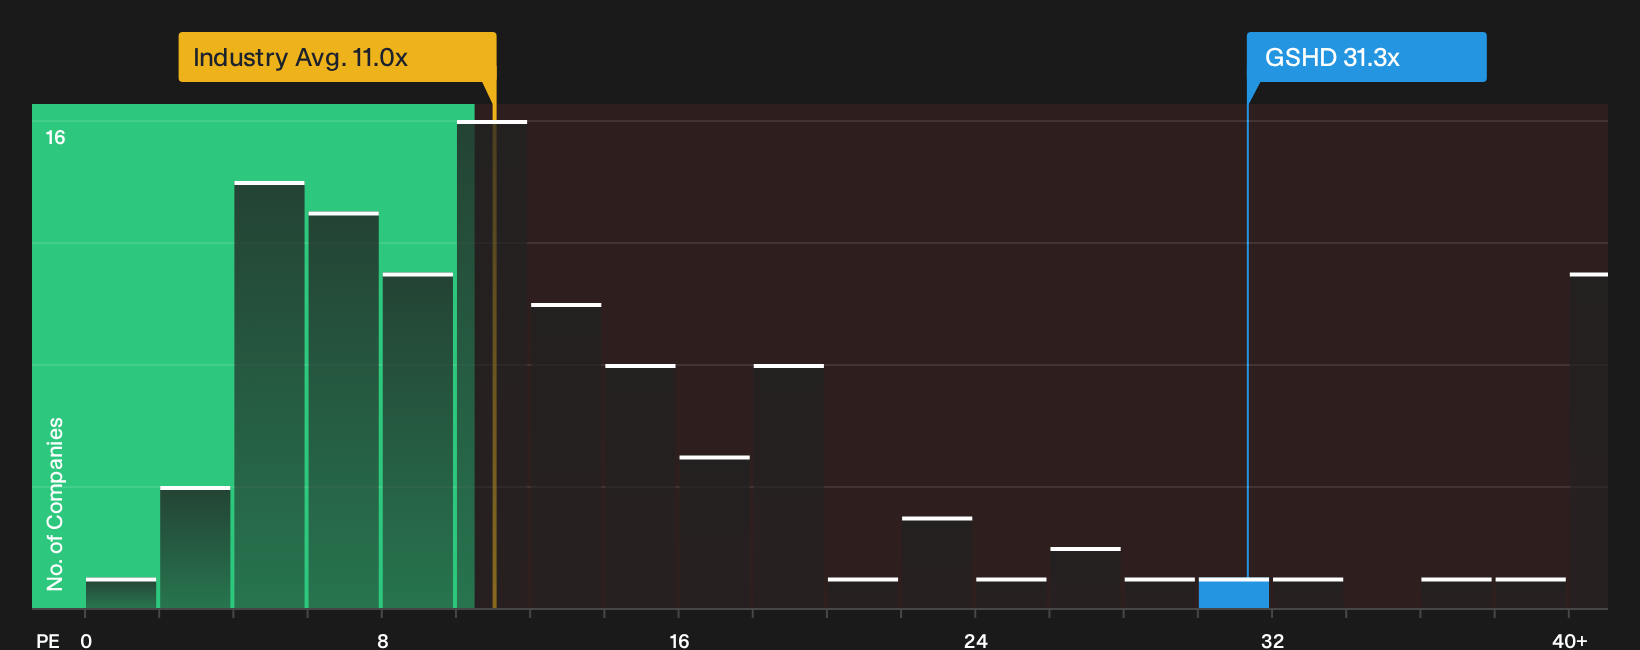
There is a different read on Goosehead Insurance when looking at the current P/E. At 31.3x, the stock trades well above the US Insurance industry on 11x and above its own fair ratio of 20.1x, although it sits below a 47.3x peer average.
That mix of richer pricing than the wider sector, yet cheaper than closer peers, suggests valuation risk if sentiment cools and opportunity if earnings align more closely with higher growth expectations. Which side of that gap do you think the market eventually closes toward?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Given the mixed mood around Goosehead Insurance, it makes sense to look at the numbers yourself and weigh both risks and potential upside before the next move. To see the full balance of concerns and bright spots in one place, review the 3 key rewards and 2 important warning signs.
Looking for more Goosehead Insurance style ideas?
If Goosehead Insurance has you rethinking your watchlist, use this moment to widen your search and spot other opportunities before they move without you.
- Target stronger value potential by checking companies that screen as quality and priced below their estimates of worth through the 32 high quality undervalued stocks.
- Prioritize resilience by reviewing a 32 resilient stocks with low risk scores that focuses on businesses with steadier risk scores and fewer financial red flags.
- Get ahead of the crowd by scanning 20 high quality undiscovered gems that combine solid fundamentals with less attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com