


WSFS Financial (WSFS) Could Be 14% Undervalued As Leadership Changes Reshape Governance
Leadership moves reshape WSFS Financial governance
WSFS Financial (WSFS) refreshed key oversight roles on 6 October 2026 by naming Michael Thompson Interim Chief Accounting Officer, appointing Charles Mosher as Chief Audit Executive, and promoting Lisa Washington to Executive Vice President, Chief Legal Officer and Corporate Secretary.
WSFS Financial’s recent governance shuffle comes at a moment when the share price has gained 38.69% year to date to US$76.35, with shorter term momentum softening over the past month. Even so, a 50.35% 1 year total shareholder return and a very strong 3 year total shareholder return of 130.56% indicate that longer term holders have been materially rewarded for staying invested.
Spot similar governance focused banks by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results).After that 38.69% year to date climb, WSFS Financial now trades at US$76.35 against analyst estimates around US$88 and a much deeper intrinsic value gap. So where does fair value really look anchored for this bank?
Most Popular Narrative: 14% Undervalued
On the most followed view of WSFS Financial, a fair value of about $88.92 sits ahead of the current $76.35 share price, which puts the bank in the spotlight for how it manages its mix of fee income, funding costs and capital returns.
Continuation of high core ROA and core ROTCE, together with capital levels above the stated CET1 target, provides room for WSFS Financial to keep returning a large portion of earnings through share repurchases, which can lift earnings per share even if overall revenue growth is modest.
See why 0 investors see WSFS Financial as 14% undervalued.
Result: Fair Value of $88.92 (UNDERVALUED)
Still, the WSFS Financial story could be tested if deposit competition forces materially higher funding costs, or if softer Cash Connect activity drags on fee income.
Find out about the key risks to this WSFS Financial narrative.
Another view on WSFS Financial’s valuation
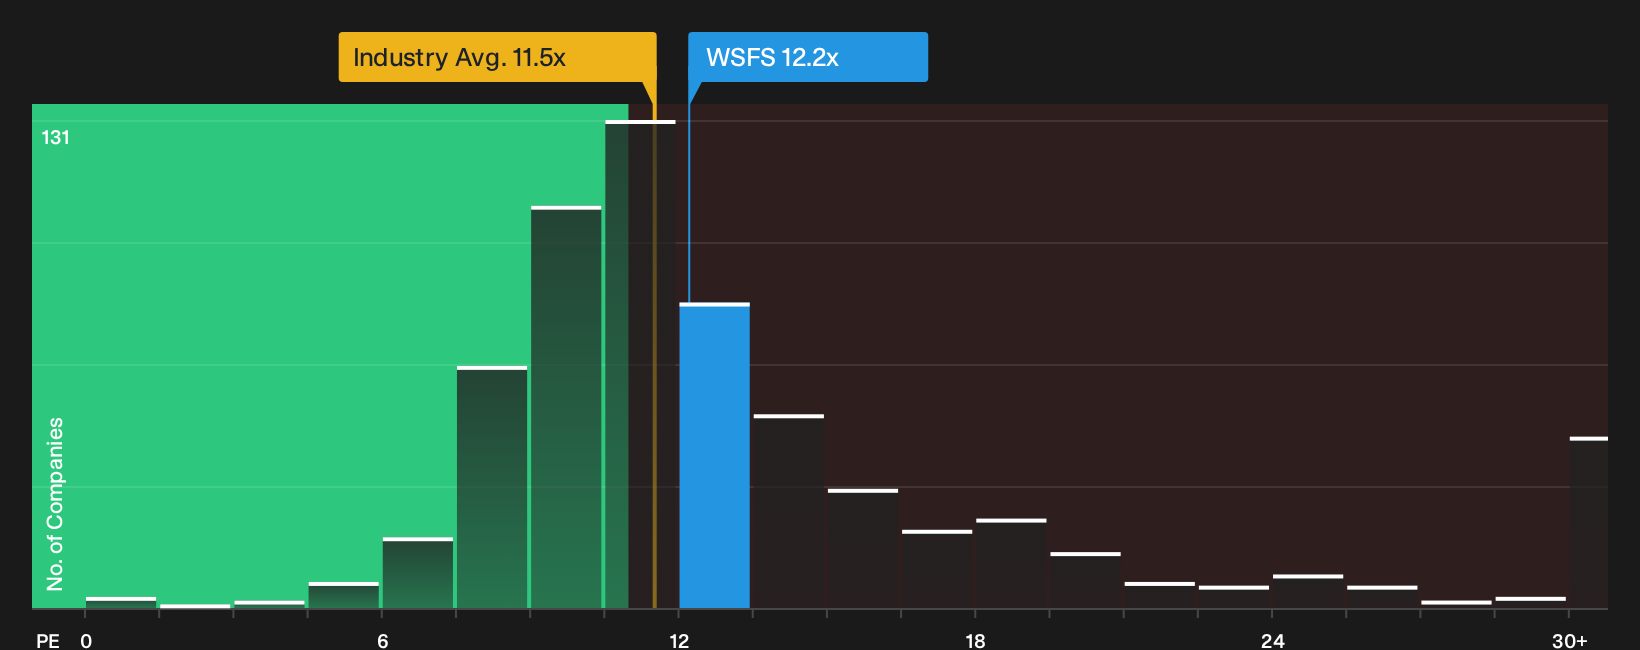
On simple earnings multiples, WSFS Financial looks less generous than the narrative suggests. The bank trades on a P/E of 12.2x compared with 11.5x for the US Banks industry and a fair ratio of 10.6x, which points to some valuation risk if sentiment cools.
That gap means investors are already paying a premium for WSFS Financial’s earnings stream. Any stumble in execution or shift in expectations could matter more than the headline discount to fair value might imply. It also raises the question of which yardstick you trust when the signals disagree.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on WSFS Financial’s valuation and governance moves can feel exciting and uncomfortable at the same time, so act quickly and test the numbers yourself. To weigh both sides of the story, start with the 2 key rewards and 1 important warning sign.
Looking for more WSFS Financial sized ideas?
If you stop with WSFS Financial, you risk missing other opportunities. Put a shortlist together now so the next move is ready before the market shifts.
- Target potential upside by scanning a curated pool of quality candidates through the 20 high quality undiscovered gems.
- Strengthen your defensive side by focusing on resilient businesses using the 32 resilient stocks with low risk scores.
- Hunt for value opportunities that pair robust fundamentals with appealing pricing with the 33 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com