


Learn Why The Bull Case For Interface (TILE) Could Change Following Carpet Tile Launch
- Interface introduced Twist & Texture, a modular carpet tile collection with seven textile-inspired styles, 18 colorways per style, QuickShip availability, and a single price point designed for fast commercial projects.
- The launch reflects Interface's focus on modular design, carbon-storing materials, and end-of-life solutions, aligning product development with circular economy goals.
- The next step is to examine how Interface's investment narrative could be influenced by the Twist & Texture launch and its QuickShip positioning.
Scan 20 high quality undiscovered gems to find other design led flooring and interiors stocks that, like Interface, pair product depth with fast delivery and sustainability credentials.
Interface Investment Narrative Recap
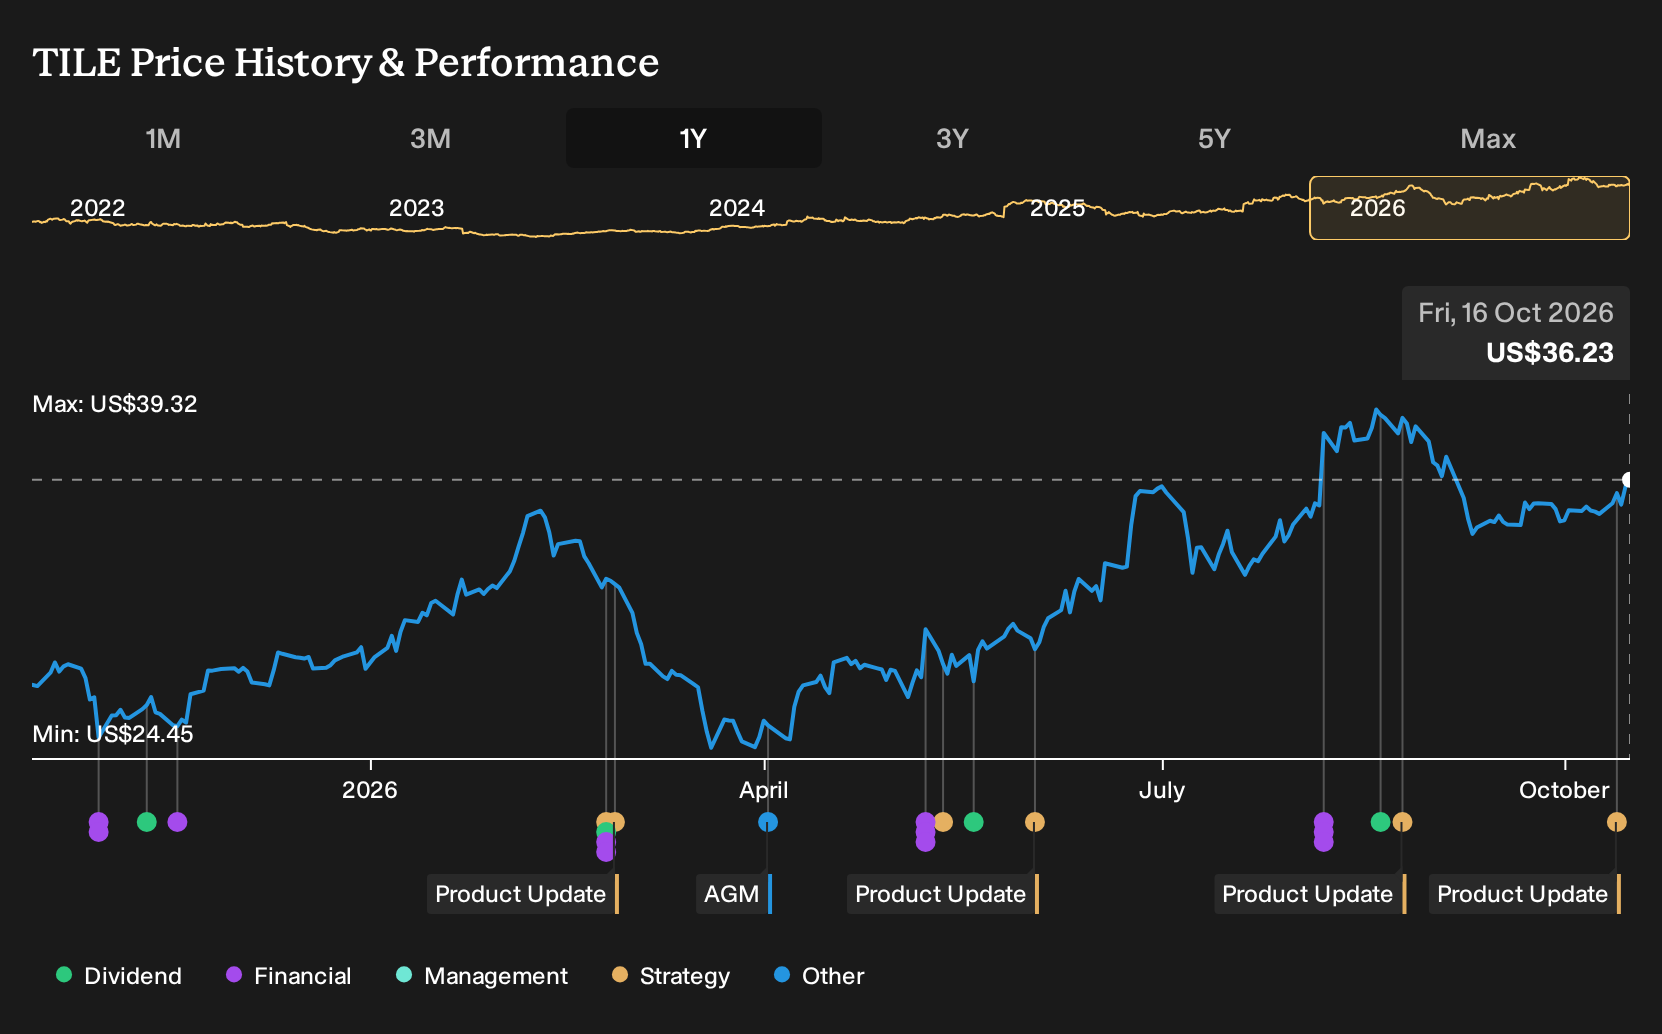
To own Interface, you need to believe the business can keep turning its One Interface model, product depth, and sustainability focus into steady demand across corporate, education, and healthcare interiors while protecting margins. The Twist & Texture launch and QuickShip promise speak directly to that thesis, but on their own they do not materially change the near term story.
The more immediate swing factors still sit with execution on automation, tariff pass through, and order conversion into backlog and earnings, especially after a strong share price run and higher expectations. Twist & Texture can support those efforts at the margin by feeding specifications, but valuation risk and tariff exposure remain the key near term watchpoints.
The Twist & Texture collection ties closely to one existing catalyst that already matters for Interface: the expansion of more approachable price point offerings like Open Air carpet tiles and thinner gauge LVT. Both push the business deeper into mid market projects where design, speed, and simplicity carry real weight for specifiers and project managers.
QuickShip availability, a single price point, and modular design keep Twist & Texture aligned with that same operational focus on volume, mix, and margin structure. If the firm continues to pair these launches with automation and robotics in its plants, the key question for you is whether that combination can offset tariff headwinds and justify the higher expectations embedded in analyst forecasts.
Interface's narrative projects US$1.7b revenue and US$157.1 million earnings by 2029. This assumes 5.9% yearly revenue growth and an earnings increase of US$11.5 million from US$145.6 million today.
Uncover how Interface's fair value indicates a 25% potential upside to its current price before the gap between price and value narrows.
Exploring Other Perspectives
One alternate view around Interface focuses on the risk that renovation heavy corporate demand cools once current refresh cycles ease. The most cautious analysts were still modeling about US$1.7b revenue and US$161.8 million earnings by 2029, yet saw only an 8.6% upside to US$41.00. That gap shows how widely opinions can differ. You can use those pre Twist & Texture numbers as a reference point and consider whether this new launch might eventually shift expectations toward or away from that more bearish outlook.
Explore 2 other Interface fair value estimates, including one that suggests it could be worth just $41.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Interface research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Interface. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Interface's overall financial health at a glance.
Looking For More Ideas Beyond Interface?
If the Twist & Texture story has sharpened your view on Interface, it can help to line that thesis up against other companies with different balance sheets, income profiles, and risk levels.
- If you want potential value opportunities that pair healthier fundamentals with a discounted entry point, start with 33 high quality undervalued stocks and see which businesses fit your criteria.
- If income is a priority and you prefer established cash returns over price moves, scan 8 dividend fortresses to find companies offering higher yields with a focus on payout resilience.
- If capital protection matters most and you would rather tilt toward sturdier profiles, review 32 resilient stocks with low risk scores and compare how those stocks stack up against Interface on risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com