


Do Earnings Revisions Change The Bull Case For Cracker Barrel Stock?
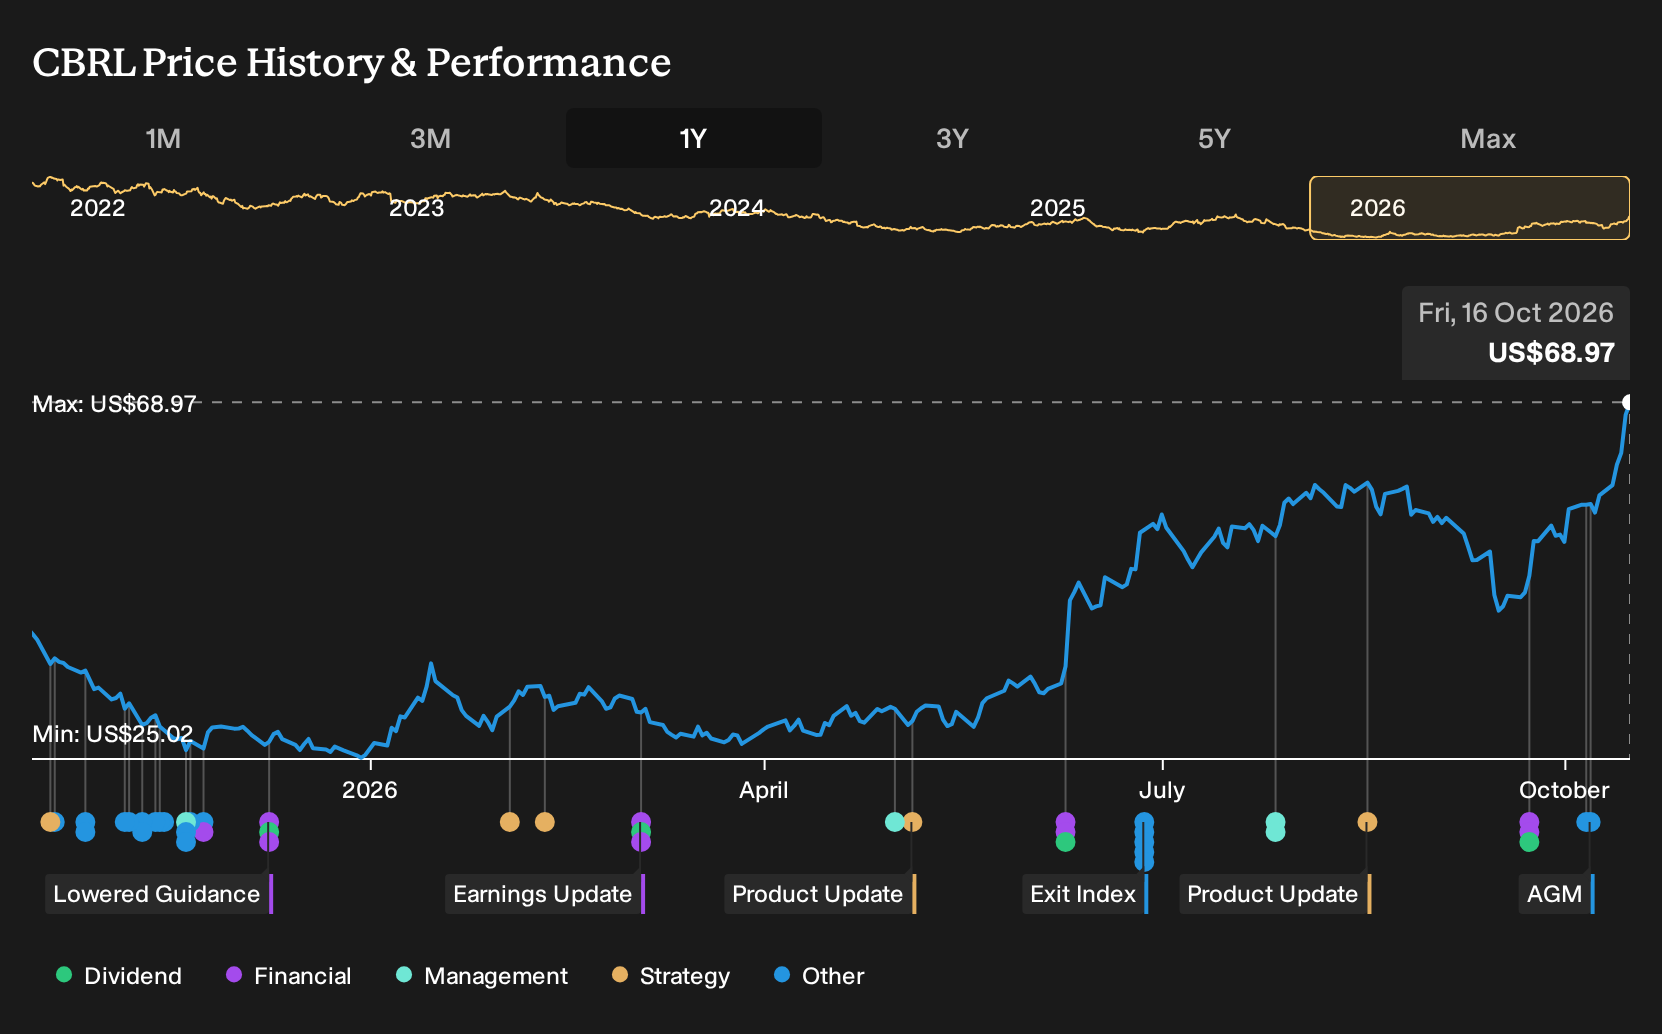
- Cracker Barrel Old Country Store filed a definitive proxy statement on October 6, 2026, urging shareholders to reject a proposal that would require investor approval before issuing blank check preferred stock, except when used for routine capital raising or acquisitions without changing voting power.
- The pushback against tighter controls on preferred stock issuance highlights how Cracker Barrel Old Country Store values financial flexibility at a time when analysts are revising earnings estimates and watching how capital structure choices interact with operating goals.
- We will now examine how Cracker Barrel Old Country Store's earnings estimates and momentum score interact with its broader investment narrative.
Cracker Barrel Old Country Store Investment Narrative Recap
To own Cracker Barrel Old Country Store, you need to believe the guest experience and rewards program eventually translate into steadier traffic and healthier restaurant level profits. Management is already leaning on value messaging and a roughly US$15.85 average check, so the near term catalyst remains any sign that high single digit traffic declines start to moderate.
The biggest risk is that consumer spending stays soft and those traffic drops persist even as guest scores and loyalty signups improve. The blank check preferred stock debate in the proxy statement does not materially change that near term equation, although it does underscore how seriously the board treats financial flexibility.
The definitive proxy filed on October 6, 2026 is the key disclosure around this news. Cracker Barrel Old Country Store asked investors to vote against tighter limits on blank check preferred stock, while still acknowledging ordinary use for funding or acquisitions without altering voting power. That points you back to the real operational swing factors.
Execution still hinges on converting US$3.3b of largely restaurant revenue into better margins and earnings without leaning only on cost cuts. Rewards members already drive over 40% of tracked sales and management is targeting US$180 to US$200m of adjusted EBITDA by fiscal 2027, so any stumble on traffic or value perception would weigh on those ambitions more than the proxy fight itself.
Cracker Barrel Old Country Store's current analyst narrative points to revenue of US$3.6b and earnings of US$62.0m by 2029, based on 2.5% yearly top line growth and an earnings move of about US$30.3m from US$31.7m today.
Uncover how Cracker Barrel Old Country Store's fair value indicates a 26% potential downside to its current price, a premium that may not be sustainable.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst around Cracker Barrel Old Country Store’s AI and data tools rather than the proxy fight itself. Before this news, the bullish camp was modeling revenue of about US$3.6b and earnings near US$68.7m by 2029. That is far rosier than consensus, so you may see forecasts shift as investors rethink how much flexibility on blank check preferred stock matters for future decisions on technology, staffing, and loyalty investments.
Explore 3 other Cracker Barrel Old Country Store fair value estimates, including one that suggests it could be worth as much as $64.28.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Cracker Barrel Old Country Store research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cracker Barrel Old Country Store. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cracker Barrel Old Country Store's overall financial health at a glance.
Looking for more investment ideas beyond Cracker Barrel Old Country Store?
If the Cracker Barrel Old Country Store story has you thinking about capital allocation, earnings power, and downside risk, it can be useful to scan for other businesses that fit different parts of that checklist. Use the Simply Wall St Screener to widen your watchlist while still keeping a clear focus on quality and risk control.
- For investors who want income that can potentially complement more cyclical holdings, check out 8 dividend fortresses that may offer robust payouts supported by underlying fundamentals.
- If balance sheet strength is your anchor, review the list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with room to handle shocks without constant refinancing pressure.
- Prefer to keep risk in check while you research each individual story, including Cracker Barrel Old Country Store, by scanning through 32 resilient stocks with low risk scores that score well on overall resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com