


Is Texas Instruments (TXN) Undervalued On Its New Data Center Hardware Push?
Texas Instruments product launch puts data center reliability in focus
Texas Instruments (TXN) has introduced new analog hardware aimed at power monitoring, protection and timing in AI data centers, giving investors fresh detail on how the business is targeting this infrastructure build-out.
Recent trading shows a mixed picture around Texas Instruments. The share price has eased over the past week but logged a 7.10% 1‑month share price return, while the year-to-date share price return of 55.75% and 3-year total shareholder return of 103.82% point to momentum that has built over time rather than faded.
Spot opportunities around Texas Instruments' AI data center push by scanning a hand-picked group of 55 AI infrastructure stocks.Texas Instruments now has a clear AI data center angle and a track record of shareholder gains behind it. The harder question is whether that combination is already fully reflected in a US$276 share price.
Most Popular Narrative: 36.5% Undervalued
Against a last close of $276.48, the most widely followed narrative on Texas Instruments pegs fair value at $435.69, leaving a sizable valuation gap that investors are actively debating.
Texas Instruments is in the midst of a multiyear capacity-expansion cycle that is temporarily suppressing free cash flow but materially enhancing the company’s long-term competitive position. The buildout of U.S.-based 300mm analog manufacturing is expected to structurally improve cost efficiency, support higher gross margins, and increase supply-chain resilience. As these assets ramp and utilization normalizes, TXN should regain its historical free-cash-flow profile, supported by diversified end-market exposure across industrial, automotive, aerospace/defense, and energy infrastructure.
See why 20 investors see Texas Instruments as 37% undervalued.
Result: Fair Value of $435.69 (UNDERVALUED)
Still, Texas Instruments faces real pressure points if utilization at its new fabs lags expectations or if AI-related hardware demand in data centers proves patchier than bulls assume.
Find out about the key risks to this Texas Instruments narrative.
Another View: Texas Instruments Through Market Ratios
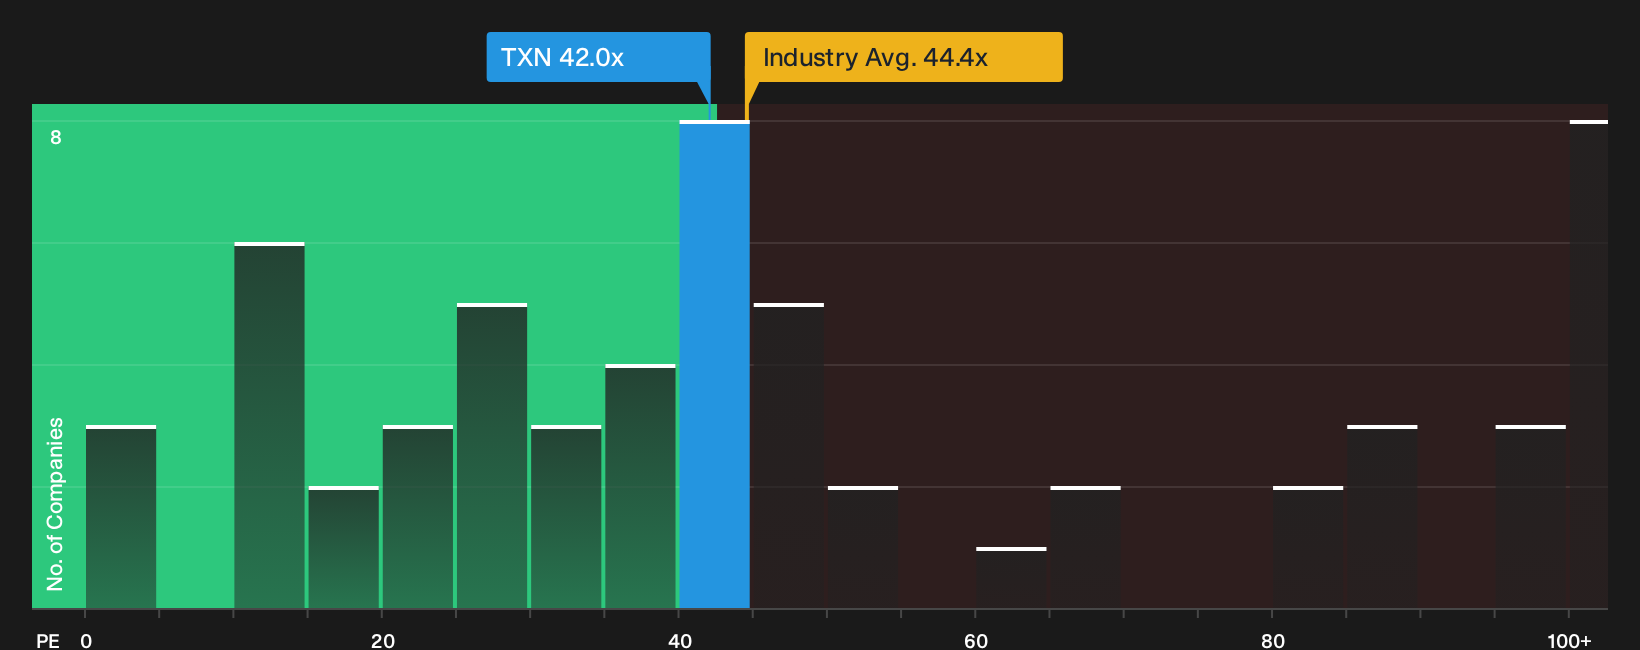
That user narrative argues Texas Instruments is 36.5% undervalued at a fair value of $435.69. Market ratios tell a cooler story. TXN trades on a 42x P/E, above a fair ratio estimate of 34x, even though it sits slightly below the US Semiconductor average of 44.4x and well under a 69x peer average. For investors, that mix of premium to fair ratio but discount to peers raises a simple question: Is this pricing a margin of safety or a sign of limited upside?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals and strong opinions only get you so far. Pull up the data, weigh Texas Instruments' risks against its potential rewards, and then see the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Texas Instruments?
Texas Instruments may be front of mind today, but you leave money on the table if you stop your research with a single ticker.
- Target resilient compounding potential by scanning a curated set of 32 resilient stocks with low risk scores that aim to keep drawdowns in check when markets turn.
- Hunt for quality at a discount with a focused list of 33 high quality undervalued stocks that pair stronger financials with prices that have not fully caught up.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses that rely less on fragile financing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com