


Boeing (BA) Could Be 53% Below Fair Value On 737 MAX 10 Progress
Boeing (BA) is back in focus after progress toward FAA certification of the 737 MAX 10, combined with fresh defense wins and missile seeker contracts, has reframed how investors are weighing the stock.
For context, Boeing shares trade at US$190.21 after a year-to-date share price decline of 16.5%, while the 1-year total shareholder return is down 10.7% and the 3-year total shareholder return is up 5.7%. This suggests longer term holders have seen modest gains even as recent momentum has faded. Fresh headlines around 737 MAX 10 certification, multi year fighter jet awards and the ramp up in PAC-3 missile seeker production are now landing against that weaker near term share price performance. As a result, investors are starting to reassess whether the recent pullback better reflects growth potential in both the commercial and defense franchises or ongoing concerns about execution risk and cash conversion.
Spot other aerospace and defense opportunities moving on similar contract and delivery themes by scanning our hand-picked 20 high quality undiscovered gems alongside Boeing.Boeing now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after a sharp pullback. Is that a pricing error, or a fair warning label on execution and cash risk?
Most Popular Narrative: 19% Overvalued
The leading Boeing narrative pegs fair value at $160.01, which sits well below the recent $190.21 close, so the story argues investors are already paying up for a recovery that is firmly under way but still unfinished.
The operating recovery is real but incomplete. Commercial Airplanes narrowed its operating margin from negative 5.1% to negative 2.7% on 171 deliveries versus 150. The 737 is transitioning to 47 per month from 38 a year ago, with a fourth Everett line activated in July, and management targets 52 next year.
See why 7 investors see Boeing as 19% overvalued.
Result: Fair Value of $160.01 (OVERVALUED)
Still, the narrative cracks quickly if a fresh multi billion dollar program charge hits, or if free cash flow again falls short of Boeing guidance.
Find out about the key risks to this Boeing narrative.
Another View On Boeing’s Valuation
The user narrative calls Boeing roughly 19% overvalued at a fair value of $160.01. A contrasting read comes from our DCF model, which prices the shares at $401.66 and therefore flags the current $190.21 quote as heavily undervalued.
The gap between a $160.01 narrative outcome and a $401.66 SWS DCF output reflects very different views on how reliably free cash flow can ramp while program charges, debt service and dilution remain in play. Which framework do you think better matches the way you judge risk around Boeing’s execution profile?
Look into how the SWS DCF model arrives at its fair value.
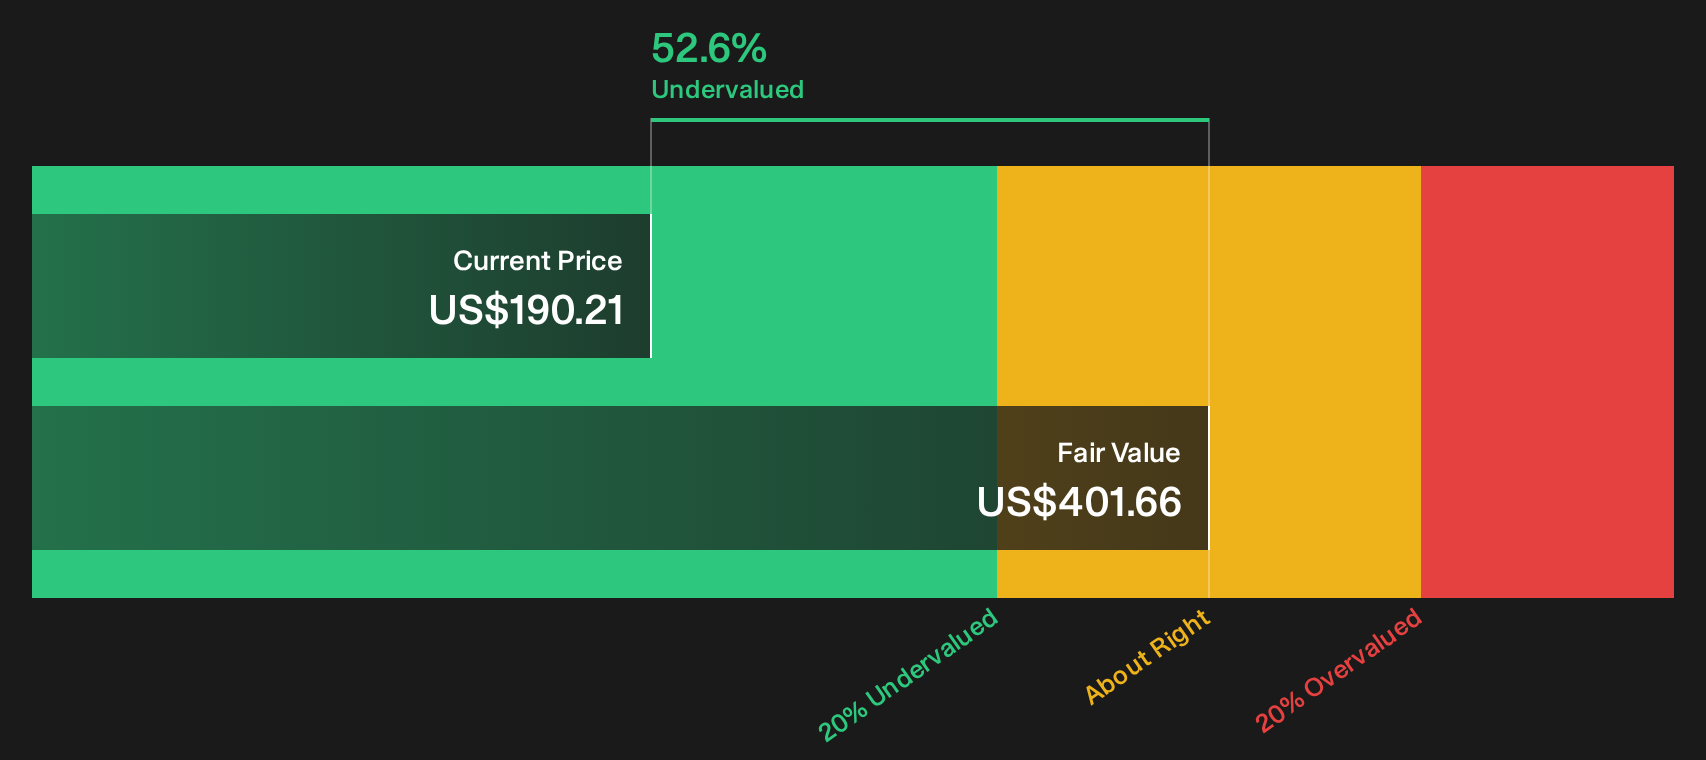
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boeing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Boeing is clearly split, so move quickly and look through the same numbers to build your own judgment. To see both the concerns and the upside case in one place, start with 4 key rewards and 2 important warning signs.
Looking for more Boeing investment ideas beyond the headline?
Do not stop with just Boeing. Use the Simply Wall Street Screener to surface fresh ideas across income, value, and balance sheet strength before the next move leaves you watching from the sidelines.
- Target reliable income streams by scanning dividend payers that appear built for durability through 8 dividend fortresses.
- Hunt for potential value opportunities by sorting companies that look attractively priced on quality and fundamentals using 33 high quality undervalued stocks.
- Prioritise financial resilience by filtering for businesses with robust balance sheets and solid metrics through list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com