


SK hynix (NasdaqGS:SKHY) Dropped, So What Is Driving Attention Now?
SK hynix (NasdaqGS:SKHY) has been in focus after Elon Musk warned that China could flood the memory market with RAM by 2028, raising fresh questions for investors watching global DRAM competition.
The recent pullback tells its own story. SK hynix’s share price has fallen 19.25% over the past week and 25.41% over the past 30 days, leaving the stock down 18.76% on a year to date share price return as investors reassess growth prospects and competitive risks despite strong Q2 results and long term supply deals.
Scan how the SK hynix selloff compares to other chip players under pressure from AI memory demand and China competition by reviewing the hand-picked 55 AI infrastructure stocks in one place.
SK hynix now trades at a steep discount to both analyst targets and some intrinsic value estimates after the selloff. Is that simply mispricing, or is it a fair caution premium on China and AI memory risks?
Preferred Multiple of 5.7x P/E: Is it justified?
On simple valuation math, SK hynix screens as cheap. At a P/E of 5.7x based on recent earnings and a last close of $136.49, the stock trades far below the pricing investors are paying for many other US chip designers and manufacturers.
P/E tells you how much investors pay for each dollar of profit. For a memory heavyweight like SK hynix, that single number reflects what the market is willing to pay for a business tied to cloud servers, AI infrastructure, mobile devices, PCs, and other hardware cycles.
The SWS data flags SK hynix as good value on this measure, since its 5.7x P/E compares against a 44.4x average for the US Semiconductor industry and 53.2x across close peers. That is a steep gap, and it points to investors assigning a heavy discount despite forecast earnings growth of about 26.9% per year and revenue growth expected at about 30.5% per year.
Compared with that sector backdrop, the valuation suggests the market is pricing in a lot more China and AI memory risk for SK hynix than for the broader chip group, even as earnings over the past year grew at a very large rate compared with the industry.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 5.7x (UNDERVALUED)
Still, the SK hynix story faces real pressure if China ramps low cost DRAM supply, or if US demand in servers and PCs cools more than expected.
Find out about the key risks to this SK hynix narrative.
Another view on SK hynix value
The DCF work presents a very different picture. Our DCF model calculates a future cash flow value of $577.86 per share versus the current $136.49 price, which appears heavily undervalued on this basis. That gap raises a blunt question for SK hynix holders: Is the model too optimistic, or is the market too fearful?
Look into how the SWS DCF model arrives at its fair value.
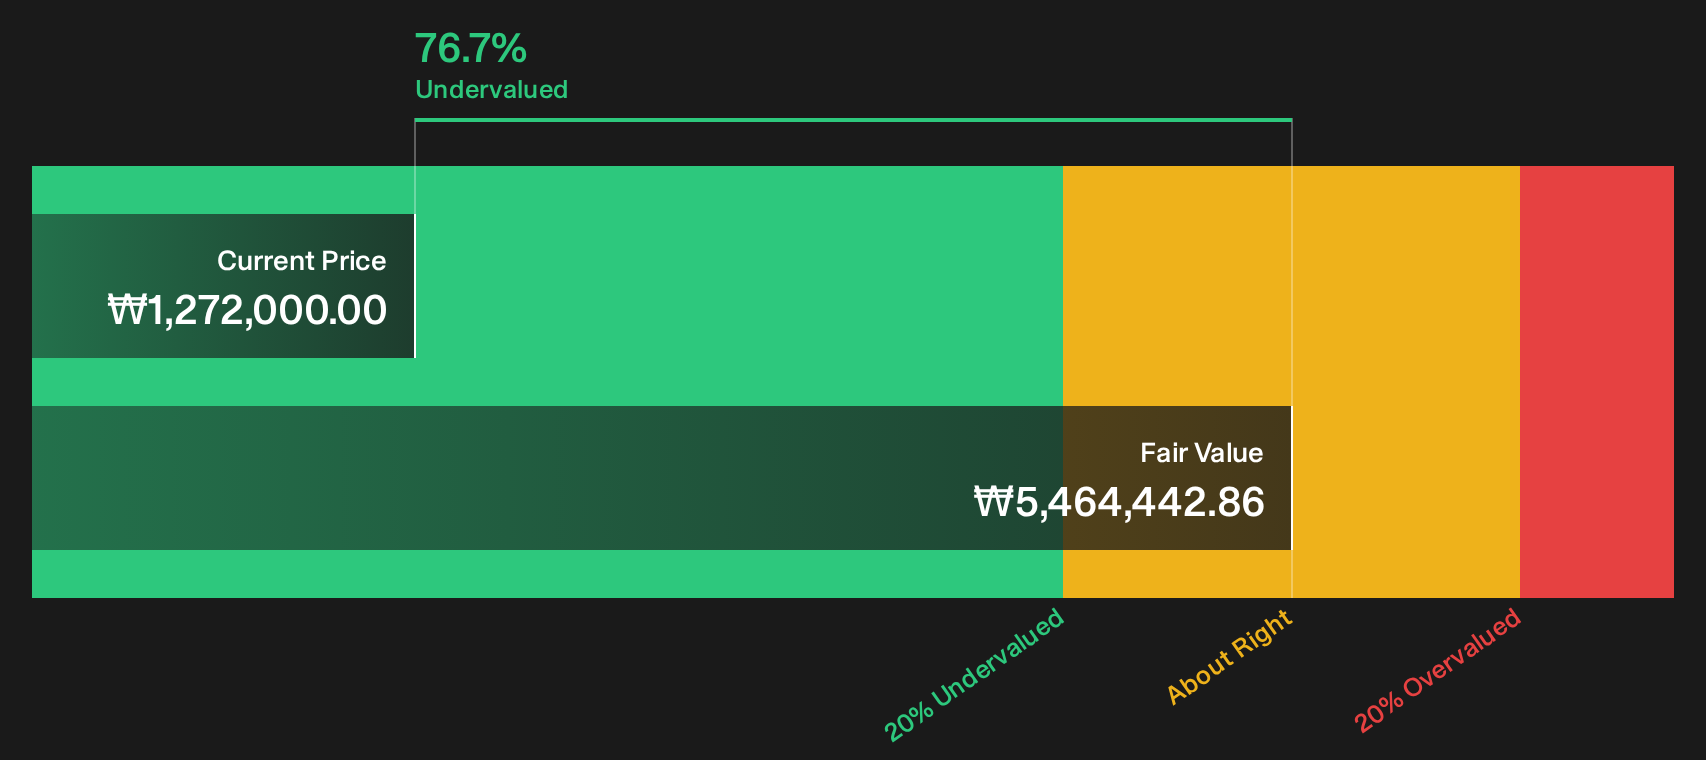
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SK hynix for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around SK hynix is clearly split, with sharp valuation signals on one side and material AI and China uncertainties on the other. Act quickly, review the numbers for yourself, then weigh up the 3 key rewards and 2 important warning signs
Looking for more SK hynix investment ideas?
Do not stop your research with SK hynix alone. Broaden your watchlist with fresh angles, because missing the next opportunity can matter more than any single valuation debate.
- Target potential bargains across sectors by scanning a curated 33 high quality undervalued stocks that filters for quality alongside compressed pricing.
- Prioritize durability and peace of mind by reviewing a 32 resilient stocks with low risk scores that screens for resilient businesses with steadier profiles.
- Hunt for under-the-radar opportunities by checking a 20 high quality undiscovered gems built to spotlight smaller companies with solid fundamentals before they hit the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com