


Is CGN Power (SEHK:1816) Cheap On Strong Operating Results And Lufeng Expansion?
Operating results put CGN Power’s recent moves in focus
CGN Power (SEHK:1816) just reported group operating results for January to September 2026, with total nuclear power generation of 189,697.73 GWh and on grid output of 176,748.88 GWh, drawing fresh attention to the stock.
The recent operating update lands after a busy few weeks for CGN Power, which also completed the registration of its Yueshan Nuclear Power joint venture for the Lufeng Unit 3 and 4 project. Against that backdrop, the share price has gathered momentum, with a 30 day share price return of 11.22% and a 90 day move of 21.61% helping lift the year to date gain to 12.16%. Longer term investors have seen a 93.05% three year total shareholder return that signals sentiment has been building rather than fading.
Compare CGN Power’s latest surge with other nuclear infrastructure plays by scanning our hand picked 16 nuclear energy infrastructure stocks, which is now shaping the sector’s next leg of growth.
CGN Power has rallied hard, yet still trades below both intrinsic estimates and analyst targets. Is that a genuine margin of safety, or a market warning label that has not faded with the latest run up?
Price-to-earnings of 14.4x for CGN Power: Is it justified?
On Simply Wall St’s numbers, CGN Power screens as good value on a discounted cash flow basis, trading about 11.6% below an intrinsic estimate of HK$3.76. However, the equity changes hands at a P/E of 14.4x that screens as expensive against several benchmarks.
The P/E ratio compares the share price with earnings per share and, for a steady cash generating utility operator like CGN Power, it gives a quick sense of how much investors are paying for each unit of profit.
For this stock, the 14.4x P/E is higher than the Asian renewable energy industry average of 14x and also above a peer group average of 10.2x. The same metric is above an estimated fair P/E of 11.3x, which points to a level the market could move towards if sentiment cools or if earnings do not keep pace with expectations.
Explore the SWS fair ratio for CGN Power.
Result: Price-to-earnings of 14.4x (OVERVALUED)
Still, tighter regulation or project delays for CGN Power’s new units could squeeze returns and challenge the idea that today’s P/E multiple offers comfort.
Find out about the key risks to this CGN Power narrative.
Another view on CGN Power’s valuation
The earnings multiple paints CGN Power as expensive, yet the SWS DCF model points the other way. On that cash flow approach, the stock sits about 11.6% below an estimated fair value of HK$3.76, which implies investors are being paid to accept some of the operating and funding risks.
For anyone weighing those mixed messages, it helps to see how the SWS DCF model is built and what would need to change for that gap to close. Look into how the SWS DCF model arrives at its fair value.
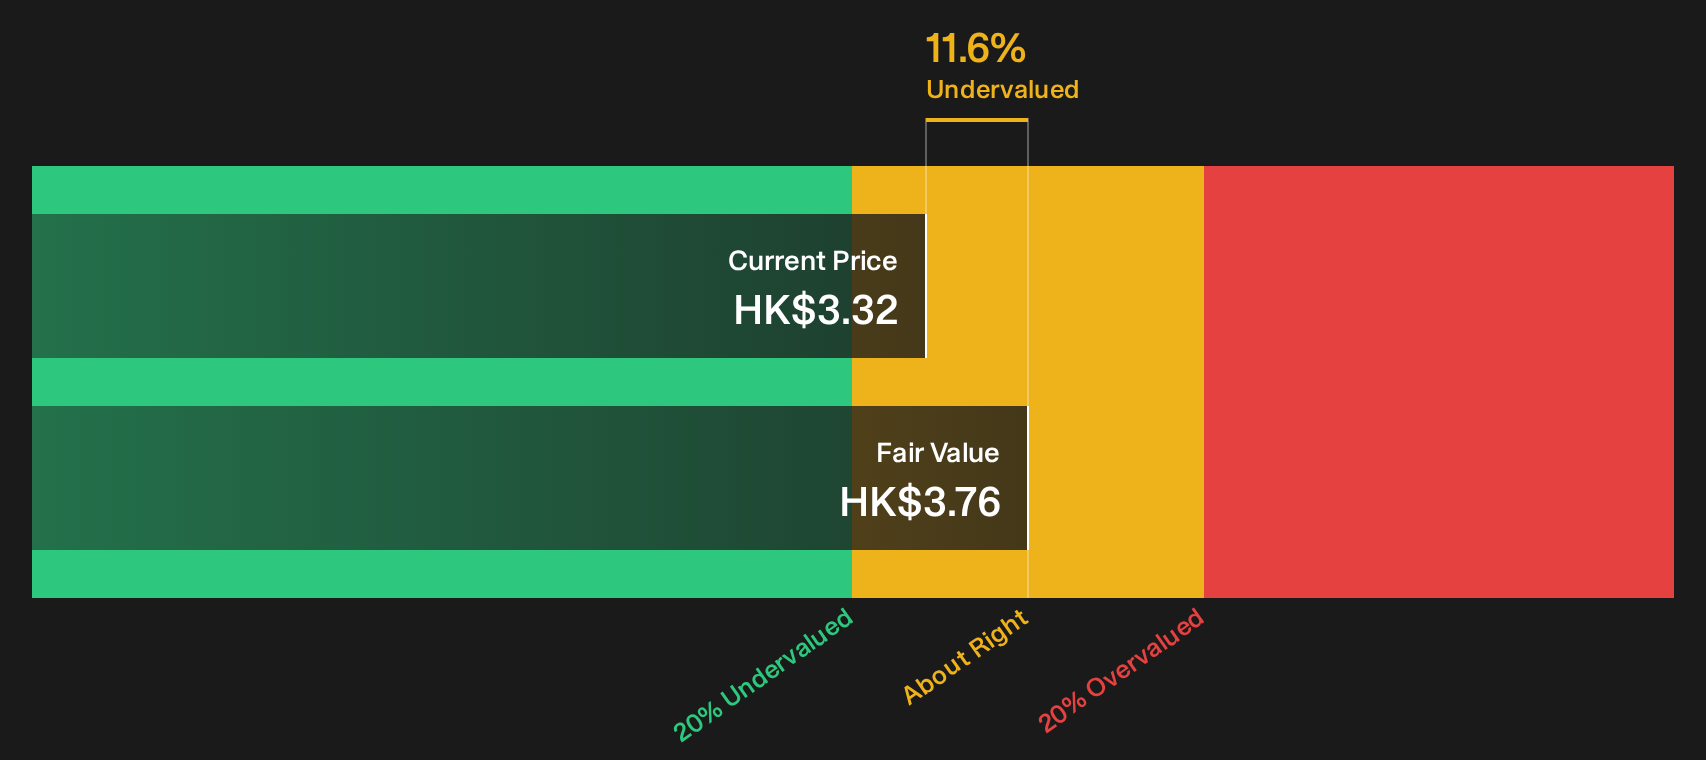
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CGN Power for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 186 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on CGN Power’s value story are clear. Move quickly, test the numbers for yourself, and weigh both sides with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond CGN Power?
CGN Power gives a focused view on nuclear energy, but your portfolio benefits when you scan a wider field of opportunities across sectors and styles.
- Target resilient cash generators with a history of rewarding shareholders by scanning companies in the 216 dividend fortresses.
- Zero in on companies that pair robust fundamentals with clean balance sheets by working through the list of solid balance sheet and fundamentals (204 results).
- Spot potential future leaders before the crowd by reviewing the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com