


How Investors May Respond To First Financial Bankshares (FFIN) Strong Q3 Earnings
- First Financial Bankshares reported third quarter 2026 net income of US$74.31 million and net interest income of US$138.51 million, alongside net charge offs of US$935,000, all for the period ended September 30, 2026.
- The combination of higher earnings per share from continuing operations and much lower net charge offs highlights how credit costs and profitability intersect for First Financial Bankshares.
- We will now examine how First Financial Bankshares' stronger earnings and low net charge offs reshape the existing investment narrative for the bank.
First Financial Bankshares Investment Narrative Recap
To own First Financial Bankshares, you need to be comfortable with a Texas focused bank that leans on conservative credit, steady profitability and only modest loan expansion. The latest quarter fits that script. Net income of US$74.31 million and net interest income of US$138.51 million point to an operation still driven by spread income and cost control rather than rapid balance sheet growth.
The short term swing factor is whether that earnings power holds up if loan growth remains modest. The sharp drop in net charge offs to US$935,000 cuts near term credit cost risk, so the bigger watchpoint now is sentiment toward a premium valued bank with slower expansion than some regional peers. The latest news does not materially change that tension.
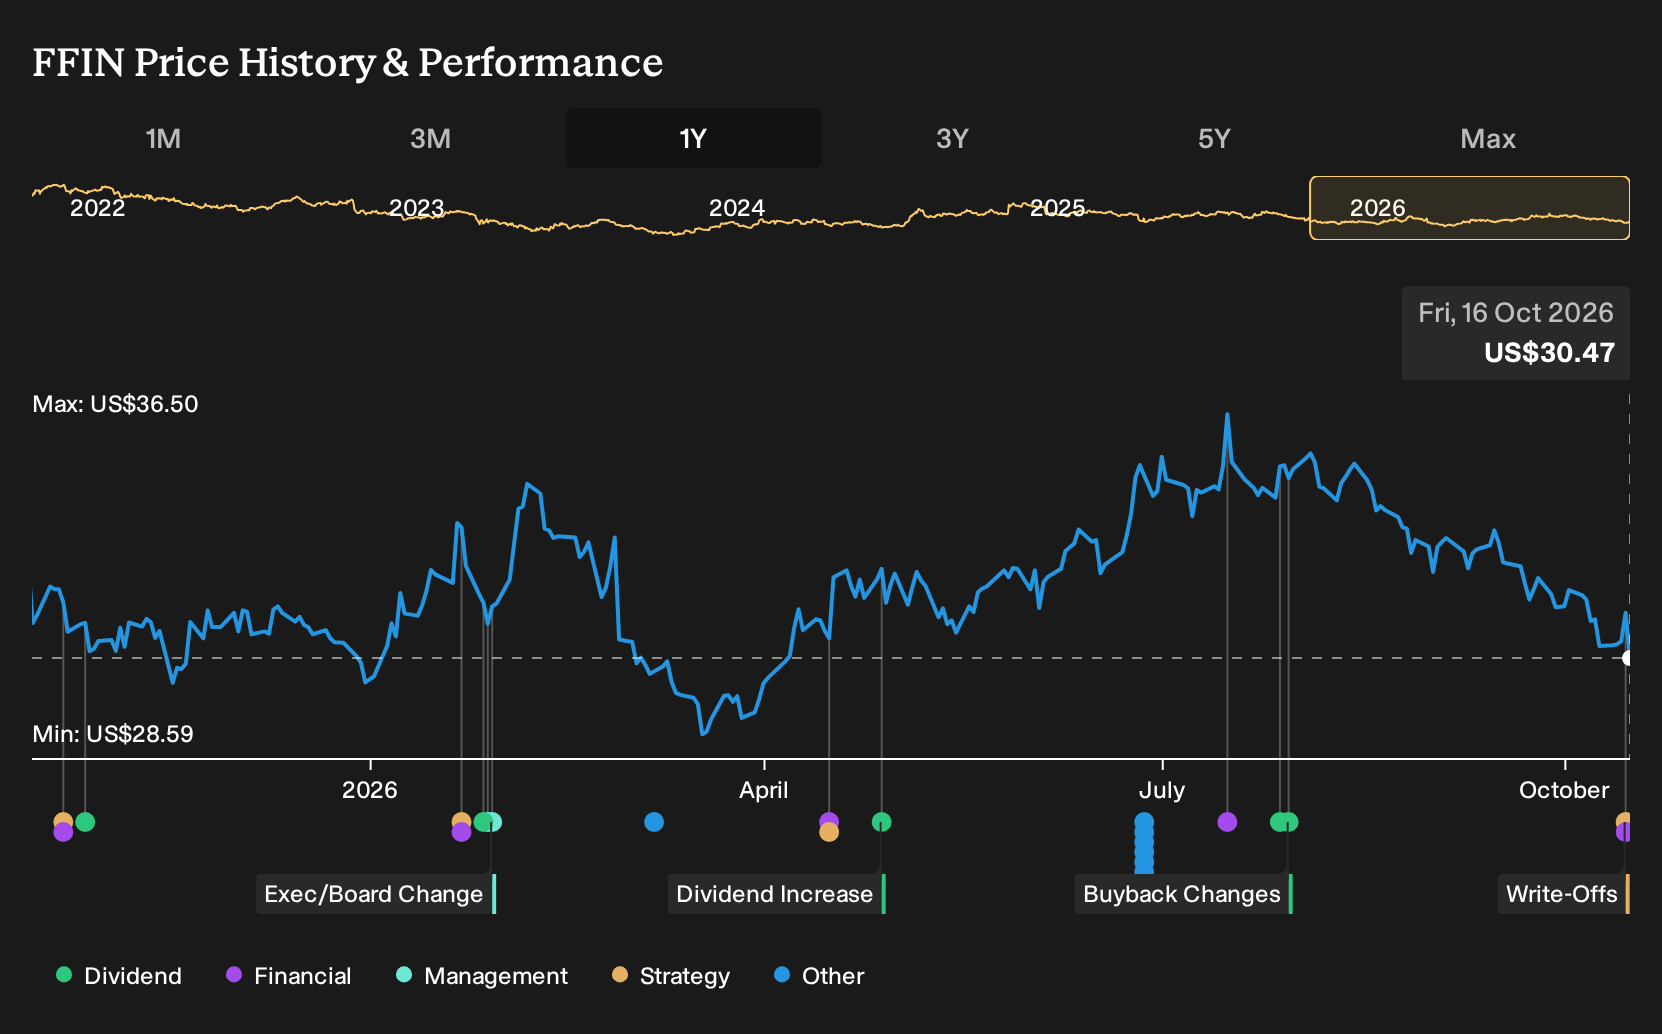
The earnings release for the third quarter of 2026 is the key announcement here. First Financial Bankshares reported higher net income year on year and basic EPS from continuing operations of US$0.52, with nine month earnings of US$217.75 million. Those figures sit alongside ongoing capital return plans, including dividends and an expanded buyback authorization.
For you as a shareholder, the catalyst is straightforward: if the bank can keep credit costs low, as implied by US$935,000 of net charge offs, and keep extracting value from its balance sheet of more than US$10 billion and its wealth management arm, then the existing premium P/E and active capital return framework may be easier for the market to accept. The risk is that modest loan growth and any sector wide pressure on bank valuations push that multiple lower despite solid reported results.
First Financial Bankshares is framed by analysts around a projection of US$875.0 million in revenue and US$356.4 million in earnings by 2029, built on an assumed 11.2% yearly revenue growth rate and an earnings increase of about US$87.4 million from US$269.0 million today.
Discover how First Financial Bankshares' fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster in a tight US$35.43 to US$36.57 band, yet those private investors clearly do not all see First Financial Bankshares the same way. You still have to weigh modest loan growth risk and sector wide multiple pressure, so exploring several alternative viewpoints is essential.
Explore another First Financial Bankshares fair value estimate, including one that suggests it could be worth just $35.43.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your First Financial Bankshares research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Financial Bankshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Financial Bankshares' overall financial health at a glance.
Looking For More Investment Ideas Beyond First Financial Bankshares?
If this update on First Financial Bankshares sharpened your thinking, use that momentum to scan a wider field of potential opportunities with the Simply Wall St Screener. You can filter for the traits that matter most to you, then compare how other businesses stack up against what you have just seen here.
- If capital preservation and steadier profiles matter most to you, start with a 32 resilient stocks with low risk scores that screens for resilience first.
- If value is your priority, broaden your watchlist with a 33 high quality undervalued stocks that highlights companies combining stronger balance sheets with more appealing P/E levels.
- If income is central to your approach, focus on cash returning businesses through a 8 dividend fortresses that filters for higher yield and consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com