


Northern Oil And Gas Stock Gets Buy Rating As Earnings Outlook Improves
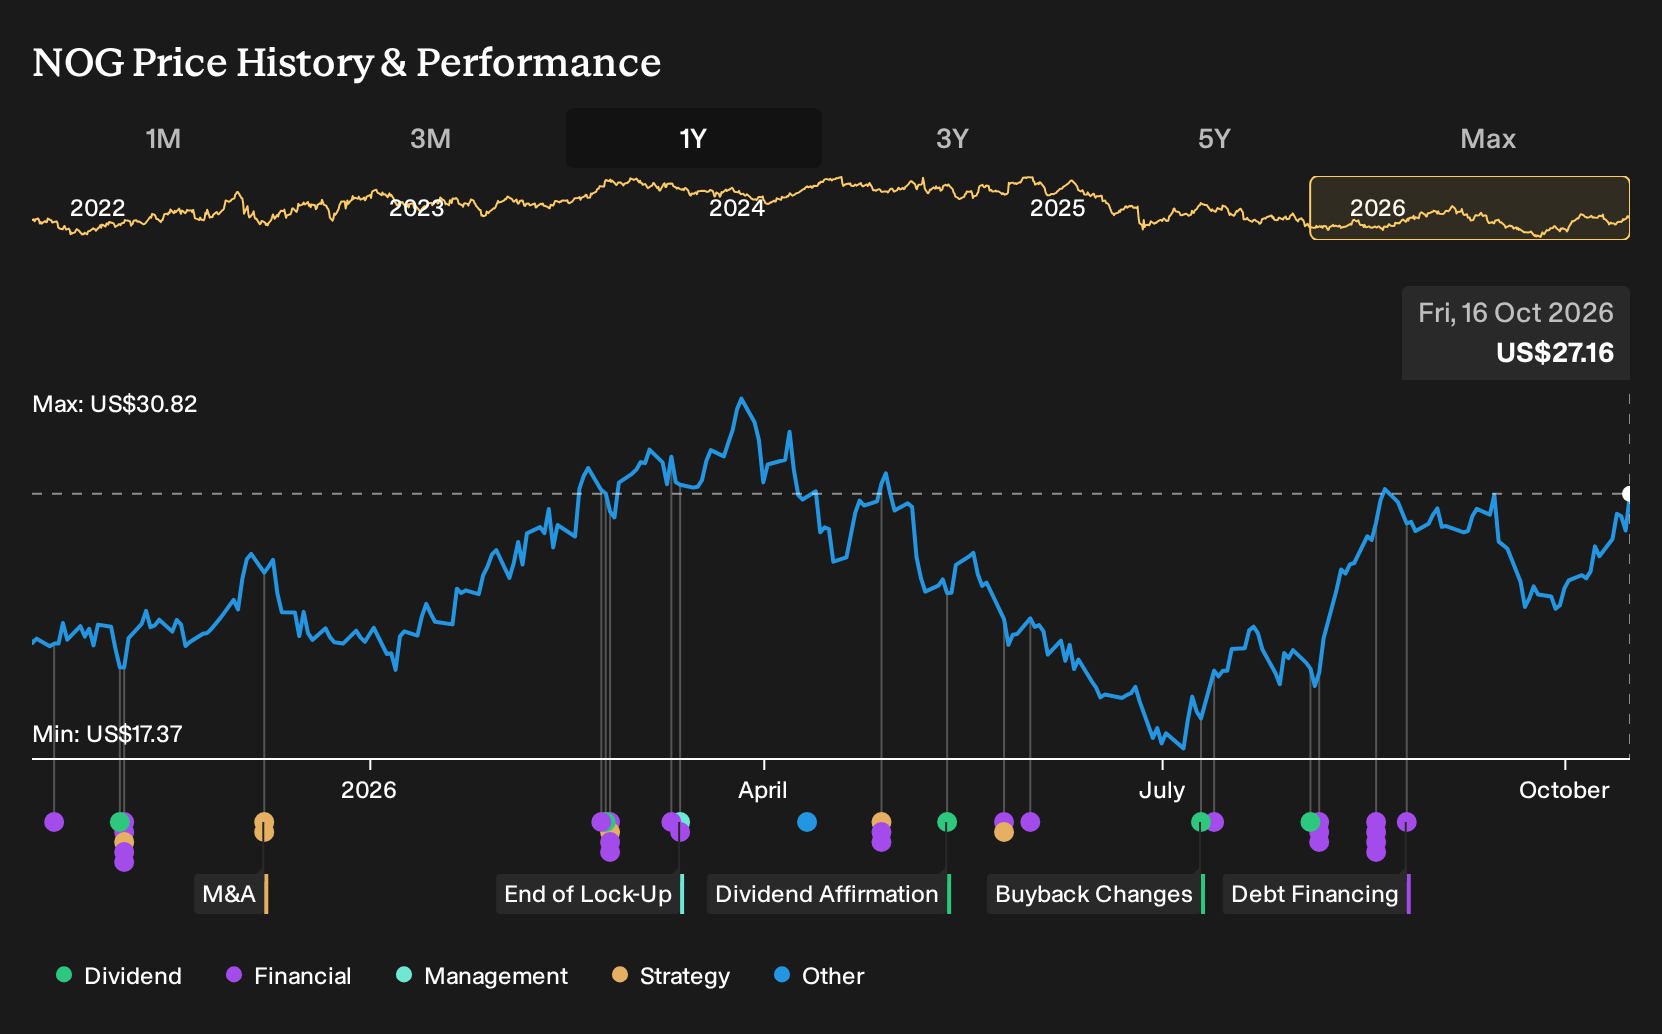
- Northern Oil and Gas completed a buyback program announced in July 2024, retiring 6,656,391 shares, or 6.51% of its equity, for US$172.66 million, including 667,989 shares purchased in the quarter ended September 30, 2026.
- The finished repurchase reduces share count while Northern Oil and Gas is being framed as a value stock with a P/E of 7.22 and a P/B of 1.01. This may sharpen investor focus on how cash returns interact with its non operated, multi basin growth model.
- The focus now turns to how Northern Oil and Gas' completed buyback might influence the broader investment narrative around value and capital allocation.
Stack your watchlist with more potential value stories by comparing Northern Oil and Gas to our curated set of 33 high quality undervalued stocks.
Northern Oil and Gas Investment Narrative Recap
To own Northern Oil and Gas, you need to be comfortable with a non operated, multi basin model that leans on acquiring long dated, lower decline assets while carrying meaningful debt and non cash accounting swings. The core near term catalyst is execution on that portfolio, keeping production, costs and free cash flow aligned with acquisition spending.
The completed US$172.66 million buyback slightly tightens the share count, but it does not change the main operational swing factors. The biggest immediate risk remains pressure on reported earnings from impairments, hedge marks and interest costs, which can mask underlying cash generation and limit flexibility for future dividends or further repurchases.
The most relevant recent development for this buyback conversation is the finished repurchase of 6,656,391 shares, equal to 6.51% of Northern Oil and Gas equity, under the program announced in July 2024. That is a sizable cash outlay for a company that already relies on higher cost notes and has interest payments that are not well covered by current earnings.
For investors, this matters because capital returns now sit alongside bond coupons, maintenance spending and new deals, competing for the same cash pool. If operating assets deliver the steady volumes and margins associated with the Utica, Duvernay and ground game portfolio, the reduced share count can increase the impact of results on a per share basis. However, any squeeze on free cash flow could limit the company’s flexibility relatively quickly.
What The Analyst Scenario Implies For Northern Oil and Gas
Analysts sketch out a version of Northern Oil and Gas where higher margins and steadier output do most of the heavy lifting. The forecasts assume revenue expands by 8.2% a year over the next three years, with profit margins moving from a loss position today to 19.6% by 2029. That path would take earnings from a loss of US$486.0 million today to a profit of US$498.5 million by about October 2029, a swing of roughly US$985 million.
Northern Oil and Gas' narrative projects revenue of US$2.5b and earnings of US$498.5 million by 2029. This assumes 8.2% yearly revenue growth and an earnings swing of about US$985 million from a loss of US$486.0 million today.
Under that consensus view, the stock screens on a P/E of 10x those 2029 earnings, using a discount rate close to 7.9% to bring that scenario back to today. That multiple sits below the current 12.3x P/E quoted for the wider US oil and gas group. This is one reason some investors frame Northern Oil and Gas as a value idea rather than a pure growth story.
There is still a wide band of opinion. The most optimistic analysts cluster around a US$38.00 target, while the most cautious sit at US$25.00, against a current share price of US$23.83 as of mid October 2026. That spread reflects different views on how reliably the non operated, multi basin model can translate into the US$2.5b revenue and US$498.5 million earnings outcome by 2029, and how much weight to place on leverage, impairments and hedge marks along the way.
Uncover why Northern Oil and Gas' fair value indicates a 12% potential upside to its current price, a discount that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view leans heavily on regulatory and decarbonization risk for Northern Oil and Gas. Under that frame, the most bearish analysts tied their US$25.00 target to slower revenue assumptions, roughly US$2.3b by 2029 and earnings of US$622.8 million, set before this buyback update. Use that gap in outlooks to pressure test your own thesis.
Explore 5 other Northern Oil and Gas fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Northern Oil and Gas research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northern Oil and Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Oil and Gas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Northern Oil and Gas?
If the Northern Oil and Gas story has you thinking about valuation, balance sheets and risk, it can help to widen the net and compare it with other listed businesses that share similar traits or offer a different mix of income and downside protection.
- For investors hunting for mispriced opportunities with quality fundamentals, start by scanning our curated set of 33 high quality undervalued stocks that combine strong cash generation with relatively modest valuations.
- If capital preservation and financial strength sit at the top of your checklist, filter the market using a list of solid balance sheet and fundamentals (25 results) to find companies with sturdier debt profiles and healthier coverage ratios.
- Income seekers who prioritize steady payouts over headline growth can focus on a 8 dividend fortresses that targets higher yielding stocks with more robust underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com