


Mondi (LSE:MNDI) Q3 Trading Statement Puts Its Undervalued Narrative To The Test
Mondi (LSE:MNDI) has moved into focus after its Q3 2026 trading statement, with underlying EBITDA of €196 million supported by higher selling prices and fresh increases in paper grades to help offset rising energy-related costs.
Recent trading updates have not stopped Mondi’s share price from losing ground this year, with a year-to-date share price return of down 17.63% and a 1-month share price return of down 9.10%. The 1-year total shareholder return of down 6.98% and 5-year total shareholder return of down 48.66% suggest momentum has been fading rather than building, despite the Q3 2026 trading statement and the upcoming sales and trading call on 15 October 2026.
Scan how Mondi’s recent setbacks compare with other packaging and materials stocks by checking out our hand picked 7 high quality undervalued stocks, which also pair earnings power with balance sheet strength.
Mondi’s share price slide and Q3 resilience now pull in opposite directions. Does that mix still tilt the risk reward balance toward buyers, or has the recent move already priced in the update?
Most Popular Narrative: 11% Undervalued
Mondi’s most followed valuation storyline points to a fair value of £8.47 against a last close of £7.57, so the narrative leans toward upside potential while still stressing execution risk around earnings and margins.
Successful capacity expansion projects (Duino, Steti, Kuopio, Swiecie) are beginning to ramp up, with incremental EBITDA expected to grow in 2025 and into 2026 as these new assets reach full utilization, directly supporting future earnings and cash flow growth.
Heightened demand for recyclable and sustainable packaging (corrugated, paper bags) from both shifting consumer preferences and regulatory pressures is increasing Mondi's addressable market, positioning its core businesses for long-term revenue expansion and potential pricing power.
See why 28 investors see Mondi as 11% undervalued.
Result: Fair Value of £8.47 (UNDERVALUED)
Still, weak demand in key packaging grades and higher structural costs could keep Mondi’s margins under pressure and could challenge the optimistic analyst narrative.
Find out about the key risks to this Mondi narrative.
Another View: What Mondi’s Cash Flows Say
The analyst narrative paints Mondi as 11% undervalued with a fair value of £8.47, yet the SWS DCF model points the other way. On future cash flows, the estimate sits at £3.98, which makes the current £7.57 quote look expensive and narrows the margin for error if the upbeat forecasts slip.
That gap forces a simple question for anyone following Mondi. Are analyst earnings assumptions too generous, or is the cash flow model too strict for a business still rebuilding profitability after recent losses?
Look into how the SWS DCF model arrives at its fair value.
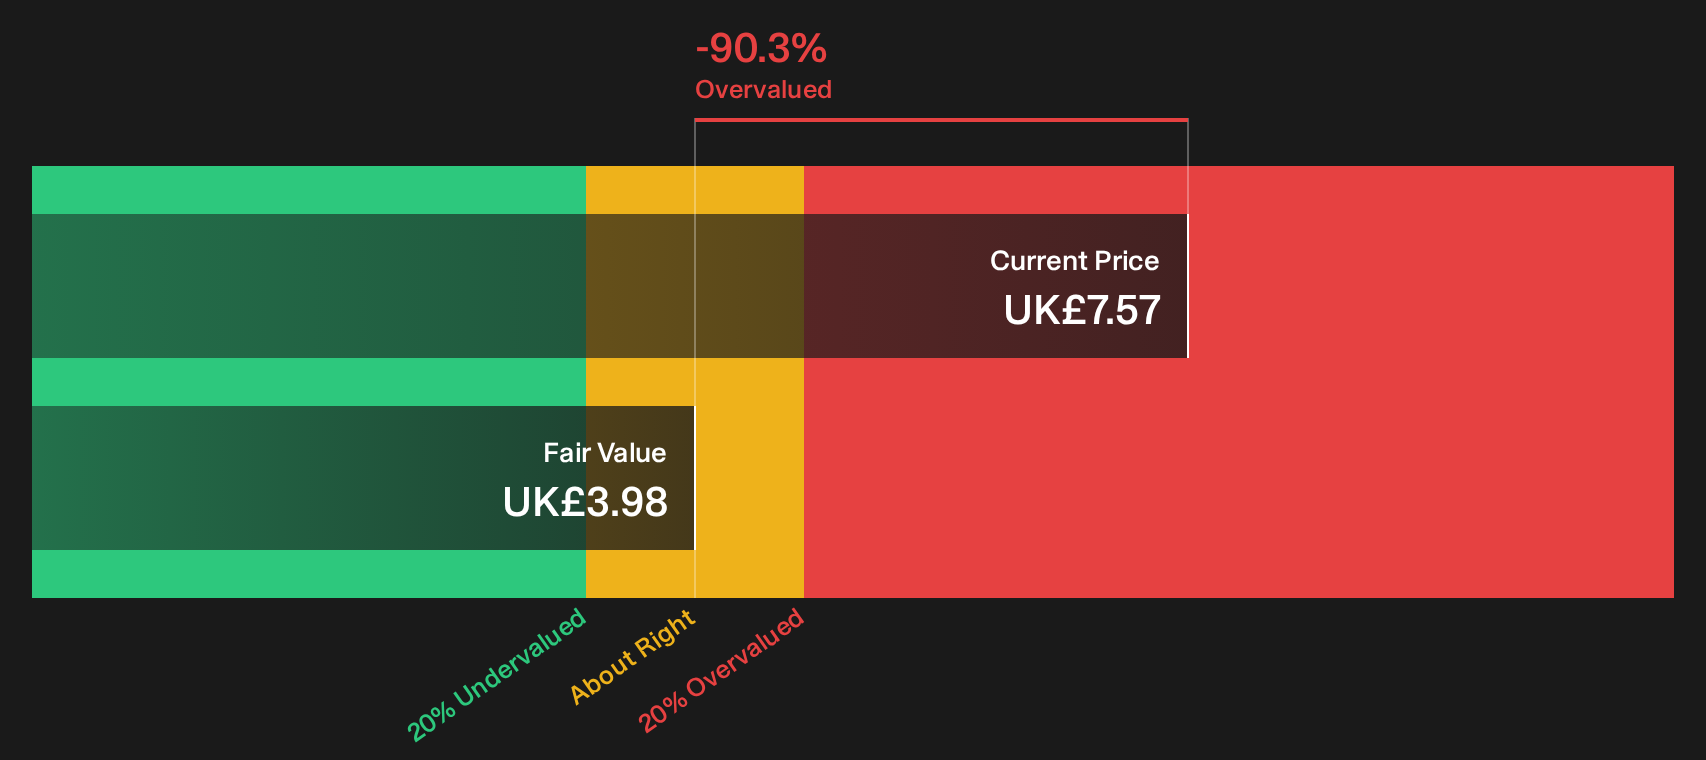
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mondi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Mondi feels familiar, consider taking action while sentiment is still split and weigh both sides of the data yourself with 2 key rewards and 1 important warning sign.
Looking for more ideas beyond Mondi?
Do not stop with Mondi alone. Broaden your watchlist with other potential opportunities that fit your risk comfort and income goals using focused stock screens.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (9 results) tailored for financially robust businesses.
- Hunt for mispriced quality by reviewing the 5 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Strengthen your income stream by assessing the 2 dividend fortresses built around higher yielding companies with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com