


Tokai Rika (TSE:6995) Draws Fresh DCF Interest On Whether It Is Still A Bargain
DCF-driven interest around Tokai Rika
Fresh DCF work around Tokai Rika (TSE:6995) has highlighted the gap between intrinsic value and the current share price, particularly in light of expectations for future free cash flow.
That valuation debate, together with a single flagged warning sign in the thesis, has brought Tokai Rika back under the microscope for investors who are comparing long-term cash generation with today’s market pricing.
Recent trading has been choppy for Tokai Rika, with a 1-day share price return of 2.78% and 7-day share price gain of 3.80%. However, a 30-day share price return that declined 2.79% hints at cooling short-term momentum, even as the 1-year total shareholder return of 25.01% and 5-year total shareholder return of 134.20% keep the longer-term story in positive territory and frame the current DCF debate around whether the latest ¥3,140 share price fully reflects that track record.
Scan other potential deep value ideas alongside Tokai Rika by comparing it with our hand picked 13 high quality undervalued stocks, which also pair solid cash flow with disciplined balance sheets.
Tokai Rika looks like a solid auto parts business with a long record of shareholder returns, yet the share price near ¥3,140 after a mixed month raises a clearer question: does the current valuation still treat it as a bargain, or as a premium story built on past success?
Price-to-earnings of 9.3x: Is it justified for Tokai Rika?
On a simple earnings yardstick, Tokai Rika trades on a P/E of 9.3x, which keeps the stock roughly in line with the wider Japanese auto components group but slightly above its own estimated fair level.
The P/E ratio links what investors are willing to pay today with each unit of current earnings. For a parts manufacturer like Tokai Rika, this measure is often used as a shorthand for how the market weighs future profit resilience against the realities of a cyclical industry and relatively modest forecast growth.
Here the picture is mixed. The shares are described as good value against both the Japanese auto components industry average P/E of 9.4x and a much higher 44.5x peer average, which points to restrained expectations in the current price. At the same time, Tokai Rika is flagged as expensive relative to an estimated fair P/E of 9.1x, suggesting the multiple could drift toward that level if sentiment cools and the market leans more heavily on slow forecast earnings growth of around 2.7% to 2.66% per year.
Explore the SWS fair ratio for Tokai Rika.
Result: Price-to-earnings of 9.3x (ABOUT RIGHT)
Still, the revenue and net income growth rates near 2.8% and 2.7%, together with a slight premium to the ¥3,100 price target, could limit near term enthusiasm for Tokai Rika.
Find out about the key risks to this Tokai Rika narrative.
Another view on Tokai Rika’s value
The earlier focus sat on Tokai Rika’s 9.3x P/E ratio, which looks roughly in step with the Japanese auto components group and only slightly above a 9.1x fair ratio. A very different message comes from the SWS DCF model, which sees the shares at ¥3,140 trading below an estimated future cash flow value of ¥6,101.23. That gap raises a simple question for investors: Is the earnings multiple missing something that long term cash projections are picking up?
Our DCF work is fully laid out for Tokai Rika, so you can see exactly how those cash flow assumptions build up to that estimated value. Look into how the SWS DCF model arrives at its fair value.
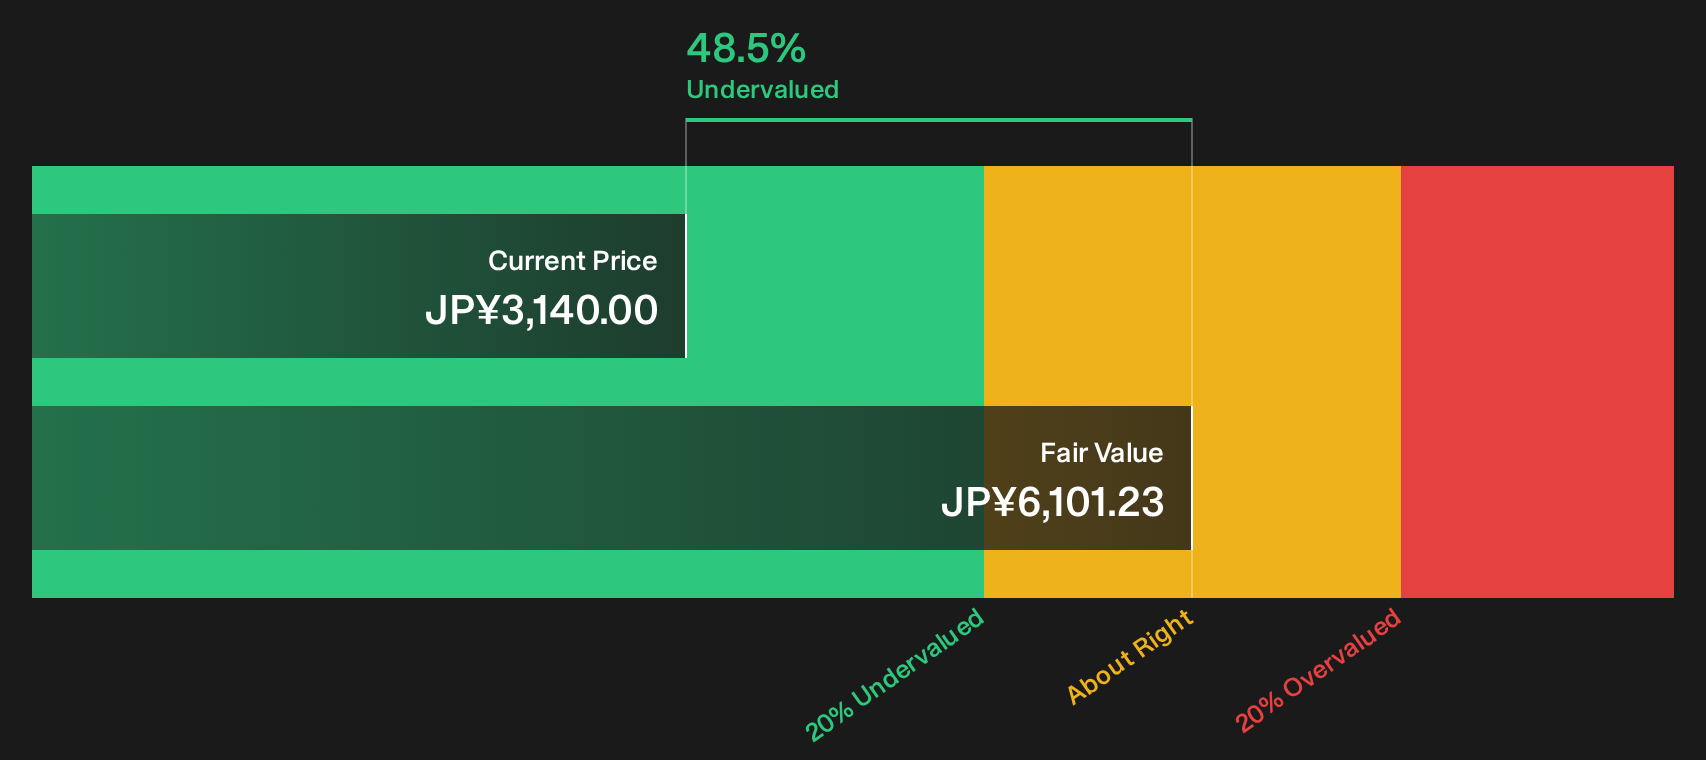
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tokai Rika for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
So does Tokai Rika still feel like a straightforward DCF story or something more complicated? Act quickly, review the risks and rewards, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Tokai Rika?
If Tokai Rika has sharpened your focus on value, do not stop here. Broader opportunity often appears where fewer investors are currently looking.
- Target dependable cash machines by scanning a 29 dividend fortresses that combines income potential with disciplined payout histories.
- Hunt for mispriced quality through a 73 high quality undiscovered gems that highlights strong fundamentals hiding outside the usual watchlists.
- Stack resilience in your portfolio by screening a 23 resilient stocks with low risk scores built around balance sheet strength and lower historical risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com