


What Barclays Doubters Missed
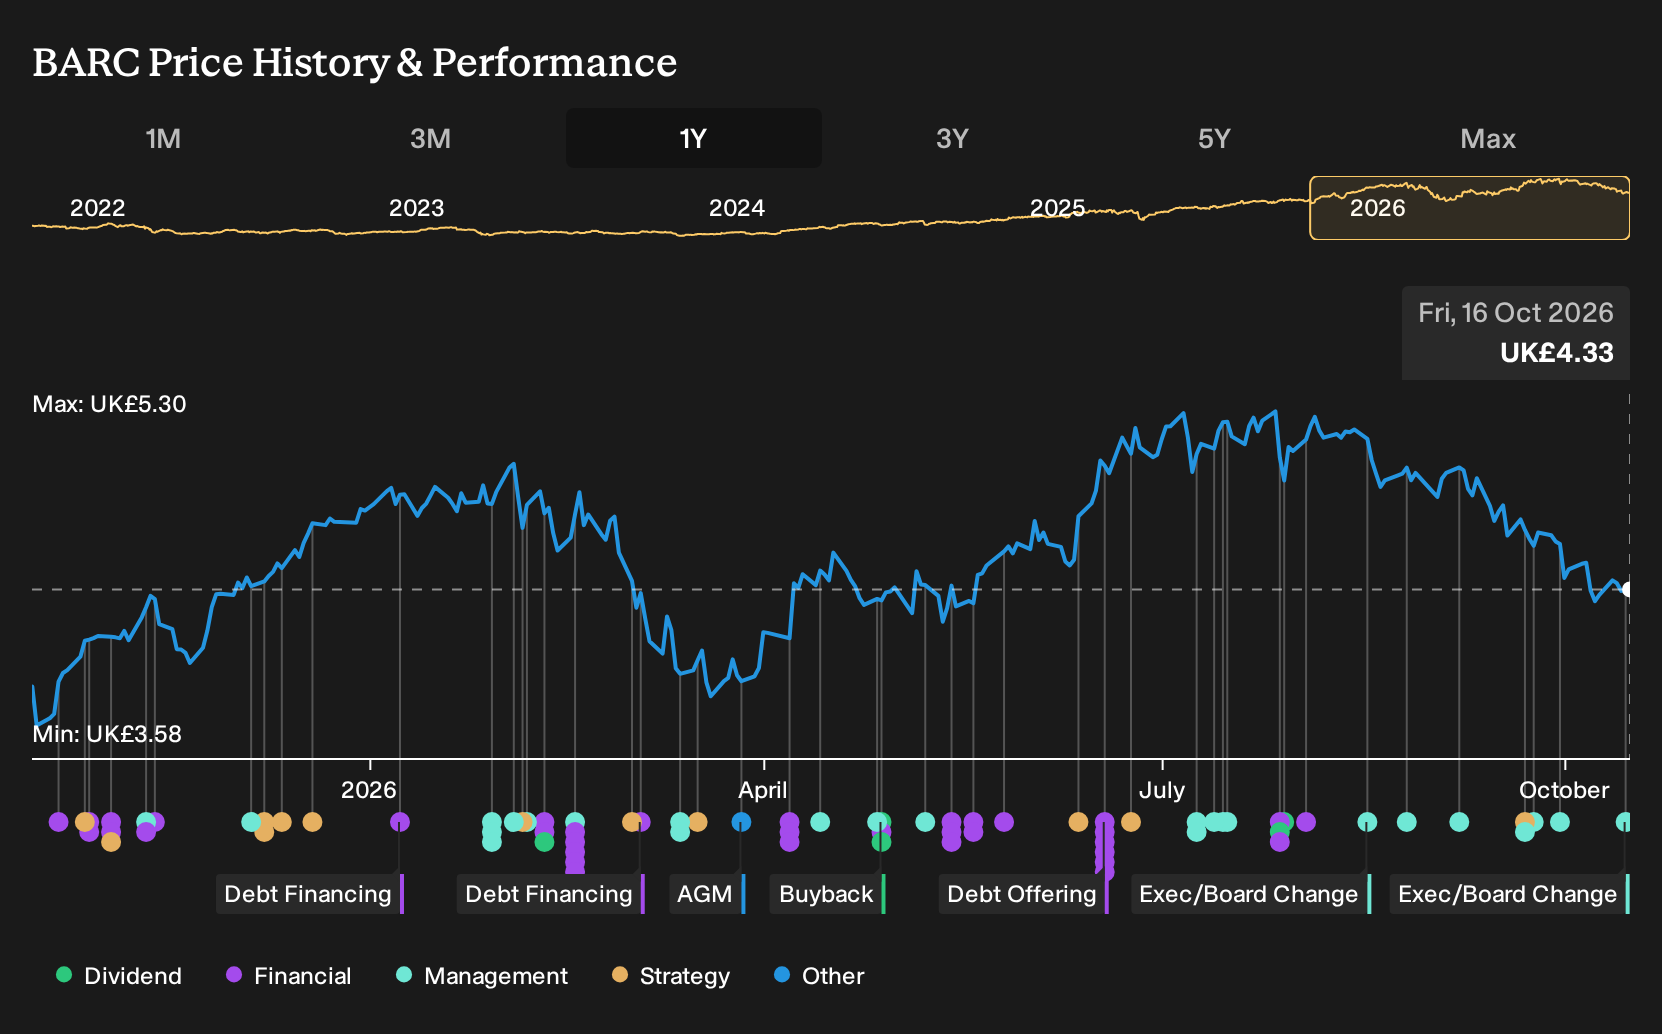
If you had been weighing up Barclays a year ago, the outcome now probably looks deceptively simple. Holding Barclays over the past year would have returned 23.7%, including dividends. Back on 16 October 2025, though, early buyers were trying to balance upbeat talk about digital banking, Tesco Bank and efficiency gains against warnings on legacy systems, fintech pressure and regulatory costs. If that decision were in front of you again today, which side of that trade-off would carry more weight?
The easy part of this move is behind Barclays. Zero in on 7 high quality undervalued stocks for companies trading below our estimates.
The Two Barclays Narratives Investors Had To Weigh
The shares cost £3.79 at the start of the period, and you had to decide which Barclays story sounded more convincing.
On the upbeat side, one narrative put Fair Value at £4.11. This was the rough price implied if its assumptions played out, built on digital banking, fintech partnerships and the Tesco Bank deal helping revenue grow 6.4% with a 23.4% profit margin and a future P/E of 9.4x.
The more cautious script pointed to a Fair Value of £2.30, with legacy IT, regulatory scrutiny and fintech competition seen as serious threats. It also argued that prolonged low interest rates could compress net interest income and limit sustainable earnings growth.
What The Results Changed In The Barclays Debate
Barclays delivered Q2 2026 revenue of £7,767m and net income of £2,259m, both higher than Q2 2025, with net margin improving from 24.7% to 29.1%. That combination of higher sales and fatter profitability supports the view that expected stronger returns from digital banking and efficiency work, even with the fraud related impairment earlier in 2026 challenging risk control.
The episode puts a spotlight on one key assumption. When a thesis relies on efficiency and technology, it is important to check whether revenue, net income and margin are all moving together in reported results rather than relying on cost cutting headlines alone.
What You Are Paying For In Barclays Today
Today Barclays trades at £4.33, and the selected Narrative places its Fair Value above that level. The argument leans heavily on a low P/B ratio combined with a roughly 10x P/E and ongoing buybacks.
The key question for you is whether Barclays can keep earning returns on equity around 10% while steadily improving efficiency and culture.
"The bank continues to generate double-digit returns on equity, a level of profitability that would often justify a valuation closer to, or above, book value. While Barclays is not producing elite returns, the combination of a price-to-book ratio around 0.8 and returns on equity in the 10% range appears somewhat contradictory."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond Barclays For Context
Barclays offers one version of large bank digital execution. That is useful, but it is only one template.
Another heavyweight lender is pushing harder into AI tools and app based services. Its focus is deepening relationships instead of mainly trimming branch costs.
This institution also leans on a broad deposit base. It aims to draw more fee and wealth income from customers already on the books.
If that strategy succeeds, its earnings mix could diverge from a traditional UK focused model. That contrast might sharpen how you judge Barclays own path.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 31% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com