


HubSpot (HUBS) Could Be 7% Undervalued After AI Financing Fears Hit Tech
Why HubSpot is back in focus after legal chief exit and tech sector pressure
HubSpot (HUBS) has drawn fresh attention after two overlapping events: the Chief Legal Officer plans to resign, and a broader tech pullback tied to AI financing concerns has pressured the stock.
Over the past year, momentum in HubSpot has clearly faded, with the share price down 39.58% year to date and the 1-year total shareholder return falling 47.13%. At the same time, a 6.86% 1-month share price gain hints at short-term buyers testing whether recent sector-wide AI and rate worries have been overdone.
Scan the high-growth tech space under similar pressure and compare HubSpot with our hand-picked 33 high quality undervalued stocks that may be pricing in those AI and rate fears differently.
The share price reset and a roughly 7% gap to the average analyst target tell only part of the story. Does HubSpot’s much larger implied intrinsic discount indicate mispricing, or does it reflect real risk that estimates miss?
Most Popular Narrative: 7% Undervalued
Against the last close at $230.94, the most followed narrative pegs HubSpot’s fair value at $249.37, pricing in an 8.64% discount rate and a long runway for its customer platform and AI tools.
Rapid adoption and expansion of AI-based functionality such as Customer Agent, Prospecting Agent, and connectors to leading LLMs are driving higher customer engagement, sticky workflows, and early-stage monetization opportunities (especially via credit-based AI features). This is setting the stage for stronger net dollar retention and potentially higher net margins in 2026 and beyond.
See why 66 investors see HubSpot as 7% undervalued.
Result: Fair Value of $249.37 (UNDERVALUED)
Still, if HubSpot’s AI monetization or international expansion stumble, the current 7% discount to analyst targets could quickly look less compelling.
Find out about the key risks to this HubSpot narrative.
Another View: HubSpot looks expensive on earnings multiples
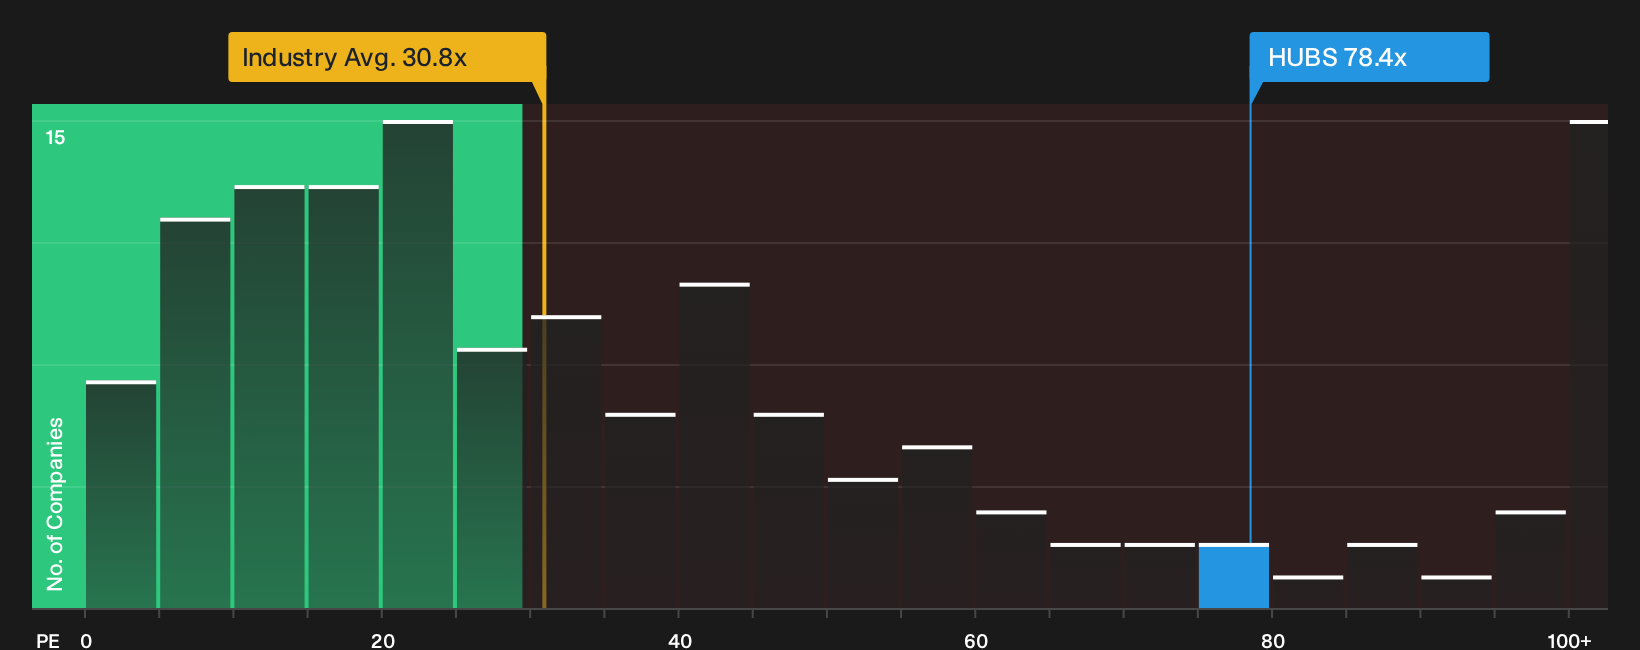
That 7% gap to the analyst fair value and a large SWS DCF upside are only one side of the story. On a simple P/E lens, HubSpot trades at 78.4x compared with 30.8x for the US Software industry, 56.1x for peers, and a fair ratio of 64.9x that the market could move toward over time. This kind of premium can reward patience if the bullish narrative plays out, but it also leaves less room for error if growth or margins fall short of expectations.
For a closer look at how these earnings multiples stack up, and what they imply for risk versus opportunity, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on HubSpot can be useful if you use them as a prompt to test the numbers yourself and move quickly rather than react later, especially with both 1 or more risks and 1 or more rewards now on the table through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HubSpot?
If HubSpot has you thinking more critically about price, quality, and risk, do not stop here. The next decision you make could move your portfolio meaningfully.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that focus on financial strength first.
- Hunt for potential mispriced opportunities by reviewing a curated 33 high quality undervalued stocks that pair quality metrics with attractive valuations.
- Build a cash flow backbone in your holdings by filtering for income ideas across our 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com