


Ocular Therapeutix (OCUL) Stock May Be Fully Priced Given Its Sales Base
Ocular Therapeutix has given investors a volatile ride, and the recent share-price swings raise a straightforward question: Is the current valuation of the stock justified by the sales the business is generating today and what it can realistically sustain over time?
- Over the past 3 years the stock has gained about 192.3%, which puts real pressure on the question of whether the present share price can be backed up by the company’s sales performance.
- The business model depends heavily on turning eye-care drug development into commercial products, which can shape future revenue scale, margin potential, and how much sales growth the current price already assumes.
- The analysts covering Ocular Therapeutix have run their own numbers. See what analysts think Ocular Therapeutix's shares could be worth.
The issue now is whether the recent share price around US$6.87 can be squared with Ocular Therapeutix's sales when judged against the Fair Ratio benchmark.
If you are weighing whether Ocular Therapeutix's recent swings line up with its sales, it can help to compare it with other 33 high quality undervalued stocks.
Is Ocular Therapeutix Getting Expensive on Sales?
P/S works better than P/E for Ocular Therapeutix because the business is still loss making, so revenue offers the cleanest yardstick for what the market is paying for the current sales base.
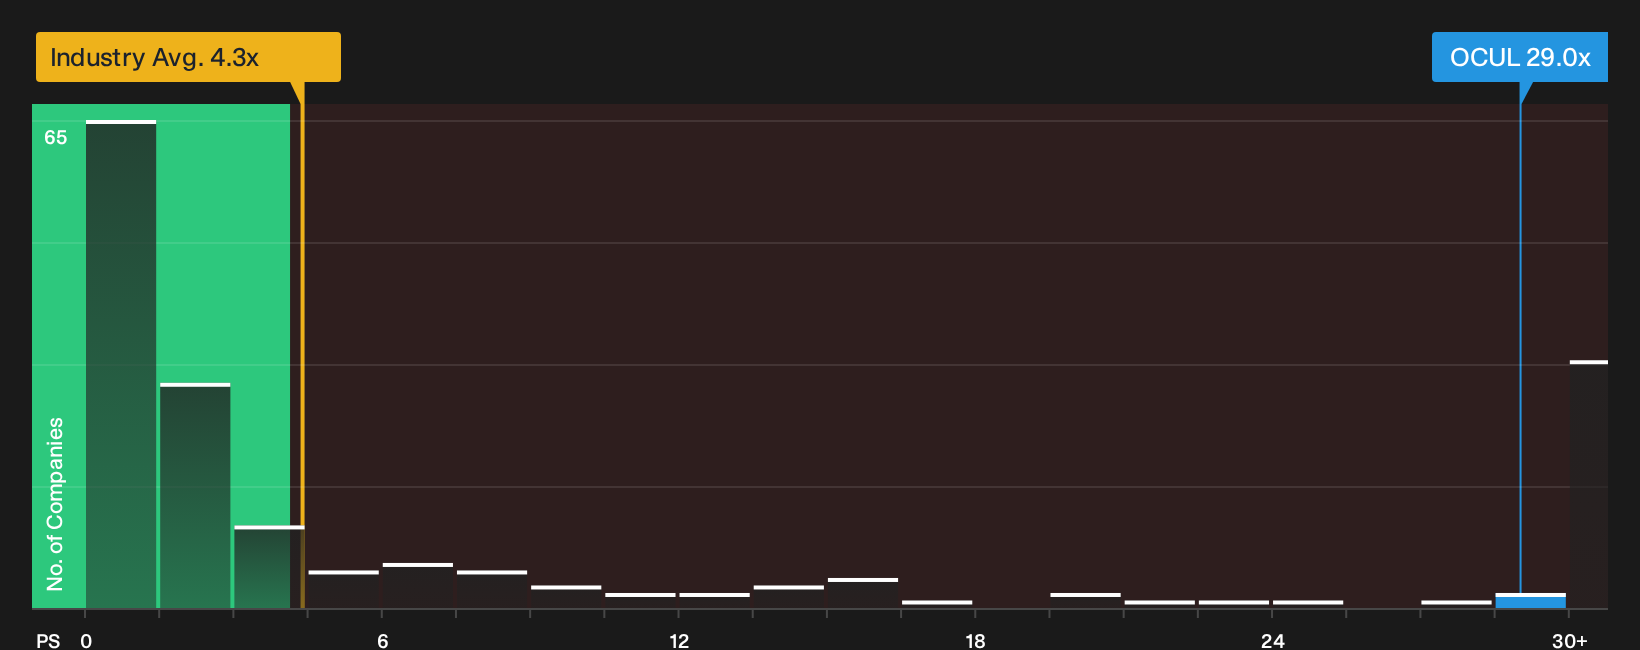
The stock trades on a P/S of about 29.0x, while the broader Pharmaceuticals industry sits nearer 4.3x and the peer group average is around 5.3x. That is a steep mark up on each dollar of revenue. The Fair Ratio model, which adjusts for growth potential, margins, size and risk, flags that this premium screens as overvalued on its framework rather than reasonable versus the underlying sales profile.
The gap is so wide that the model is effectively warning that losses, execution risk and the quality of revenue assumptions are doing most of the work in that valuation, not today’s reported selling line. Anyone considering Ocular Therapeutix needs to decide whether the pipeline, commercial strategy and balance sheet comfort level justify paying such a rich P/S against both sector norms and this tailored benchmark. Explore the numbers behind Ocular Therapeutix's P/S valuation.
The Ocular Therapeutix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle on Ocular Therapeutix leaves off. They spell out which combinations of future growth, profitability and earnings would need to hold for the stock to be worth materially more or less than its current price. Each one treats fair value as a thesis about how the business might progress over time, so you can watch how that idea holds up as new information arrives on the Community page.
One of the top community narratives on Ocular Therapeutix: 75% undervalued
"Heavy dependence on a single pipeline asset exposes Ocular Therapeutix to clinical, regulatory, and competitive risks that threaten margins, revenue, and sustainable growth…"
Discover why this Narrative puts Ocular Therapeutix at 75% undervalued.
One more Ocular Therapeutix check that sits outside the valuation ratios
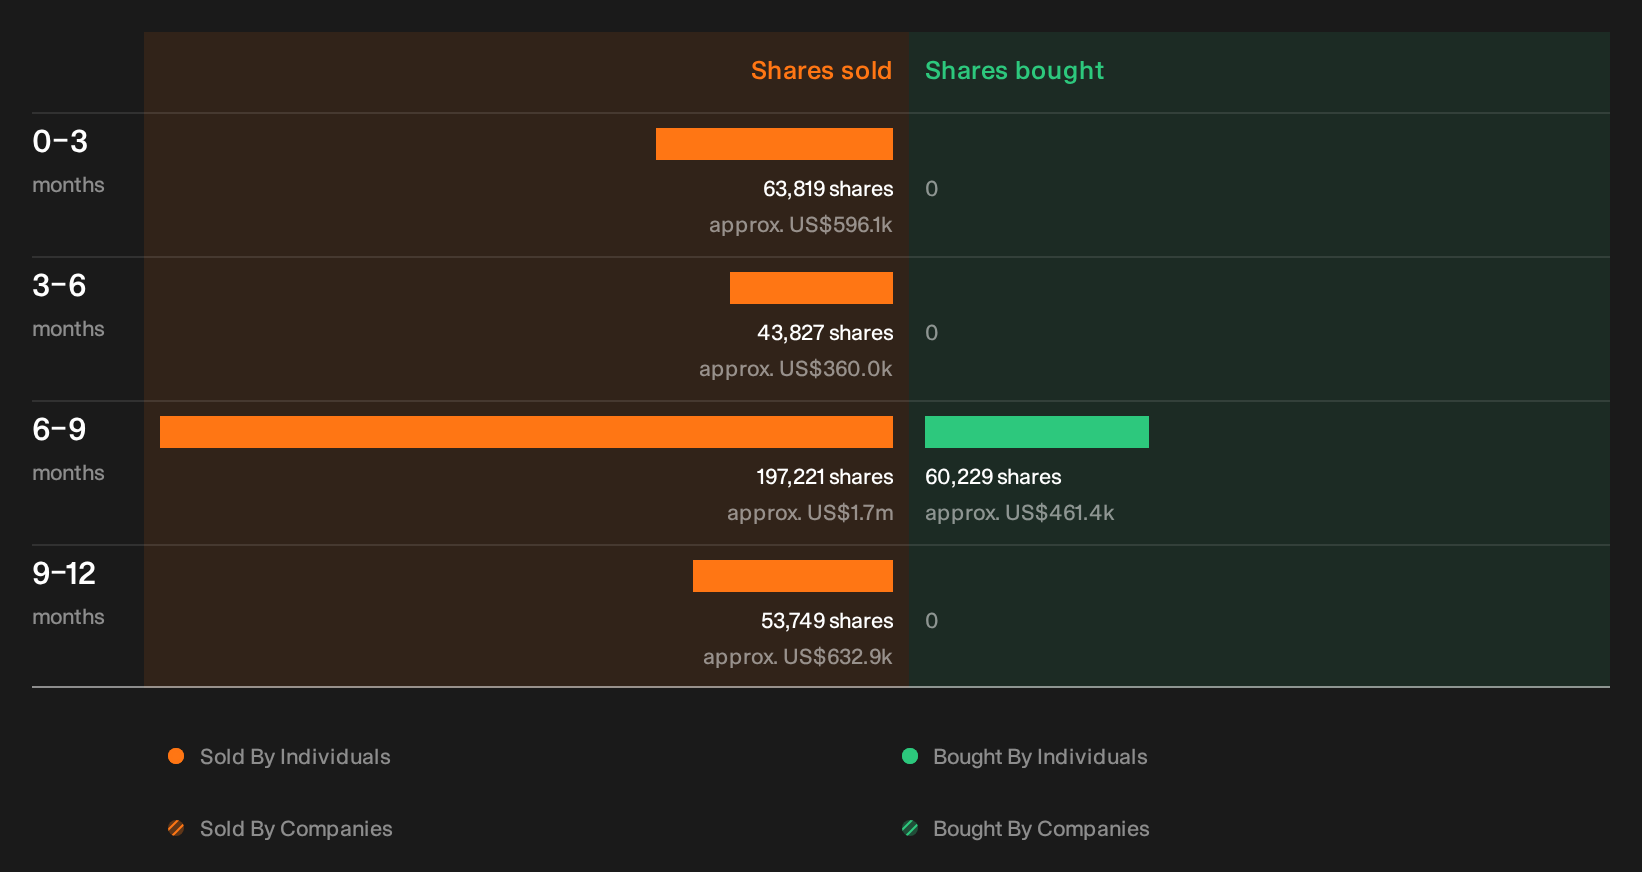
Price multiples only tell part of the story, because recent trading records also show insider share sales, and the who, how much and possible read throughs are all still for you to inspect. See the recent insider selling flagged for Ocular Therapeutix.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com