


How Investors May Respond To T Mobile US (TMUS) Privacy First Ad Partnership
- Vistar Media recently announced expanded audience segments for digital out-of-home campaigns that rely on T-Mobile US first-party, privacy-centric carrier data, available exclusively through Vistar's demand-side platform.
- The partnership turns T-Mobile US consented carrier, app engagement and location signals into aggregated audience scores that can help advertisers target physical screens more precisely across many sectors while keeping individual user data protected.
- We will now look at how this privacy-centric data partnership might influence T-Mobile US's broader investment narrative around adjacencies.
T-Mobile US Investment Narrative Recap
To own T-Mobile US, you need to believe that its 5G network, broadband push and adjacencies like advertising can translate into steadier service revenue and rising free cash flow, even with modest forecast top line growth of 4.1% a year. The Vistar partnership fits that story as an extra use case for its privacy-centric data, but it does not look like a major near term driver.
The near term swing factor still sits with core wireless economics. Rate plan modernization and higher bills risk nudging churn higher just as competitors lean into richer device promos. If bill pressure or legal issues around product bundling gain traction, those could matter more to earnings than incremental ad data revenue.
The Vistar announcement connects most directly to T-Mobile US’s broader push into adjacencies that use its network and data assets more efficiently. Management is already leaning on 5G capacity, spectrum modeling and AI tools to support higher value postpaid and broadband growth. Advertising solutions that use aggregated, consented carrier data extend that same logic into marketing budgets.
For catalysts, the interesting angle is execution discipline rather than headline buzz. If T-Mobile US can fold privacy-centric DOOH targeting into its existing AI and network stack without distracting focus from broadband or premium plan adoption, the business adds one more relatively low capital revenue stream. If efforts around adjacencies spread management bandwidth too thin, the risk is softer progress on the core churn and pricing issues investors watch most closely.
T-Mobile US' narrative projects US$104.6b revenue and US$18.3b earnings by 2029. This aligns with analyst assumptions of 4.3% yearly revenue growth and an earnings increase of about US$7.7b from current earnings of US$10.6b.
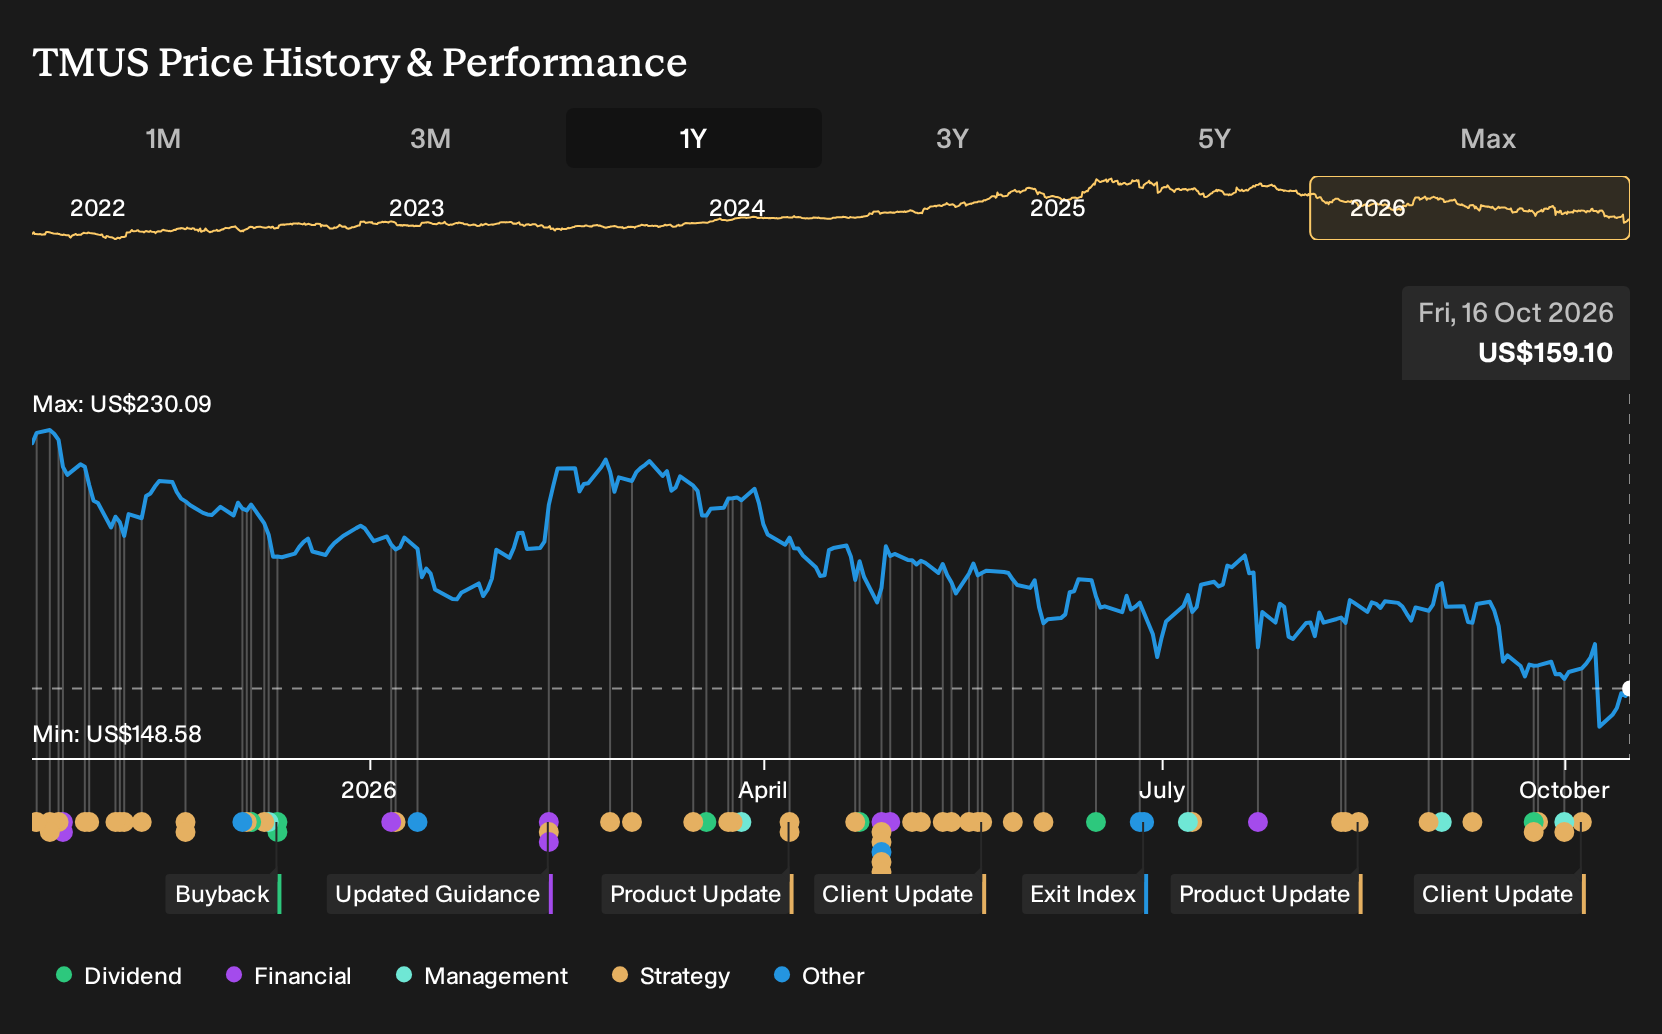
Uncover why T-Mobile US' fair value indicates a 49% potential upside to its current price, a discount that could close quickly.
Exploring Other Perspectives
One alternative view says the real swing factor is how efficiently T-Mobile US can fund these adjacencies at all. The most cautious analysts were penciling in revenue of about US$102.3b and earnings of US$16.2b by 2029, well below the bullish camp. This shows how sharply opinions diverge and how this Vistar news could shift those assumptions.
Explore 2 other T-Mobile US fair value estimates, including one that suggests it could be worth just $236.84!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your T-Mobile US research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking For More Investment Ideas Beyond T-Mobile US?
After forming a view on T-Mobile US, it can help to widen the lens and compare it with other businesses that match the kind of balance sheet strength, income profile, or risk level you are comfortable with. The Simply Wall St Screener lets you filter for exactly those traits, then track them over time.
- For investors who care most about financial resilience and low leverage, review a curated list of solid balance sheet and fundamentals (25 results) that keep debt in check and fundamentals front and center.
- If you are hunting for potential mispricings based on quality and valuation, scan through a focused set of 33 high quality undervalued stocks that may offer more for every dollar you put to work.
- Income seekers who want yield backed by real balance sheet support can work through a targeted group of 8 dividend fortresses built around steady cash distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com