


Is Sunoco (SUN) Still Reasonable After A 166% Five Year Run?
Sunoco has delivered a powerful long term run, and with the share price now far above where it was several years ago, the key issue is whether that climb still lines up with what the business earns.
- Over the past 5 years, Sunoco has returned 166.3%, which puts real weight on the question of whether current earnings can support this kind of long haul performance.
- The partnership structure and fuel distribution model can influence how much of its earnings turn into cash that is available for reinvestment or distributions, which matters for how much investors may be willing to pay for each dollar of profit.
- The analysts covering Sunoco have run their own numbers. See what analysts think Sunoco's shares could be worth.
The stock's next move may depend on whether Sunoco's current price still lines up with what its earnings profile can justify.
If you want a yardstick for Sunoco's earnings story, it can help to line it up against other companies screened on earnings and valuation signals such as 33 high quality undervalued stocks.
Does Sunoco Look Undervalued on Earnings?
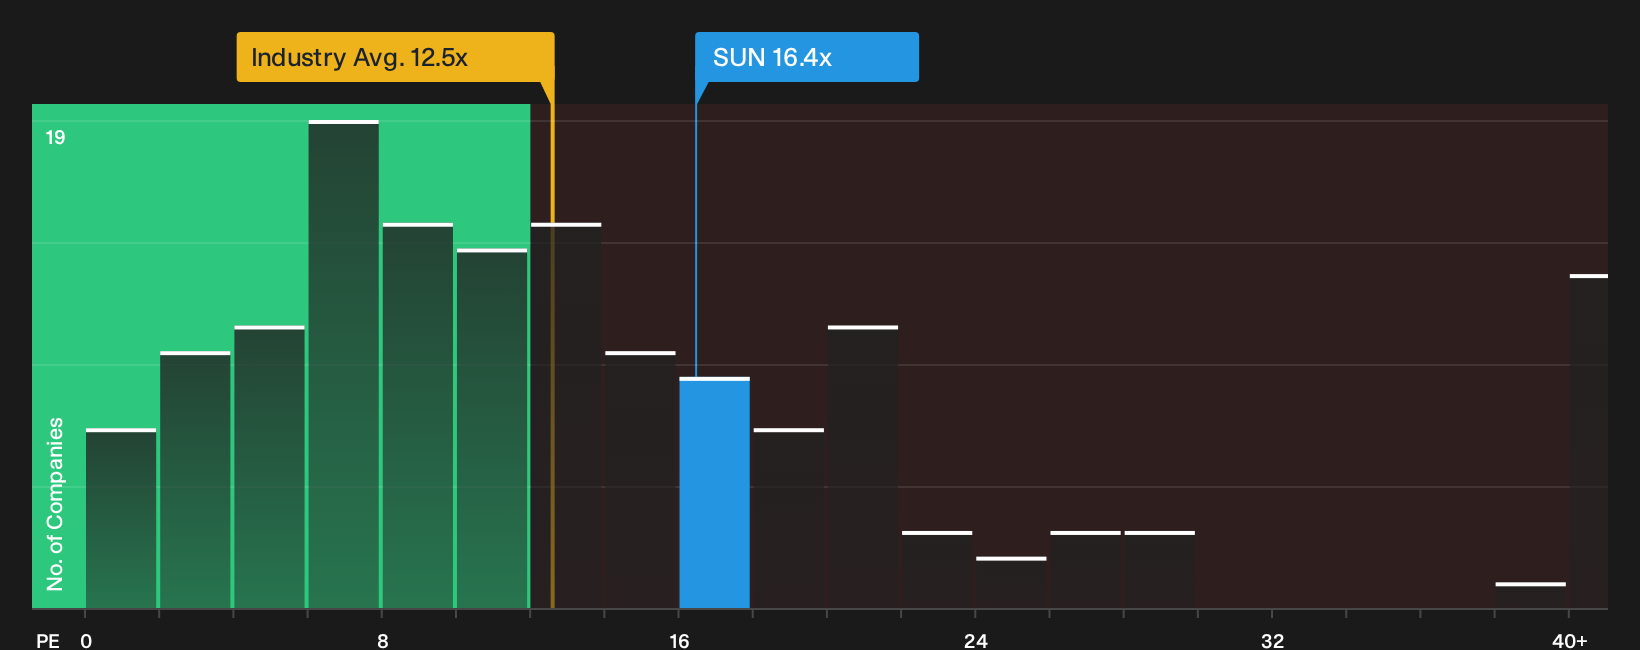
The P/E ratio fits Sunoco because earnings remain the main reference point for a fuel distributor with steady demand for its products. On this measure, the stock trades on a P/E of 16.4x, which is higher than the Oil and Gas sector average of 12.5x yet below the broader peer group on about 25.6x. That mix suggests the market gives Sunoco more credit than the typical industry player, but not as much as some comparable firms.
The valuation model that blends Sunoco's growth profile, profitability, size and risk suggests the earnings multiple that might suit the partnership is higher than where the shares change hands today. That gap implies the current P/E points to the stock being undervalued on this framework. Any investor still needs to weigh how sustainable current earnings are and how the partnership structure affects cash available to unitholders. Explore the numbers behind Sunoco's P/E valuation.
The Sunoco Narrative: What Would Justify Today's Price?
Sunoco Narratives on Simply Wall St pick up where the valuation puzzle leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for the partnership to be worth significantly more or less than its current price, and they sit on the Community page. Each scenario links a fair value view to a clear storyline about Sunoco's possible catalysts and risks, so you can track over time which path appears to be unfolding in the real business and market.
One of the top community narratives on Sunoco: 10% undervalued
"Synergy capture and operational optimisation remain central to the Sunoco playbook, with Parkland integration expected to deliver US$125 million of in year synergies..."
Discover why this Narrative puts Sunoco at 10% undervalued.
One more angle on Sunoco that could change how you see it
Everything here has focused on what Sunoco looks like today. Yet professional analysts have mapped out where they expect this partnership to be several years from now, which gives you a different yardstick to compare with the current price. Explore where analysts expect Sunoco to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com