


Iluka Resources (ASX:ILU) Could Be 37% Undervalued On Rare Earths Supply Focus
Fresh attention on rare earths supply has pushed Iluka Resources (ASX:ILU) back into the spotlight, as South Africa and other regions position producers like Iluka alongside non Chinese critical mineral suppliers.
Recent trading tells a mixed story for Iluka Resources. The 1-day share price return of 5.34% lifted the stock to A$5.33, yet the 30-day share price return is down 11.17% and the 1-year total shareholder return has declined 33.61%. This suggests short-term interest is picking up while longer term momentum has been weak as investors reassess revenue prospects, risk and what they are willing to pay for its sales.
Scan other rare earths players receiving similar attention to Iluka Resources by reviewing our curated list of 32 best rare earth metal stocks in this space.
Iluka Resources now pairs a sharp share price pullback with fresh rare earths attention. Does that mix still leave more upside than downside for new buyers once the valuation is stripped back?
Most Popular Narrative: 36.5% Undervalued
On the narrative view, Iluka Resources carries a fair value of A$8.395 per share versus the recent A$5.33 close, which puts a lot of weight on assets and projects beyond current earnings.
At A$8.395 per share, Iluka Resources (ASX: ILU) appears reasonably valued when considering its existing mineral sands business, its 20% interest in Deterra Royalties and the progress already made on the Eneabba rare earths refinery. With approximately 430 million shares on issue, the assessed price values Iluka’s shares at around A$3.61 billion.
See why 3 investors see Iluka Resources as 37% undervalued.
Result: Fair Value of A$8.395 (UNDERVALUED)
Still, Iluka Resources faces clear swing factors, including execution risk on the Eneabba refinery build and the higher net debt carried across both mineral sands and rare earths.
Find out about the key risks to this Iluka Resources narrative.
Another View: Iluka Resources Looks Expensive On Sales
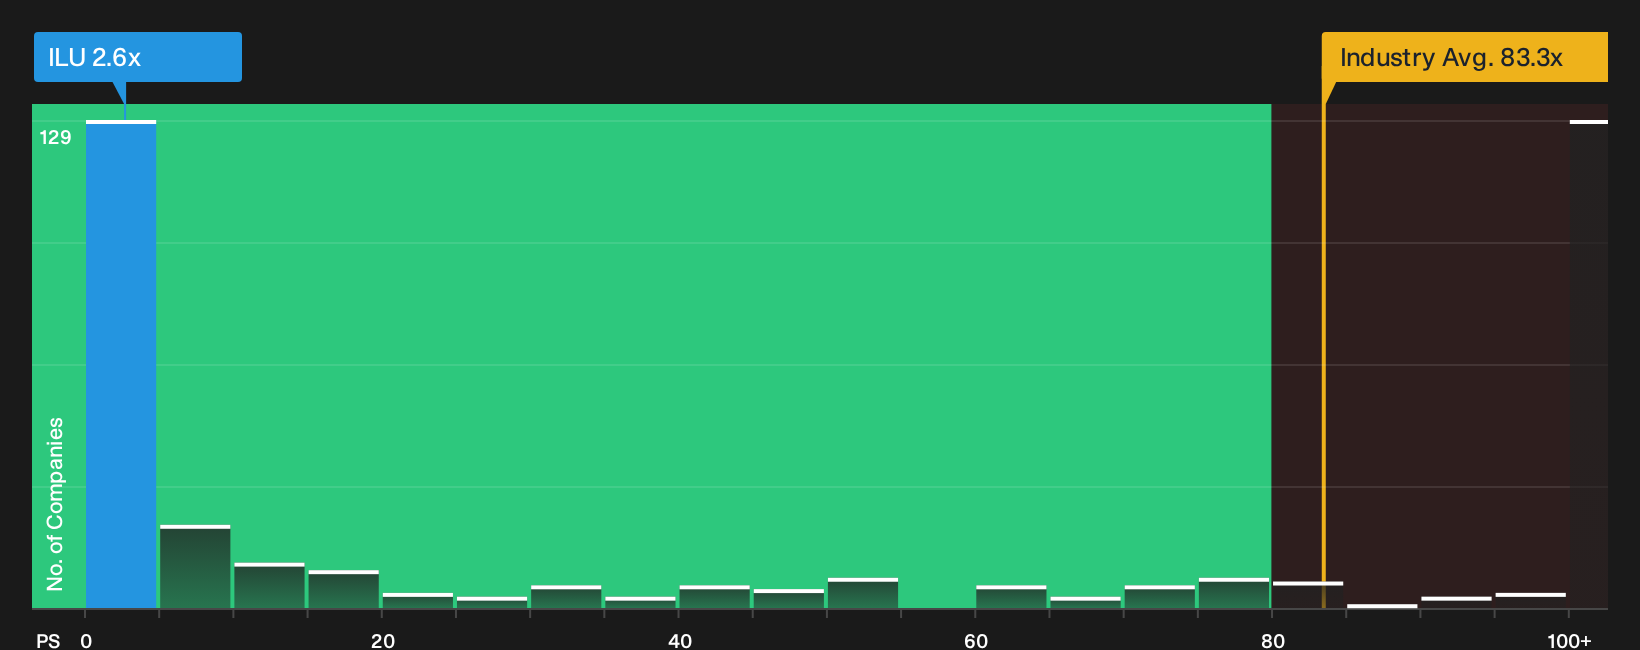
The SWS fair value narrative leans on assets and projects, yet Iluka Resources screens differently when the focus shifts to sales. On a P/S of 2.6x, the stock trades above peer levels of 1.5x even though the fair ratio is estimated at 4.2x. That gap hints at upside potential but also real valuation risk if sentiment on rare earths cools.
For a closer look at how these P/S signals stack against cash flow potential, check the valuation breakdown next, where the numbers do the talking rather than the story See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Iluka Resources often create interesting setups, so consider reviewing the full picture for yourself by reading the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Iluka Resources?
If Iluka Resources has caught your eye, do not stop there. Use this momentum to line up your next potential opportunities before the crowd moves on.
- Target quality at a discount by scanning our curated pool of 4 high quality undervalued stocks that pair strong fundamentals with compressed valuations.
- Prioritise resilience by focusing on a list of solid balance sheet and fundamentals (12 results) that can better handle shocks when conditions get tougher.
- Get ahead of the market by reviewing 15 high quality undiscovered gems that have strong financial underpinnings yet still sit off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com