


Tutor Perini (TPC) Stock Could Still Trade Below Fair Value After New Wins
Tutor Perini has delivered a very large 3 year share price gain, yet recent pullbacks now have investors asking whether the current valuation is still supported by the cash the business can generate. With the stock closing at US$77.65 and fresh contract wins in hand, the open question is how well those projects ultimately translate into sustainable cash flows.
- The share price has risen more than 10x over the past 3 years, which puts extra focus on whether that move lines up with the company’s long term cash generation.
- New Coast Guard and data center contracts, worth a combined US$586m, can shape future project mix, the timing of cash receipts, and the working capital the construction group needs to commit.
- What if you looked at Tutor Perini through its earnings instead? See what Tutor Perini's 32.9x P/E says about the price.
The issue now is whether Tutor Perini's current share price is justified by the cash flows implied by its intrinsic value estimate using the Discounted Cash Flow (DCF) approach.
To pressure test whether Tutor Perini's huge 3 year move and new contracts line up with the cash story you want to back, it can help to compare against 32 high quality undervalued stocks.
Is Tutor Perini a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Tutor Perini can return to shareholders over time. On the latest figures, the business generated roughly $680.8 million of free cash flow over the last twelve months, and the forecast path in the DCF assumes that future annual cash flows settle into a relatively flat to mildly declining pattern rather than rapid expansion. That combination of solid recent cash generation with restrained forward assumptions keeps the analysis grounded in what the current project mix can plausibly support.
Despite Perini Management Services securing a US$315 million Coast Guard pier contract in Alaska, the model still points to an estimated intrinsic value that sits substantially above the current US$77.65 share price. The construction work stretches out to 2030, so the DCF treats it as one contributor to a long pipeline rather than a one off windfall, yet the projected cash flows it feeds into still imply the market is not fully crediting the business for that stream of work. Find out what Tutor Perini could be worth using our Discounted Cash Flow (DCF) estimate.
The Tutor Perini Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the Tutor Perini valuation puzzle leaves off by spelling out what mix of future growth, margins and earnings would need to materialise for the share price to sit meaningfully above or below where it trades today. Each scenario ties a fair value estimate to a particular set of potential catalysts and risks for Tutor Perini, so you can track over time which version of the story the business seems to match.
One of the top community narratives on Tutor Perini: 26% undervalued
"Reliance on large public contracts, labor pressures, litigation risks, and required tech investments threaten profit stability, cash flow, and long-term competitiveness..."
Discover why this Narrative puts Tutor Perini at 26% undervalued.
One more Tutor Perini puzzle that the valuation does not answer
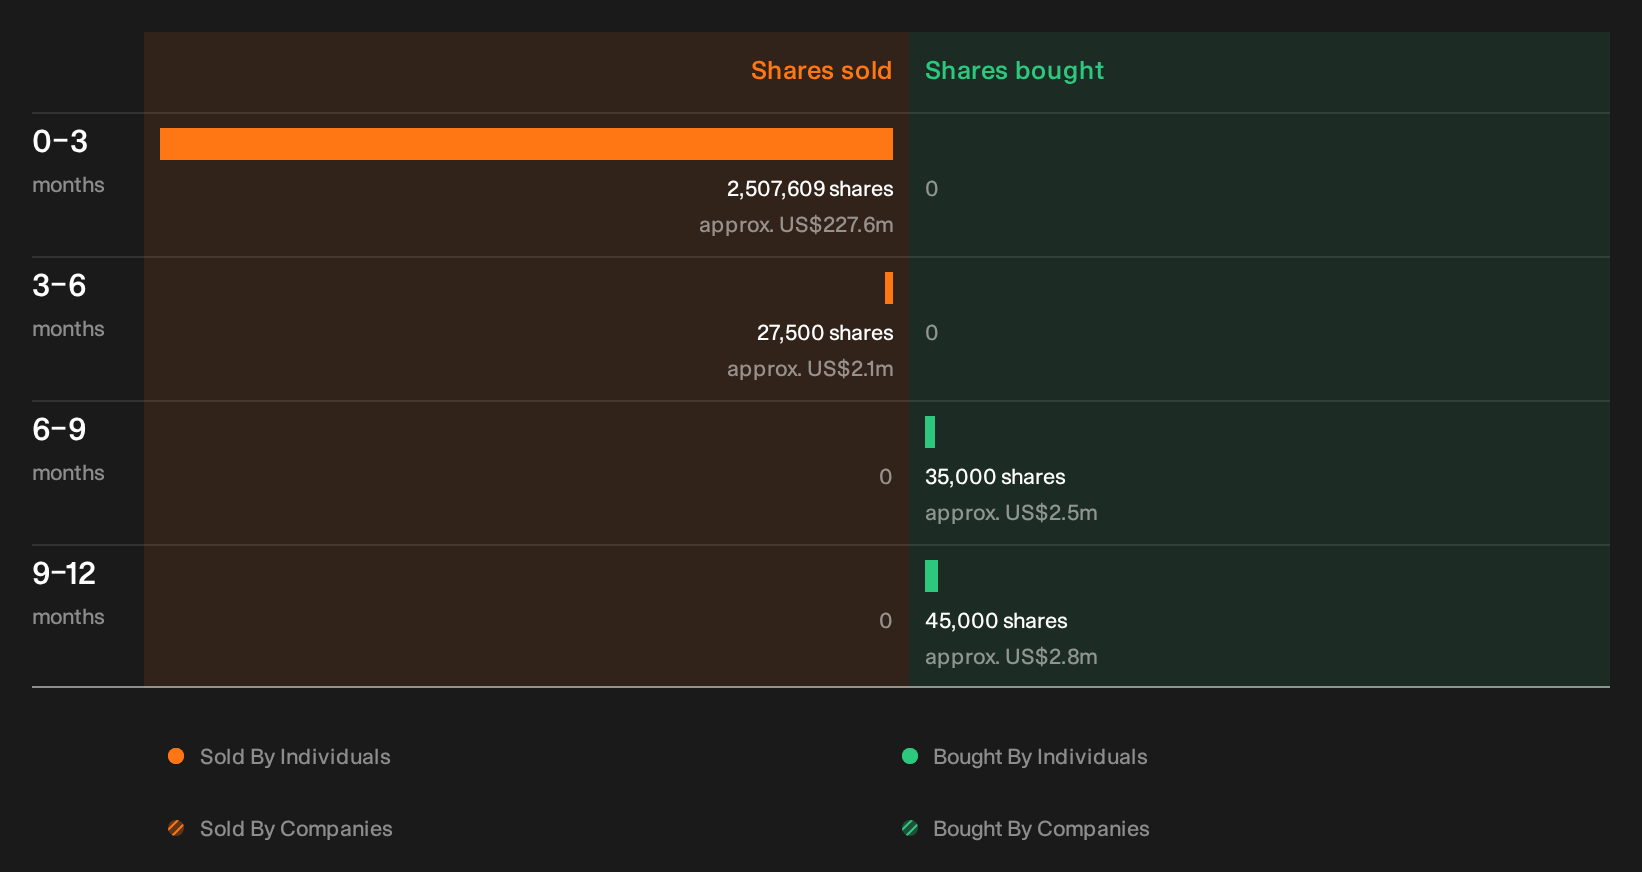
Valuation work only gets you so far. Recent trading by people inside Tutor Perini adds another layer that investors often study closely, from who sold to how much and why. See the recent insider selling flagged for Tutor Perini.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com