


Cummins (CMI) Is Back In Focus, What Is Drawing Investors In?
Cummins (CMI) is back in focus after its board declared a quarterly cash dividend of US$2.20 per share, payable on December 3, 2026, to holders of record as of November 20.
That dividend decision lands while Cummins shares change hands at US$531.33, with short-term momentum soft after the share price fell about 18.1% over the past 90 days. However, the longer-term total shareholder return of 30.9% over one year signals sentiment has remained broadly supportive despite recent volatility.
Scan beyond Cummins and review other industrials with resilient payouts and solid balance sheets using our hand picked 8 dividend fortresses as a comparison set.
Cummins looks like a robust industrial powerhouse, backed by a fresh dividend and solid recent returns, yet the share price slide over the past quarter raises a sharper issue. Is that strength already fully reflected in today’s valuation?
Most Popular Narrative: 26% Undervalued
Cummins is trading at a last close of $531.33 while the most followed narrative pegs fair value closer to $721, a gap that puts its future power and data-center exposure under the spotlight.
Cummins is experiencing strong and steadily growing demand for power generation equipment, especially from the data center sector, supported by record Power Systems revenue of US$2.3b in Q2 2026 and a globally supply constrained market for large diesel standby gensets, which can continue to lift revenue and support higher EBITDA margins as orders already extend into the second half of 2028.
See why 60 investors see Cummins as 26% undervalued.
Result: Fair Value of $721.14 (UNDERVALUED)
Still, Cummins faces two clear pressure points: rising input and tariff costs that weigh on margins, and ongoing Accelera losses that could offset strength elsewhere.
Find out about the key risks to this Cummins narrative.
Another View: Cummins On Earnings Multiples
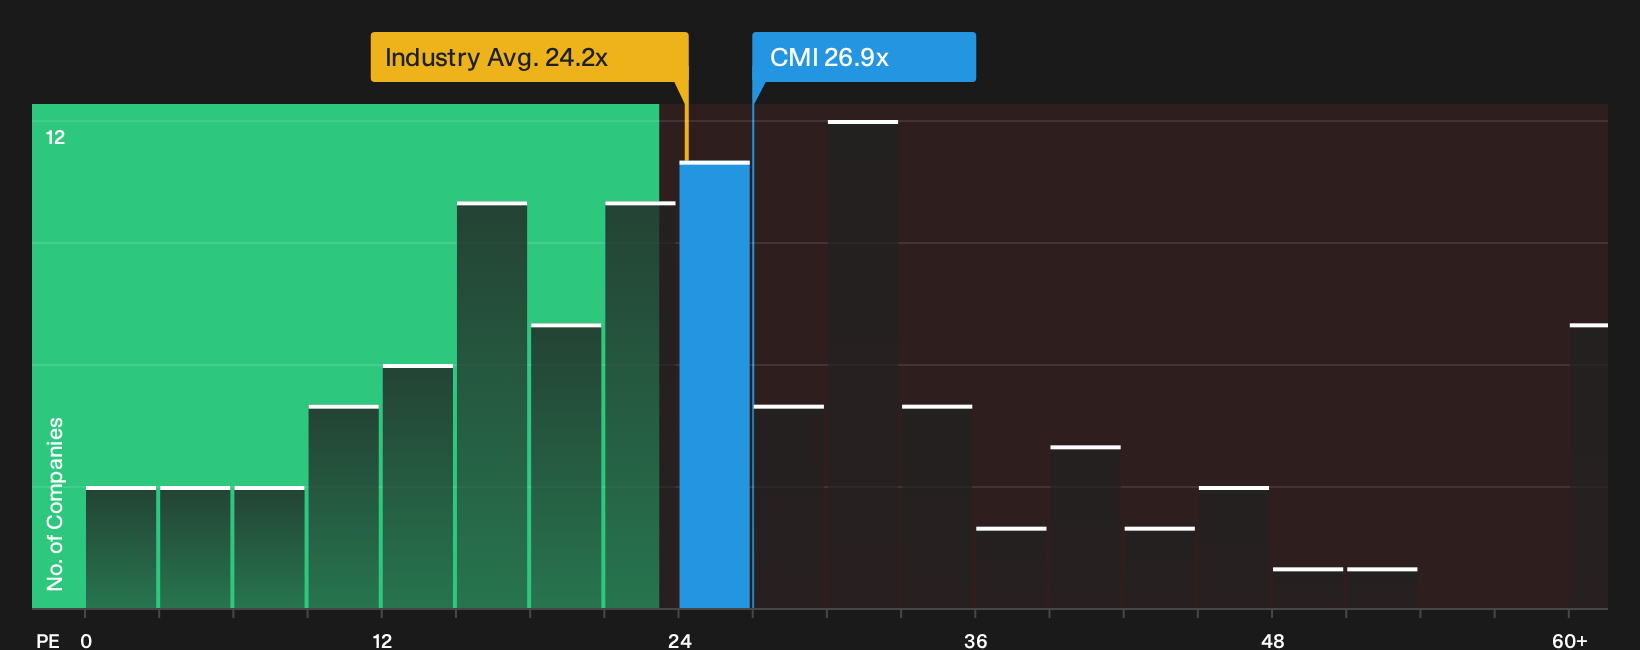
On fair value maths, Cummins screens about 33.8% below the Simply Wall St estimate, yet the current P/E of 26.9x tells a different story. That is higher than the wider US Machinery group on 24.2x, only slightly below peers at 27.5x, and under a fair ratio of 35.4x that the market could move toward. For an investor, that mix suggests room for optimism if earnings track forecasts, but also clear valuation risk if sentiment swings back toward the broader industry range.
To see how these P/E gaps could matter for your own return expectations, and where the numbers leave less margin for error, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big claims around Cummins valuation and rewards only matter if the evidence stacks up in your view. Take a few minutes to comb through the data, stress test the assumptions, and then weigh the 4 key rewards.
Looking for more Cummins sized investment ideas?
If Cummins has sharpened your focus on quality, use the Simply Wall St screener to identify new candidates before the crowd gets there.
- Target strong potential upside by scanning companies that screen as 33 high quality undervalued stocks based on cash flows and balance sheet strength.
- Focus on reliability by filtering for businesses that show up as 32 resilient stocks with low risk scores in terms of financial stability and volatility.
- Look for overlooked opportunities by reviewing a curated set of 20 high quality undiscovered gems that have not yet attracted broad market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com