


PLS Group (ASX:PLS) Following Its Pilgangoora Expansion Approval Is The Undervalued Narrative Still Intact
Why PLS Group’s expansion decision matters now
PLS Group (ASX:PLS) has locked in a multi billion dollar commitment to expand its Pilgangoora lithium operation, approving the P2000 project and a final investment decision that targets a significant increase in spodumene production capacity by 2029.
The plan includes a new processing plant and upgraded infrastructure, with funding primarily from existing cash and operating cash flow. Debt remains a potential support option if conditions require more flexibility.
Recent price action for PLS Group has been weak, with the 30 day share price return down 29.38% and the year to date share price return down 30.86%. However, the 1 year total shareholder return is still 12.22%, which points to fading momentum despite this expansion announcement grabbing investor attention this week.
Scan beyond PLS Group’s expansion story and size up other lithium and resources opportunities with our hand picked 32 best rare earth metal stocks that could be setting up their next big move.
For PLS Group, an A$1.9b expansion alongside a share price that has slid over the past year sets up a clear tension. Does that shift the risk reward balance toward buyers, or toward more patience as the valuation case is tested next?
Most Popular Narrative: 41% Undervalued
On the most followed view, PLS Group’s shares at A$2.98 sit well below an implied fair value of about A$5.05, which frames the expansion decision against expectations for higher future cash generation.
The combination of a cash balance of about A$2.3b, total liquidity approaching A$2.8b and a recently issued US$600 million senior unsecured bond due 2031 gives PLS Group scope to fund higher FY27 capex of A$620 to A$685 million and future projects like P2000, which can influence long term production capacity, revenue and earnings power.
See why 141 investors see PLS Group as 41% undervalued.
Result: Fair Value of A$5.05 (UNDERVALUED)
Still, the PLS Group narrative could be knocked off course if lithium pricing weakens again or if higher FOBr costs squeeze margins as Pilgangoora expands.
Find out about the key risks to this PLS Group narrative.
Another View: What PLS Group’s P/E Is Telling You
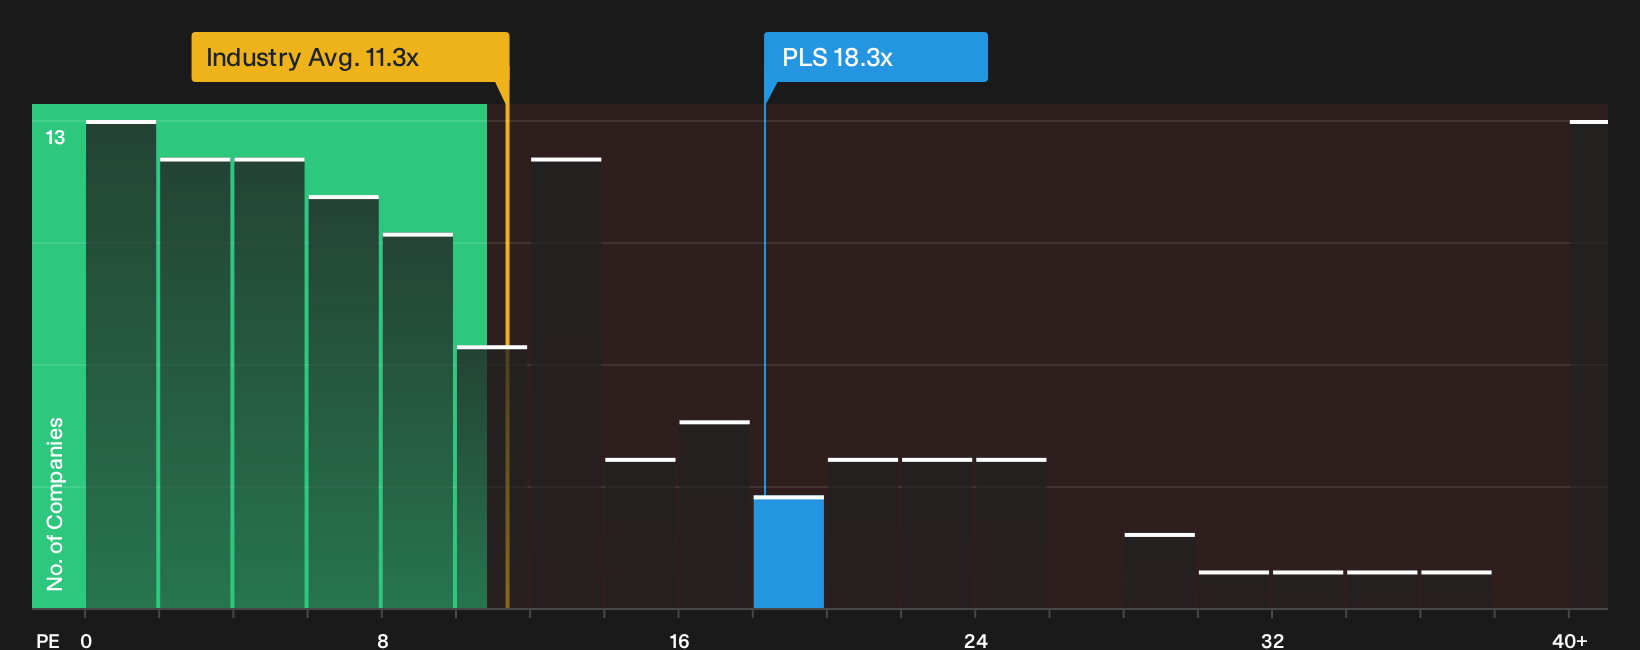
On a simple earnings multiple, PLS Group screens less generous. The shares trade on a P/E of 18.3x compared with 11.3x for the Australian Metals and Mining sector and a fair ratio of 16.1x, even though they are cheaper than the 25.1x peer average. That gap lifts valuation risk if earnings or sentiment slip again.
To see how these earnings multiples square with a fuller valuation picture, including cash flows and project returns, it is worth weighing them against our fair value work in more detail. See what the numbers say about this price — find out in our valuation breakdown.
For readers who want to see where PLS Group currently sits against sector pricing visually, and how that 18.3x compares with the broader market, the following chart provides a simple reference point.
Next Steps
If the mixed signals in PLS Group’s story leave you on the fence, go through the numbers yourself and carefully test every assumption. Then compare your conclusions with the 3 key rewards
Looking for more investment ideas beyond PLS Group?
Do not stop at PLS Group. Use this momentum to line up fresh ideas that match your risk appetite, income goals and balance sheet comfort zone.
- Target potential mispricing by scanning our curated pool of quality opportunities through the 4 high quality undervalued stocks.
- Strengthen your passive income plan by filtering for reliable cash returns with the 4 dividend fortresses.
- Reduce portfolio stress by focusing on financially resilient businesses using the 6 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com