


Ricegrowers And 2 Other Australian Dividend Stocks
Rising global borrowing costs are front and center again, with the IMF warning that higher interest bills and stretched public finances are putting pressure on governments and households. Income is back in fashion. Reliable Australian dividend stocks that offer yields above 5% can feel like being paid to wait while others worry about rate moves. This article highlights three long term payout candidates from that high yield royalty list.
The three dividend ideas below are just a sample from the higher yielding end of the market, and the full Dividend Aristocrats screen surfaced 1 more company with a similarly interesting income story that is not covered here.
If you want to go beyond these examples and identify which high yield payers best fit your own income goals, head straight into the Dividend Aristocrats screener to filter, analyze, and focus on your highest conviction candidates.
Ricegrowers (ASX:SGLLV)
Overview: Ricegrowers is a Leeton based food group that turns grower rice into branded consumer products like SunRice, Riviana and Trukai worldwide.
Operations: Ricegrowers generated about A$737 million from international consumer packaged goods, A$735 million from Australia and New Zealand CPG and A$328 million from bulk rice and animal feed.
Market Cap: A$920 million
Ricegrowers ties cleanly into the Dividend Aristocrats theme because much of its income comes from everyday rice brands that households keep buying regardless of market swings. Earnings growth of 3.4% last year and a share price described as trading below estimated fair value are both cited as supporting the income profile. However, the strength of future payouts depends on one less visible factor in its crop cycle and processing economics.
That crop cycle lever can reshape the whole income picture, so review the 4 key rewards and 1 important warning sign for Ricegrowers before banking on those payouts for the long haul.
Peet (ASX:PPC)
Overview: Peet develops and sells residential land and masterplanned communities across Australia, with its funds management arm providing recurring income streams.
Operations: Peet generated A$305 million from Development, A$95 million from Funds Management, and A$33 million from Joint Arrangements, all from Australian projects.
Market Cap: A$763 million
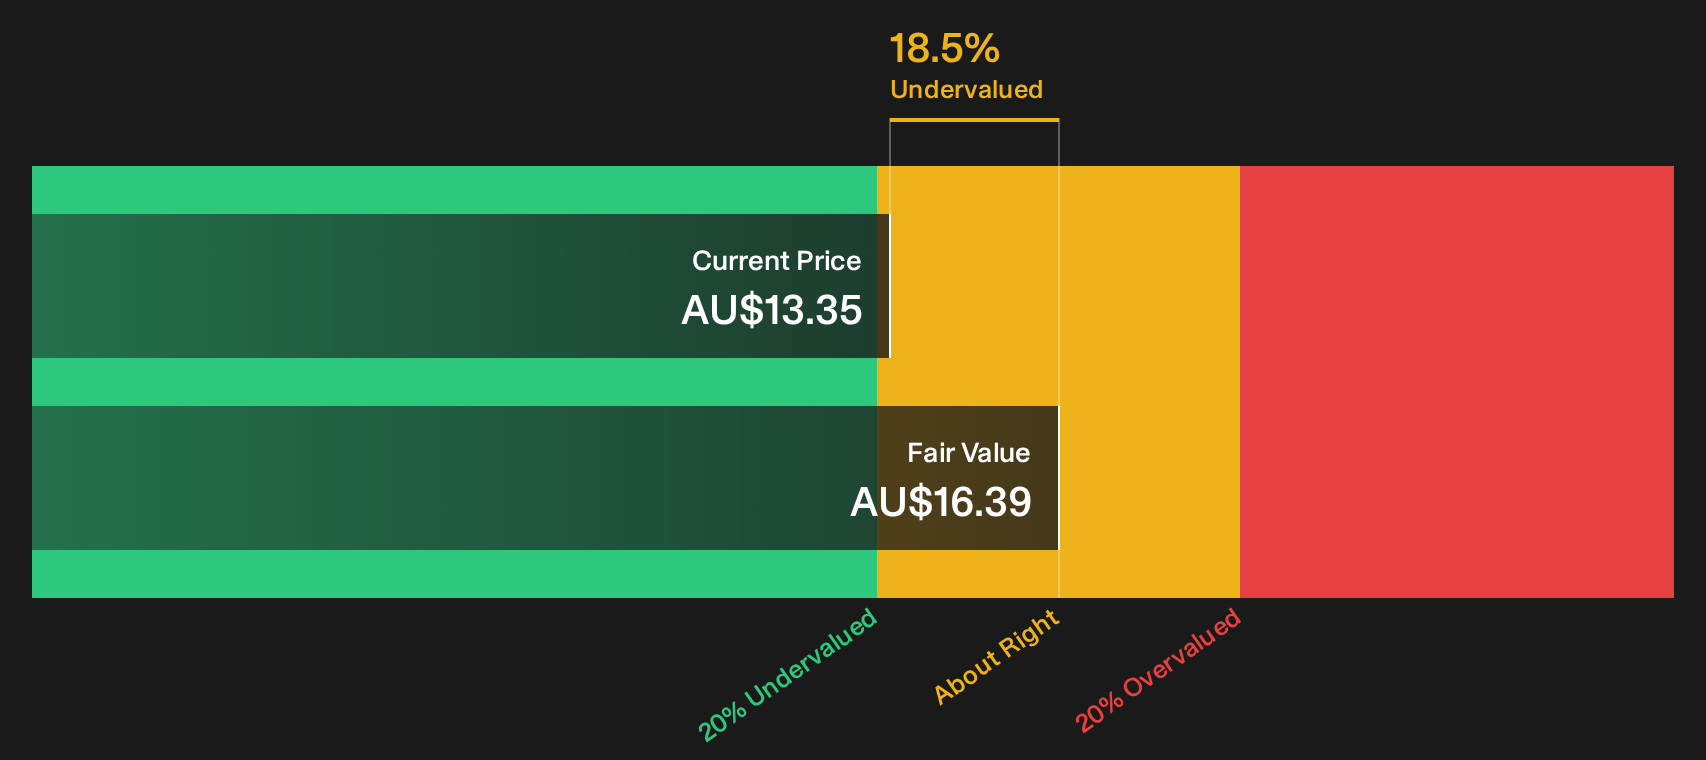
Peet relates to the Dividend Aristocrats theme through its funds management division, where long-term land development funds generate fee income and developer profit share that can support a yield above 5%. Recent full-year revenue of A$419.13 million and net income of A$103.4 million provide a basis for the dividend profile, although any change in how those fund flows behave could affect the comfort level around future payouts.
Those shifting fund flows are the real hinge, so check the 2 key rewards and 1 important warning sign to see how Peet's yield story lines up with that capital cycle risk.

Sandfire Resources (ASX:SFR)
Overview: Sandfire Resources is a West Perth based miner that produces copper driven concentrates. Its cash flows support its high dividend profile.
Operations: Sandfire Resources earns most of its income from the MATSA Copper Operations at about $910 million and the Motheo Copper Project at about $745 million.
Market Cap: A$9.6b
For income investors, Sandfire Resources brings a different flavour to the Dividend Aristocrats theme, with a high payout backed by producing copper hubs rather than a broad portfolio of slow and steady franchises.
"Sandfire's ramp-up and optimization of the Motheo Copper Mine in Botswana is expected to deliver sustained step-changes in ore output and revenue. Ongoing investment in infill drilling and pre-feasibility studies at Motheo (A1, A4, T3) position the company to extend mine life towards the 15-year target at processing hubs, supporting long-term revenue growth and production visibility."
What happens if a single unseen pressure on those copper linked cash flows shifts, for better or worse, will matter a lot.
That pressure point is where things get interesting, and the full narrative for Sandfire Resources explains how Sandfire Resources' copper engine could accelerate, stall, or quietly reshape your income thesis.

Seeking Alternatives Before The Crowd?
Fresh opportunities move quickly. Some tickers build quiet breakout momentum while others start dropping once the crowd finally notices. Scan these under the radar lists while it matters and consider them before they become widely followed.
- Spot cash rich businesses that still trade like afterthoughts by running the list of solid balance sheet and fundamentals (12 results) before their next move is fully reflected in the price.
- Track fast moving AI themes and see which smaller players already have real earnings support through the 38 profitable AI stocks that aren't just burning cash while sentiment is still catching up.
- Review the 17 top copper producer stocks curated for producers that may be involved in copper heavy infrastructure trends.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com