


Does Claims Workflow Integration Change The Bull Case For Verisk Analytics (VRSK)?
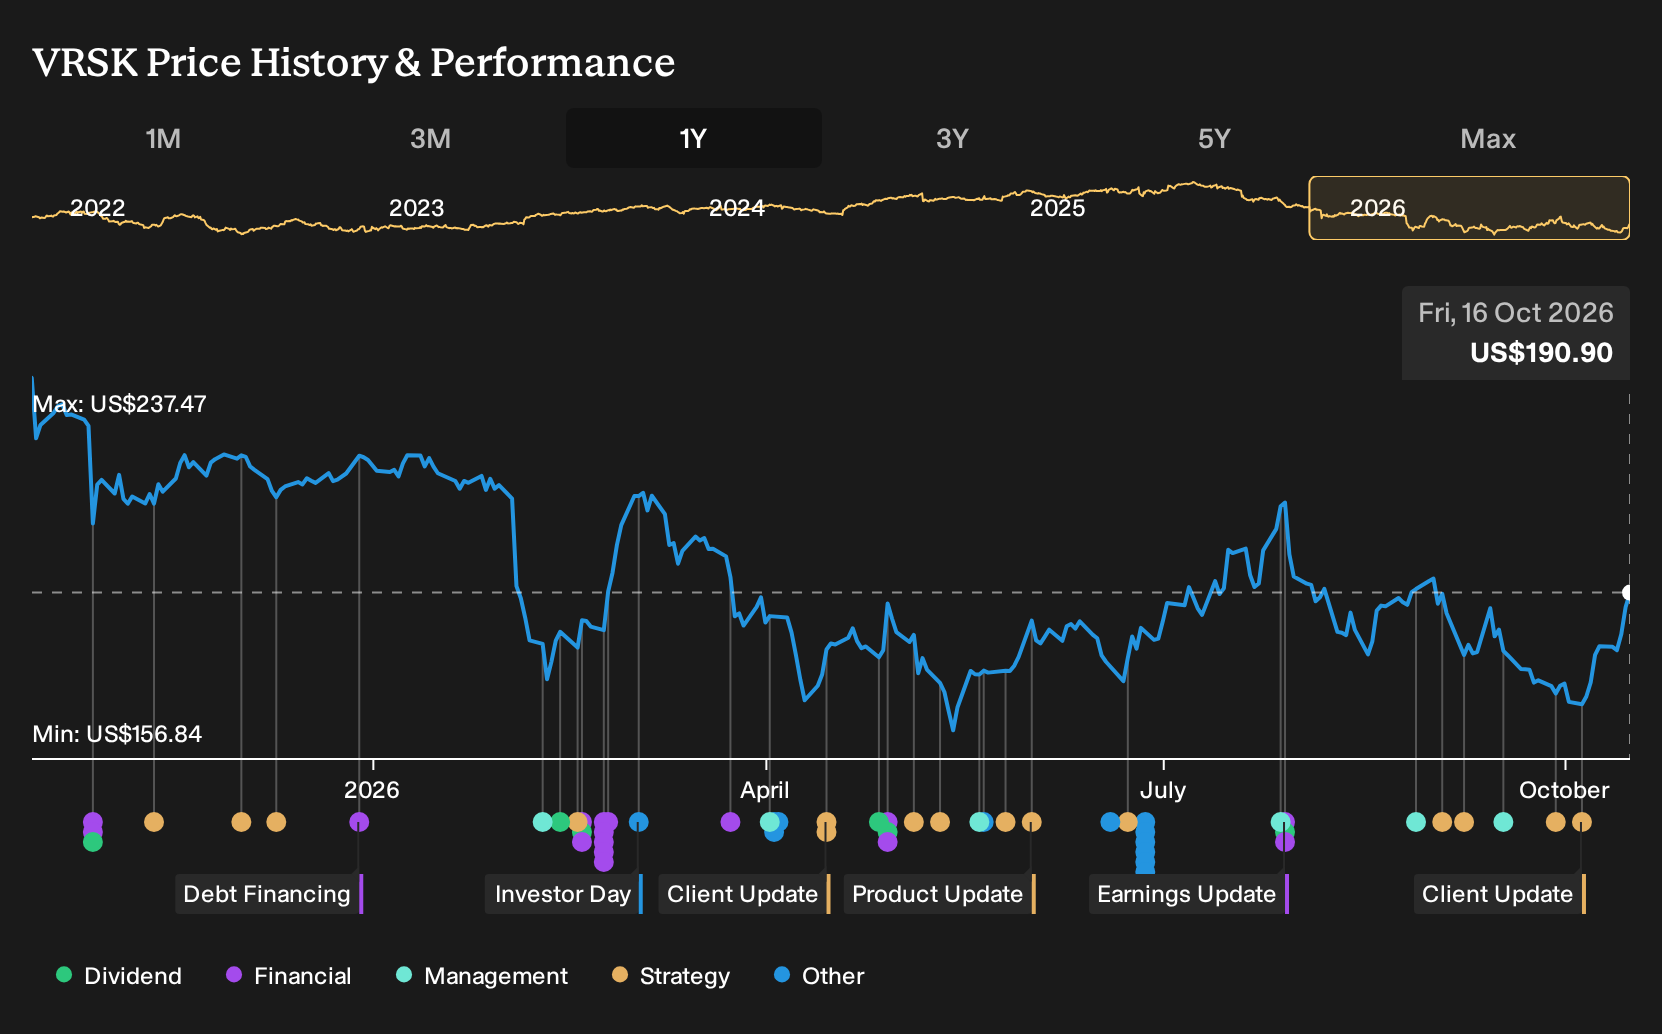
- Solera recently announced a new integration that connects Verisk Analytics' IVI Total Loss solution with the Audatex estimating platform. This allows insurers and repairers to use FNOL data and images throughout the repair process to reduce duplication and support earlier action on claims.
- The link between Verisk Analytics' total loss analytics and Audatex's estimating system gives the business a deeper role in motor claims workflows. It ties the company's data more tightly into insurer and repairer operations rather than leaving it as isolated point solutions.
- We will now look at how Verisk Analytics' investment narrative might be affected by deeper integration of its tools into claims workflows.
Scan how Verisk Analytics compares with other data driven insurers and repair-focused platforms by reviewing the hand picked 55 AI infrastructure stocks shaping the future of automated claims workflows.
Verisk Analytics Investment Narrative Recap
To own Verisk Analytics, you need to believe the subscription backed model and AI heavy toolkit can keep earning a central role in insurer workflows even as conditions stay mixed. Management already flags a soft commercial property market and weather related transactional pressure in the second half of 2026, which keeps near term growth drivers under scrutiny.
The key short term swing factor is whether subscription pricing and usage can offset that softer transactional backdrop while Verisk carries a meaningful debt load. The Solera integration deepens claims touchpoints but, on its own, does not materially change the near term risk that insurers trim discretionary analytics budgets if inflation or regulation squeeze profitability.
The recent integration between Verisk’s IVI Total Loss solution and Solera’s Audatex platform is most relevant here. It extends Verisk Analytics further into automated motor claims, tying its data and AI into day to day repair decisions instead of treating them as standalone tools. That kind of embedding is important if insurers later reassess vendor priorities.
For catalysts, this motor claims upgrade sits alongside Verisk’s push into AI products like XactAI and Premium Audit AI and the ongoing Core Lines Reimagined rollout. Together, these efforts give the business more ways to anchor itself inside client processes. Execution risk remains around insurer spending, operational complexity and the softer property and catastrophe backdrop flagged for late 2026.
Verisk Analytics' current analyst narrative points to revenues of US$3.8b and earnings of US$1.3b by 2029. This framework assumes revenue grows at 6.6% per year and earnings rise by about US$414.5m from US$885.5m today.
Uncover how Verisk Analytics' fair value indicates a 19% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
The Simply Wall St Community has five fair value views on Verisk Analytics, ranging from US$76.85 to US$288.74, resulting in almost a fourfold span. Those opinions were formed before the Solera tie up and sit alongside real risks around inflation, regulation and catastrophe activity, so it makes sense to compare several viewpoints before acting.
Explore 4 other Verisk Analytics fair value estimates, including one that suggests as much as 51% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Verisk Analytics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verisk Analytics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verisk Analytics' overall financial health at a glance.
Looking For More Ideas Beyond Verisk Analytics?
If the Verisk Analytics story has you thinking about where else data, balance sheet strength and steady execution might matter, the Simply Wall St Screener is a useful next step to widen your watchlist without losing discipline.
- If you want potential mispricings with quality fundamentals, scan the 33 high quality undervalued stocks and see which businesses currently line up with your return and risk preferences.
- For investors who care more about resilience than excitement, the 32 resilient stocks with low risk scores helps surface companies that may better match a capital preservation mindset.
- If balance sheet strength is your starting filter, the list of solid balance sheet and fundamentals (25 results) can quickly narrow the field to businesses with healthier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com