


CBRE Group (CBRE), What Is Driving Fresh Attention Now?
Why CBRE Group’s Upcoming Earnings Matter
CBRE Group (CBRE) heads into its third quarter 2026 earnings release on October 22 with management signaling confidence in revenue momentum and a more than 20% year over year increase in core earnings per share.
Those expectations, backed by diversified service lines and demand across core segments, help explain the recent swing in CBRE’s market value and set the stage for investors to reassess how the stock’s current performance lines up with that outlook.
Recent trading in CBRE Group has been choppy, with the share price down 3.96% over the past month and 5.59% over 90 days. The year-to-date share price return of 16.92% and 1-year total shareholder return of 15.30% both point to pressure on sentiment, even alongside a 3-year total shareholder return of 97.18% and 5-year total shareholder return of 28.06%.
In the short term, that pullback has coincided with news of senior brokers leaving for rivals and investors weighing management’s upbeat earnings message against competitive risks. This leaves current momentum looking fragile as the stock trades around US$133.08 ahead of the results.
Scan for other commercial real estate and outsourcing plays showing similar earnings tension to CBRE Group in our hand picked list of solid balance sheet and fundamentals (25 results)
.After a sharp pullback and upbeat earnings guidance, CBRE Group now sits in a gray zone where both optimism and worry feel justified. Does that recent slide leave enough upside to compensate for the risks?
Most Popular Narrative: 26.9% Undervalued
On Simply Wall St’s most followed narrative, CBRE Group’s estimated fair value of $182.17 sits well above the recent $133.08 close. This puts the focus squarely on whether the business can deliver on that implied upside over time.
The continued shift toward resilient businesses such as facilities management, critical infrastructure services, property management, project management, loan servicing, valuations and recurring investment management fees, which together grew revenue 18% in Q1 2026, is expected to increase the share of fee income that supports more stable margins and through cycle earnings.
See why 15 investors see CBRE Group as 27% undervalued.
Result: Fair Value of $182.17 (UNDERVALUED)
Still, two things can quickly shake that 26.9% undervalued narrative for CBRE Group: weaker advisory deal activity and slower fundraising in its investment management arm.
Find out about the key risks to this CBRE Group narrative.
Another View: What CBRE Group’s P/E Is Really Saying
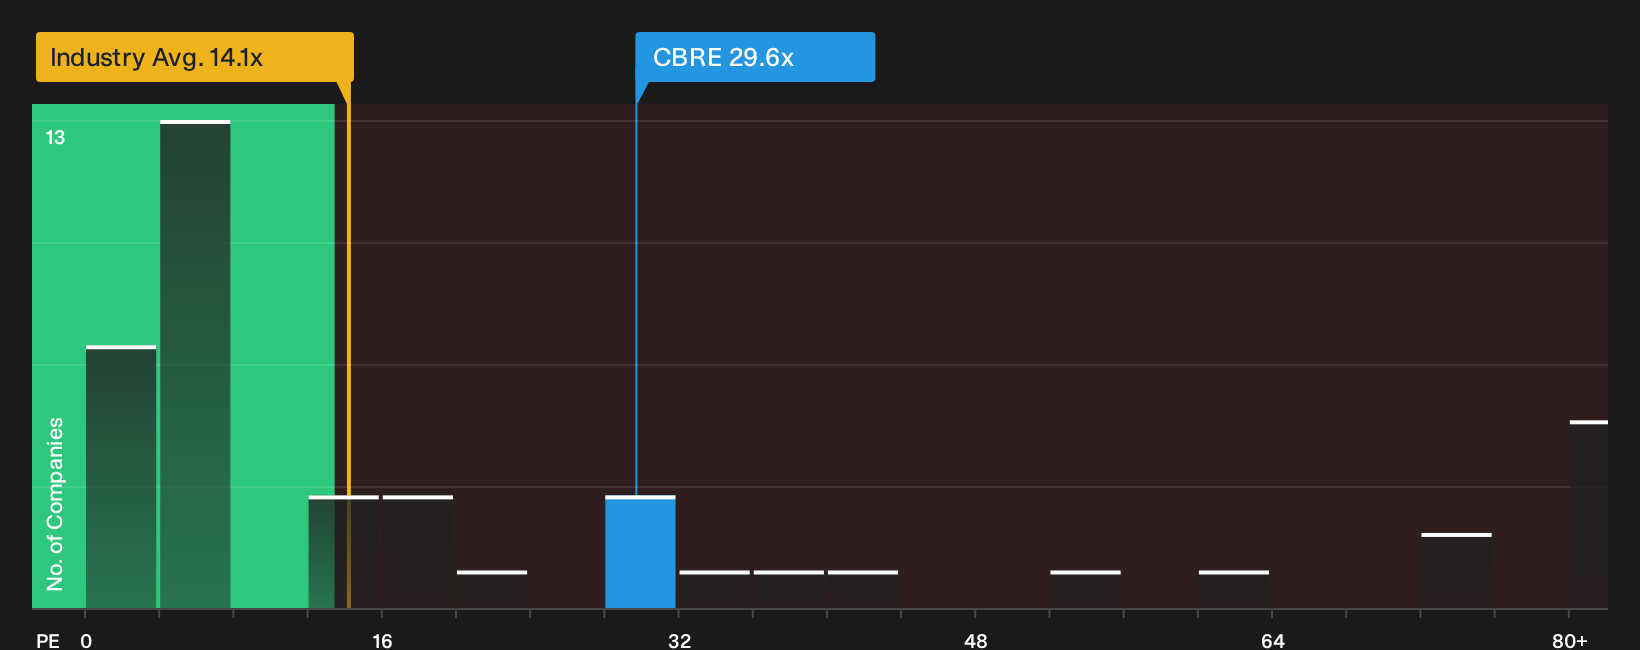
The first fair value story paints CBRE Group as undervalued. Step back and the P/E ratio tells a more complicated story. At 29.6x earnings, the stock trades at more than double the US Real Estate industry average of 14.3x, which suggests investors are already paying up for quality.
Against closer peers, that same 29.6x multiple looks modest next to an 87.6x average. It also sits below an estimated fair ratio of 36.9x. That gap can signal room for the share price to move toward that fair ratio over time, or it can shrink if sentiment cools. Which side of that tradeoff do you think is more realistic for CBRE Group?
To pressure test this earnings based view against the underlying numbers, take a look at the valuation breakdown in our multiple comparison See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the mixed mood around CBRE Group so far, with optimism on value but clear questions on risks and rewards, it makes sense to scan the numbers yourself, stress test the narratives, then weigh the 3 key rewards and 2 important warning signs
Looking for more CBRE Group style investment ideas?
If you stop with CBRE Group, you only see one angle of the market. Broaden your watchlist now so you do not miss the next move.
- Target dependable growth potential by focusing on high quality companies that still look inexpensive through our 33 high quality undervalued stocks.
- Prioritise resilience in rough markets and concentrate on businesses with sturdier financial positions using the 32 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities and find stocks with strong fundamentals that fly under most radars through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com