


Disco (TSE:6146) Could Be 53% Above Fair Value On Strong Sales Growth
Disco (TSE:6146) just released preliminary non-consolidated sales for the September 2026 quarter, reporting ¥118.5b for the period and ¥213.6b for the first half, compared with ¥85.3b and ¥160.8b a year earlier.
Against that sales update, Disco’s share price closed at ¥53,850, with a 1-day share price return of 1.26% but a 7-day move that declined 12.38%. The 1-year total shareholder return of 4.94% and very large 5-year total shareholder return of around 4.6x suggest long-term momentum remains intact even as shorter term sentiment has cooled.
Spot opportunities beyond Disco by scanning a hand-picked 55 AI infrastructure stocks that may benefit from rising demand for chipmaking tools and the broader build out of semiconductor capacity.Disco’s machines and tools clearly have buyers right now. Yet the share price just dropped more than 12% in a week. Is this still a strong business that is simply being valued as if the good news is already in the price?
Price-to-Earnings of 40x: Is it justified?
On the latest numbers, Disco trades on a P/E of 40x, which frames the current ¥53,850 share price as rich against several benchmarks.
The P/E ratio compares what investors pay today with the earnings the business currently generates. For a specialist equipment maker like Disco, that multiple reflects the market’s view on its earnings quality, how durable its margins look, and how much growth is built into expectations.
Disco has some support for a premium tag. Earnings have grown 20.2% per year over the past 5 years and are forecast to grow 17.25% per year, with net profit margins at 31.6% compared with 31% a year earlier. Return on equity sits at 25.1% and is projected at 28.5%, which is high and signals that recent profit levels and reinvestment returns have been strong. Against that backdrop, the stock is described as good value versus its peer average P/E of 42.5x, but expensive relative to an estimated fair P/E of 30.6x. That estimated level is one the market could move towards if optimism cools.
The comparison with the wider sector is much harsher. Disco’s 40x P/E is almost double the JP Semiconductor industry average multiple of 20.6x, which suggests the market is assigning a much richer price to each yen of earnings than it does for the typical local chip equipment stock. That gap only looks wider when set against the estimated fair P/E of 30.6x. This implies investors are already paying up materially for growth and profitability that are not forecast to be extreme compared with the broader market.
Explore the SWS fair ratio for Disco.
Result: Preferred multiple of 40x P/E (OVERVALUED).
Still, any stumble in Disco’s precision tools demand cycle, or a reset in market expectations for that 40x P/E, could compress the valuation quickly.
Find out about the key risks to this Disco narrative.
Another View on Disco’s Valuation
A different lens paints Disco as more stretched. Our DCF model points to a future cash flow value of around ¥25,232 per share, well below the current ¥53,850 price. That gap suggests investors are paying a heavy premium. Is the business strong enough to keep justifying it?
Look into how the SWS DCF model arrives at its fair value.
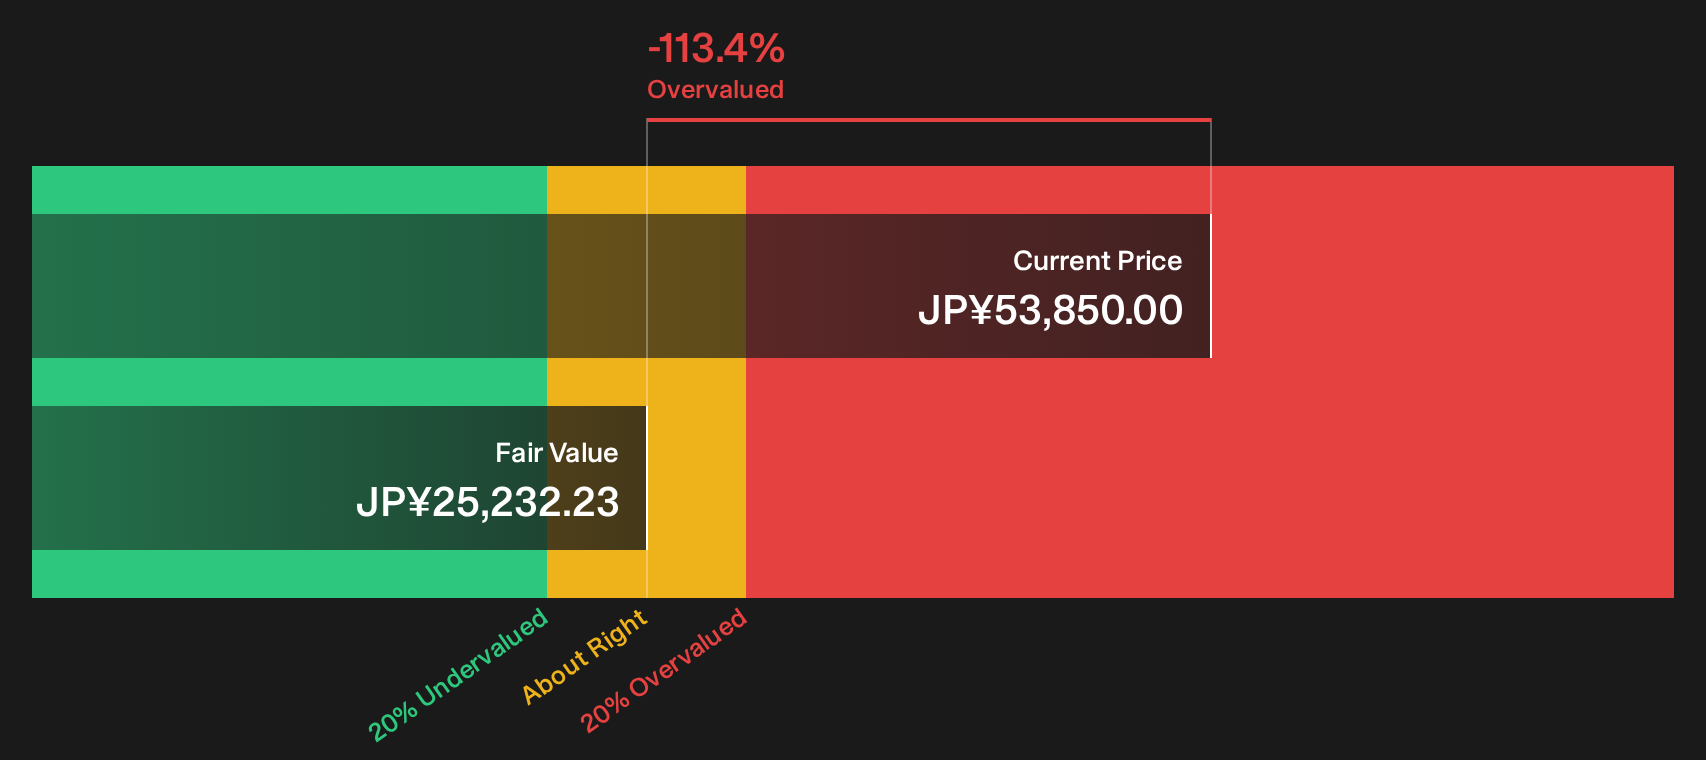
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Disco for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Disco’s valuation and recent share price move make this a good moment to look at the full picture yourself and decide how comfortable you are with the current setup. To weigh both sides of the story in one place, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Disco?
If Disco has your attention, do not stop at one stock. Use the screener to surface other opportunities that fit your style before they move without you.
- Target income resilience by checking companies that appear in the 29 dividend fortresses and see which payouts look better supported by fundamentals.
- Hunt for quality at a lower sticker price with the 13 high quality undervalued stocks and compare how those valuations stack up next to Disco.
- Prioritise sleep-at-night holdings by reviewing the 23 resilient stocks with low risk scores so you are not relying on one high expectation story alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com