


Autohome (ATHM), What Is Behind The Fresh Attention?
Recent trading in Autohome (NYSE:ATHM) has drawn attention after a period of softer performance that left the stock down over the past month and past 3 months, prompting closer scrutiny of its current valuation.
Over the past year, Autohome’s share price has moved lower, with the stock down 11.16% on a year to date basis and the 1-year total shareholder return declining 20.25%, which indicates that recent selling pressure has outweighed any optimism around the business and has led to current valuation metrics coming under closer review.
Pressure test your view on Autohome by comparing it with a curated 33 high quality undervalued stocks that has been filtered for both balance sheet strength and cash flow quality.
Autohome now trades after a long stretch of weaker returns that have reset expectations. Does that reset create a better entry point for new buyers, or does it simply mark a value trap, once the valuation is unpacked next?
Most Popular Narrative: 6% Undervalued
On the most widely followed view, Autohome’s fair value sits at $21.40, only modestly above the last close at $20.15. This perspective puts more weight on how the business mix could shift rather than on a large valuation gap.
The build out of Autohome Mall and new retail pilots, including online car purchase models in multiple cities and the Autohome Good Car offline franchise network, is creating a broader transaction ecosystem that may shift the company’s revenue base from media and leads toward transaction commissions and service fees.
See why 2 investors see Autohome as 6% undervalued.
Result: Fair Value of $21.40 (UNDERVALUED)
Still, the Autohome story can break if China’s car market stays weak for longer and advertising or dealer spending continues to pressure media and leads revenue.
Find out about the key risks to this Autohome narrative.
Another View: Autohome Looks Rich On Earnings
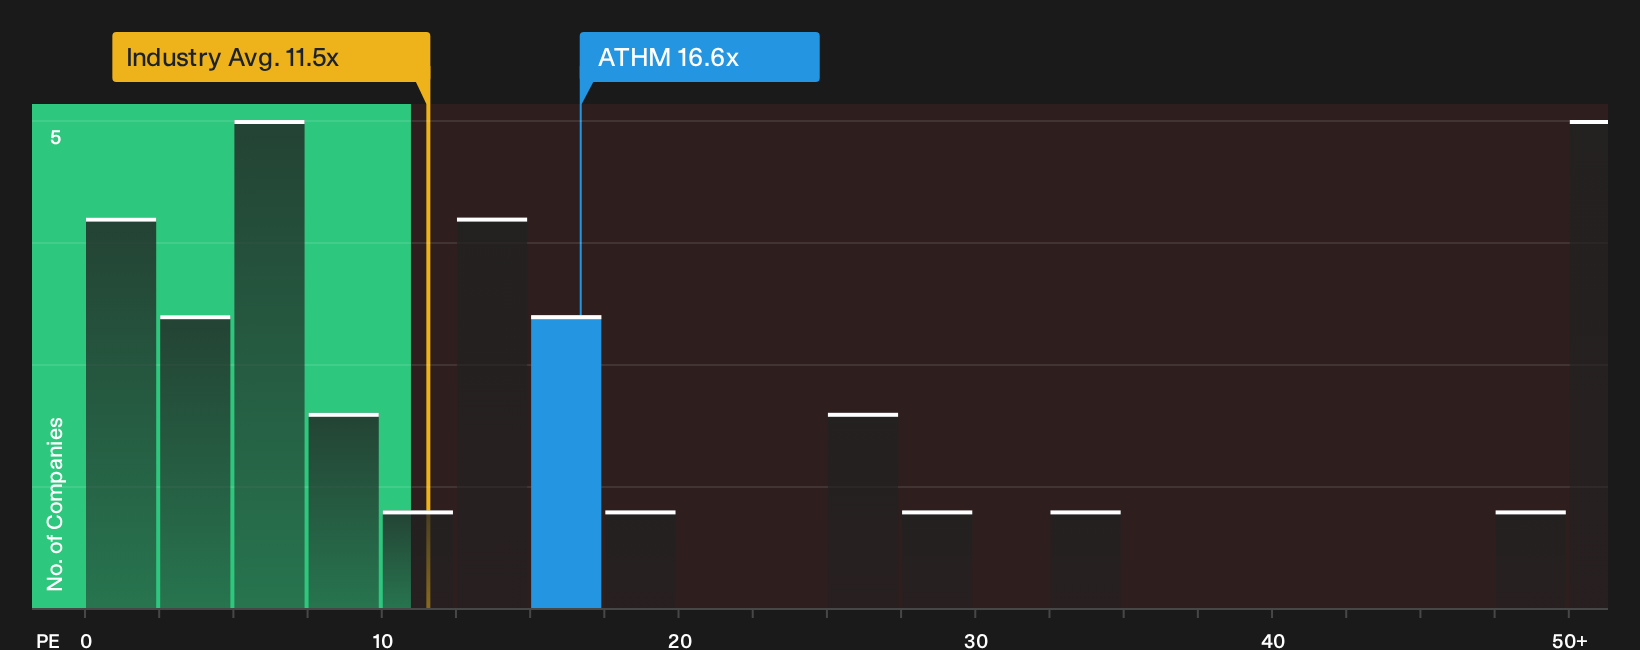
Autohome may look modestly undervalued on fair value estimates, but the earnings multiple tells a tougher story. The stock trades on a P/E of 16.6x, while peers average 13.6x and the fair ratio sits at 14.1x. That premium raises a simple question: Is the extra price worth the slower growth and weaker recent returns?
To pressure test that P/E premium against the underlying numbers and risk profile, review a valuation breakdown built around this fair ratio lens, then compare it with your own expectations for Autohome’s earnings power over the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Autohome can feel unsettling, so move quickly from headline sentiment to your own verdict by weighing both sides of the story with the 2 key rewards and 1 important warning sign.
Looking for more Autohome-sized investment ideas?
If Autohome has sharpened your thinking, do not stop there. Broaden your watchlist with a few targeted filters that could surface your next opportunity.
- Target resilience first and hunt for companies with healthy finances and robust fundamentals through a focused list of solid balance sheet and fundamentals (25 results).
- Zero in on pricing power and search for quality businesses that trade below their estimated worth using a curated 33 high quality undervalued stocks.
- Lean into consistency and scan for potential income anchors with a carefully filtered 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com