


How Investors Are Reacting To United Utilities Group (LSE:UU.) Sewage Spill Scrutiny
- United Utilities Group has come under pressure after releasing untreated sewage into the River Irthing in early October, alongside ongoing heavy capital spend on major projects such as the £260 million Vyrnwy Aqueduct upgrade.
- The same period has brought louder political scrutiny of UK water operators, with talk of revised legislation, tighter controls on executive pay and potential public ownership adding new uncertainty around United Utilities Group's long term regulatory and ownership framework.
- Attention now turns to how United Utilities Group's investment narrative absorbs rising sewage regulation pressure and the threat of tougher water legislation.
United Utilities Group Investment Narrative Recap
For an investor to stay with United Utilities Group, the belief has to be that a heavily regulated water business can keep earning a fair return on a growing asset base while managing higher scrutiny on service and sewage performance. The short term swing factor is whether Ofwat and politicians keep backing the enlarged AMP8 spend despite the Irthing incident and related criticism.
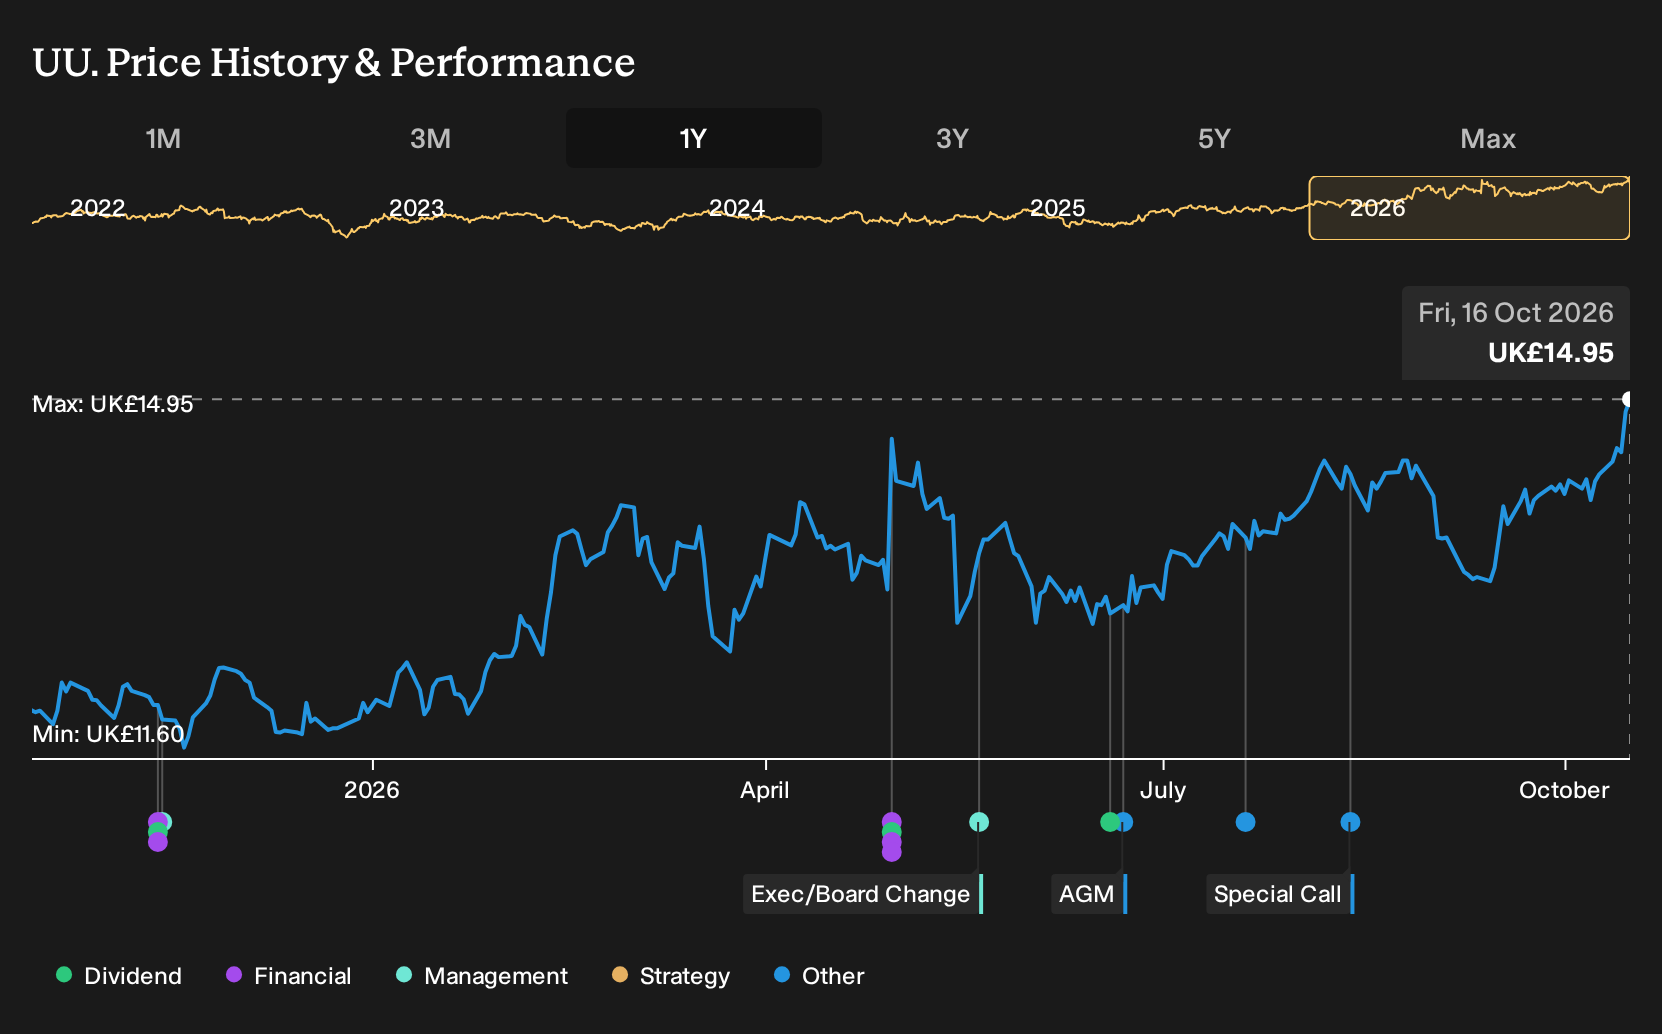
The biggest current risk sits around pressure on funding and costs while credit ratings sit on a negative outlook and operating expenses are guided around £100 million higher, with another £50 million to £60 million in extra depreciation. The recent sewage event and political noise raise the chance of tighter rules, but the immediate share price move of around 1% does not look like a game changer on its own.
The most relevant operational backdrop here is the £260 million Vyrnwy Aqueduct upgrade, now about 60% complete, because it shows where a large chunk of capital is actually going. This work aims to reline 102 km of pipeline to support water quality for around one million customers, which ties directly into service outcomes that regulators track closely.
For you as a shareholder, that project sits right at the intersection of risks and catalysts. Execution helps the AMP8 investment case, supports arguments for future allowed revenue and leans against political calls for harsher treatment of water utilities. Any delays, cost overruns or service issues around Vyrnwy would pull in the other direction and could weigh on perceptions of how United Utilities Group is handling its large £11.5b AMP8 plan.
United Utilities Group's narrative projects £3.1b revenue and £774.7 million earnings by 2029. This projection assumes 5.9% yearly revenue growth and an earnings increase of about £188 million from £586.8 million today.
Uncover why United Utilities Group's fair value is essentially consistent with its current price.
Exploring Other Perspectives
The Simply Wall St Community only supplies two fair value views for United Utilities Group, yet they stretch from about £5.17 to £15.12 per share. That is a wide span for such a small sample. When you factor in sewage regulation risk, AMP8 spending and rating outlook questions, you can see why opinions can diverge sharply.
Explore another United Utilities Group fair value estimate, including one that suggests it could be worth as much as £15.12.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Utilities Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Utilities Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Utilities Group's overall financial health at a glance.
Looking For More Ideas Beyond United Utilities Group?
If the United Utilities Group story has sharpened your thinking on regulation, balance sheets and cash flows, use that same lens on a wider set of businesses with the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, scan a curated set of 7 high quality undervalued stocks that already pass strict cash flow and balance sheet tests.
- If income is a priority, focus on stability first and comb through 2 dividend fortresses that combine higher yields with more resilient fundamentals.
- To keep overall portfolio risk in check, start with resilience and work outward by reviewing a list of solid balance sheet and fundamentals (9 results) that can anchor your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com